
BASF: On the Rise with Natural Gas and Strong Forecasts
The Ludwigshafen-based chemical company is currently working on its global comeback and is pulling out all the stops to achieve it. A recent example is US energy company Cheniere Energy, which now relies on a specialized purification technology from the Palatinate-based firm in Texas. This newly commissioned Durasorb LNG-MAX technology demonstrates that BASF is far more than just a traditional raw materials supplier. This involves the rather complex, if not highly complex, processing of liquefied natural gas. This could, or is intended to, generate high-margin revenue for the company that is, above all, largely independent of the cyclical chemicals business. But investments are also being made at home, as evidenced by the recently modernized acid chloride plant.
The financial rewards of parts of this strategy are already being reaped, as revenue climbed 16% to EUR 17.2 billion in the second quarter. Thanks to this strong operating momentum, the Executive Board raised the EBITDA target for 2026 to a range of EUR 6.9 to 7.7 billion. To keep its shareholders on board, the company is also consistently moving forward with the second phase of its billion-euro share buyback program, with a volume of EUR 1.0 billion.
At the same time, management is streamlining the investment portfolio and recently sold an additional 133 million shares of the British oil and gas producer Harbour Energy, which is bringing fresh cash into the coffers. On the stock market, the share was last trading at just over EUR 52, which still represents a gain of more than 15% year-to-date. However, while more critical voices, such as those at JPMorgan, currently recommend selling, optimistic analysts, such as those at Bernstein, with price targets of up to EUR 62, see upside potential.
BASF is cleverly expanding its high-margin specialty technologies, and if the global economy cooperates, the stock could soon break out of its volatile phase with a very strong upward surge. Above EUR 55, the stock is likely to take off on a technical rally toward EUR 70. So much potential has built up over the past months and years that it could suddenly erupt. Take note and mark your calendars.
Moving on from the chemical industry, we now turn our attention to luxury automaker Porsche.
Porsche SE: Gigantic Leverage
Anyone looking at shares in sports car manufacturer Porsche AG today cannot ignore the overarching holding company Porsche SE. This is where a large part of the current Volkswagen crisis is concentrated. Although the “Future Plan 2030,” recently approved by the VW Supervisory Board, promises a radical restructuring of the group with significant cost reductions, it demands a great deal of patience, nerves of steel, trust, and courage from investors. Anyone investing in Porsche SE ultimately gains enormous leverage over the painful but unavoidable restructuring of the entire “Volkswagen empire.” While the holding company’s majority voting rights are a powerful tool, operationally, the company naturally depends on its subsidiaries.
And that is exactly where things are not going so well right now. Deliveries in China are plummeting because local electric-vehicle competitors are flooding the market with aggressive pricing. At the same time, US tariffs are weighing on vehicles produced exclusively in Germany. The stock market is currently punishing this mix of uncertainty with a downright absurdly low forward P/E ratio of just over 2. Such valuation discounts are crazy and hard to imagine, yet they are real.
The big question now is whether this massive discount on the books will remain an irrefutable fact or dissolve as the first signs of success emerge. At a current share price of just over EUR 29, the disbelief, or, more precisely, the contradiction within the financial expert community, is strikingly reflected. The analysts’ average price target stands at EUR 28, signalling palpable skepticism in the market. Only those who firmly believe in the success of VW’s cost-cutting program would dare to jump in and buy right now. Yet historically, some of the most compelling contrarian opportunities have emerged when sentiment is at its darkest and uncertainty is at its peak.
We leave the crisis-plagued domestic automotive landscape behind and turn our attention to North America. There, an even smaller but technologically exciting player may be on the verge of a breakthrough.
HPQ Silicon: Battery Revolution! Is a Chart Breakout Finally Coming?
Canadian technology developer HPQ Silicon is delivering results. Progress is particularly strong in the field of high-density silicon batteries. The Canadian company already made headlines on August 27 when, together with its technology partner Novacium, it delivered 30 custom-designed battery packs to 3 European drone manufacturers. With this step into the final evaluation phase, HPQ is demonstrating that it is on track toward its goal of commercialization. European high-tech drones urgently need greater range and payload capacity, and that is exactly what these innovative silicon anodes promise.
But that is not all—management is continuing to push ahead. The next piece of news followed on September 10. A collaboration between Novacium and Tokai COBEX is set to establish a European anode material solution. HPQ’s company presentation underscores the potential. From specialized fumed silica to state-of-the-art battery materials to autonomous systems for green hydrogen production from aluminum waste—it is all there. HPQ Silicon is methodically driving the transition from research to lucrative commercialization at an industrial scale.
For technically oriented investors, the situation is getting interesting, as HPQ Silicon’s stock could finally gain upward momentum if it breaks above the current resistance zone marked by the downward-sloping line. The long-awaited breakout would be definitively confirmed if prices sustainably trade above the key level of CAD 0.14—or, even better, directly at CAD 0.15 or higher. At the same time, we see what appears to be reliable downside support down to the CAD 0.12–0.13 range. The recent increase in volume suggests interested buyers are eagerly snapping up these low prices. If the price successfully breaks through the critical zone at CAD 0.155 or 0.165, the stock could rally rapidly toward the upper boundary at CAD 0.20. If things go particularly well and the news flow is supportive, the stock might even quickly reach CAD 0.24 or 0.25, where a previous high was recorded. After successfully overcoming this hurdle, the stock could then continue largely unchecked toward CAD 0.30 from a technical perspective.
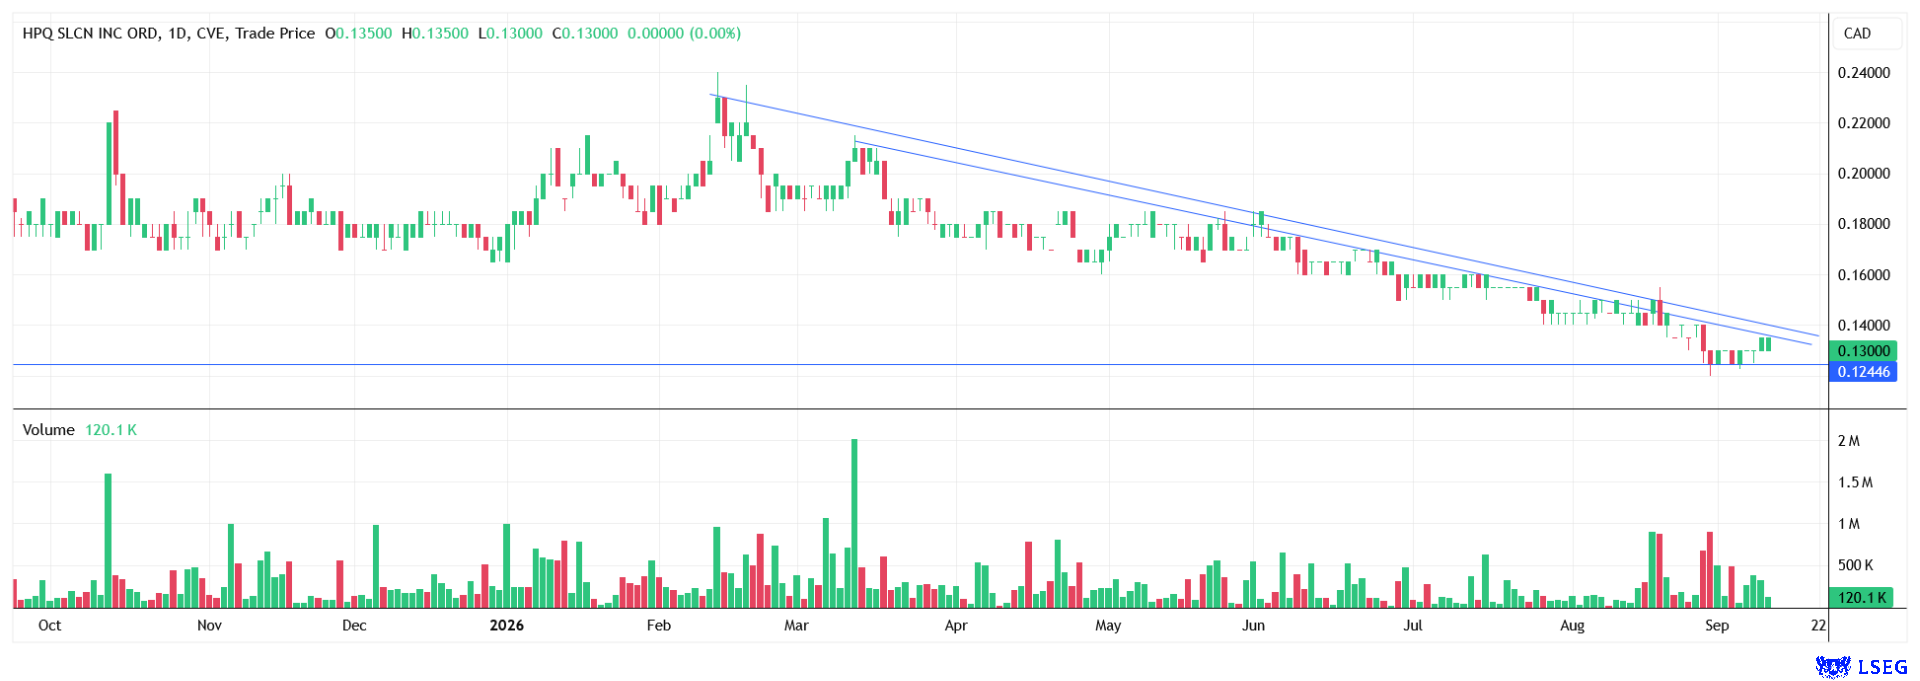
BASF has got it right. The company is streamlining its portfolio and could deliver solid returns to shareholders in the medium term. From a technical analysis perspective, the EUR 55 mark would need to be breached for things to really take off. Porsche SE remains a bet on whether the painful restructuring of the VW Group justifies the enormous valuation discount. Here, pessimism has now reached such a high level that things can almost only get better. HPQ is making a targeted push into future markets with its innovative silicon solutions. With a solid bottoming process and a clearly defined technical setup, the stock offers bold investors an attractive opportunity that could well lead to positive surprises in their portfolios.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.