
Zefiro Methane: The Lucrative Business After the Last Barrel
Methane is an underestimated climate killer. This greenhouse gas is 80 times more harmful than CO₂ during certain periods and continues to escape if oil and gas wells have not been properly decommissioned. Estimates suggest there are more than 2 million such abandoned wells in the US. The problem is so significant that US policymakers have established a multi-billion-dollar budget to address this environmental and societal issue.
As a “hidden champion”, Zefiro Methane addresses this very problem through its US subsidiary, Plants & Goodwin, a well-service provider with more than 50 years of experience. Zefiro’s services range from measurement and monitoring to decommissioning and site restoration. Clients are often from the public sector. Demand is growing as US energy and data centre infrastructure expands. Orphaned well sites can hinder the use of suitable land and must be secured before construction begins.
In addition to acquisitions, such as the recent acquisition of equipment from Viking Well Service, the partnership announced this summer with the industry-renowned Well Done Foundation stands out as a growth accelerator. The foundation is active in 18 US states and has selected Zefiro as its preferred service provider for well plugging. This enables the company to operate nationwide. The strategic and long-term nature of the partnership is a major asset.
In addition, Zefiro is pursuing the emissions credit business for the future. For suitable projects, verified and independently audited emissions reductions can be converted into tradable credits and made fungible as certificates.
In recent weeks and months, the company has reported numerous successes. A state environmental agency in the US Great Lakes region commissioned Zefiro to perform decommissioning work worth over USD 11.5 million. The project is scheduled to begin in November and run through June 2029. Approximately USD 3 million of the funding allocation is earmarked for work through the end of June 2027.
In addition, three federally funded decommissioning projects in Ohio and Pennsylvania were secured. A few days ago, the company entered the Indiana and Michigan markets. This expansion was made possible by equipment from the Viking Well Service fleet, which was acquired in May. In Indiana, Zefiro is working on its first underground carbon storage project. In Michigan, an emergency operation is underway at a well where toxic hydrogen sulfide is leaking. These contracts demonstrate that the company’s existing well expertise can also be applied beyond traditional well decommissioning projects.
Most recently, Zefiro plugged two abandoned oil and gas wells in Cuyahoga Valley National Park near Cleveland, Ohio, under a contract awarded in June 2026. The contract underscores the company’s positioning in the growing market for methane reduction and the remediation of abandoned wells. In US national parks alone, approximately 1,800 such wells have been identified.
The financial results for the fiscal year ended June 30 reflect progress and start-up costs. Revenue increased by 31% to USD 42.5 million. The gross margin improved to 29.2%. Adjusted EBITDA reached USD 3.8 million. The bottom line showed a loss of USD 3.5 million. As of the balance sheet date, cash and cash equivalents totaled approximately USD 1.1 million. As an expert in a large market, the prospects for further growth are strong. In their latest report, analysts at GBC assign a “Buy” rating and confirm that the stock has enormous upside potential at USD 1.50.
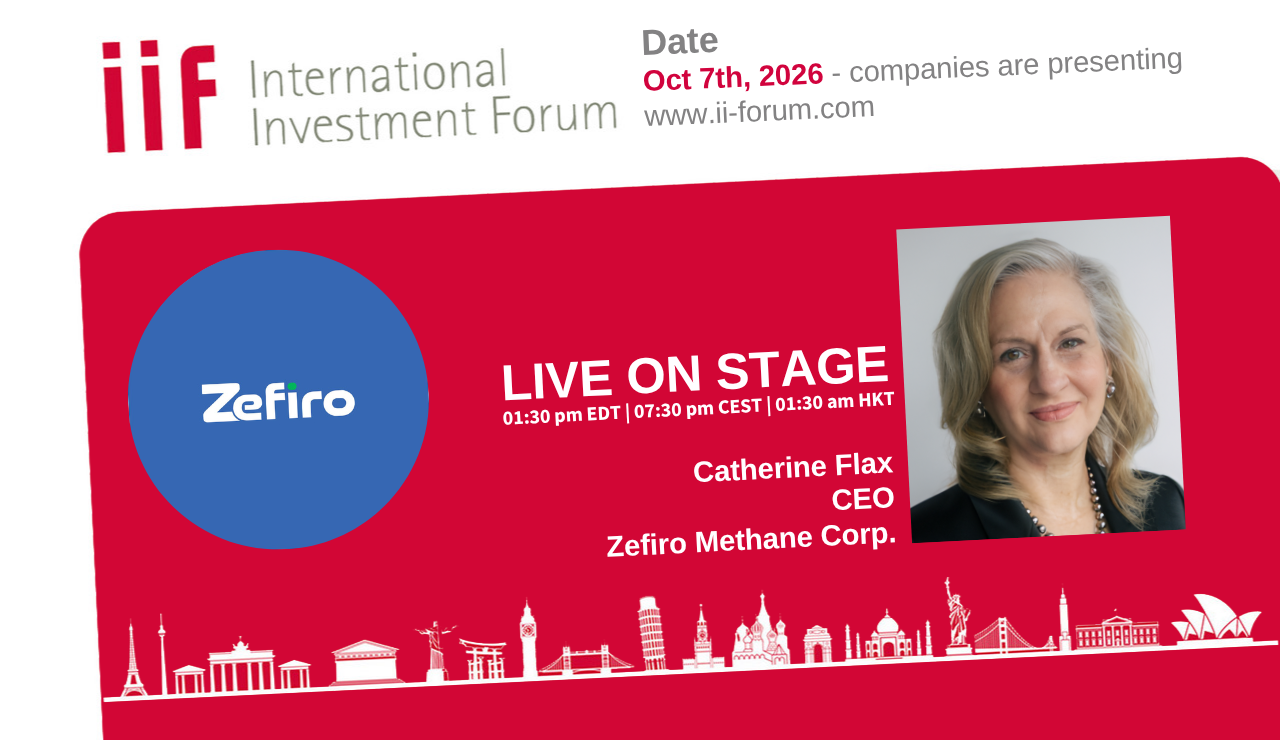
On October 7, CEO Catherine Flax will present live at the virtual International Investment Forum. Participation is free. Register at www.ii-forum.com.
BP: Moderate Valuation
The integrated model combines production, refining, trading and distribution. This creates multiple revenue streams but also demands strong asset availability and capital discipline. In the second quarter, the British company reported adjusted earnings at replacement cost of USD 5.7 billion. Operating cash flow reached USD 10.9 billion. Two opposing trends stood out. High oil and gas prices as well as stronger refining margins had a positive effect, while the operational reliability of the production facilities deteriorated.
Given the size of the portfolio, portfolio adjustments are the rule, not the exception. The announced measures include plans to sell the British North Sea business and the US biogas business Archaea. At the same time, BP is investing in future production opportunities. In early September, Shell announced its planned 50% stake in the Brazilian Tupinambá exploration block. However, BP is expected to remain the operator, and the deal is subject to regulatory approvals.
The shares are moderately valued at a P/E ratio of 6.8 for the current fiscal year and 9.2 for 2027. In addition, an attractive dividend yield of over 4% is on the horizon. The stock has performed well since the beginning of the year, posting a 30% gain. On average, analysts project further upside potential of 15% for the stock.
Shell: 2027 P/E ratio of 9
Shell stands out for its international LNG and trading business. Natural gas is liquefied, transported, and marketed in various sales markets. Production, logistics, and trading are closely intertwined. This opens up opportunities to optimize supply flows but also increases the significance of geopolitical risks.
In the second quarter, the company generated operating cash flow of USD 21.4 billion. Net debt fell to USD 41.8 billion. Shell also announced share buybacks totaling USD 4.2 billion. The annual dividend yield is just over 3%. The P/E ratios, at 7.8 and 9.0 for 2026 and 2027, respectively, are also at a moderate level. According to analysts, the stock still has 10% upside potential in the coming months.
Shell recently announced that it has acquired a 30% stake in the BP-operated Conifer exploration project in the Gulf of Mexico. The first exploratory well is expected in 2027. This creates an option for additional resources.
The high demand for professional well decommissioning provides a solid foundation for Zefiro’s business model. Acquisitions and the partnership with the Well Done Foundation will further accelerate growth. Analysts are bullish. For the industry heavyweights BP and Shell, experts see only moderate upside potential. However, decent dividends offer some consolation.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.