
Southern Copper: Time to take the foot off the accelerator
What happened at Southern Copper in September was historic. The company overtook Rio Tinto as the world’s second-largest mining group by market capitalisation. Unlike the iron ore giant, however, it mainly mines copper. But that is now history again. This has not broken Southern Copper’s upward trend, but market sentiment is subdued following the US midterms. The share is currently trading at roughly its May/June level, although it is still a good way from the March low. From a technical perspective, however, there are no signs of a bottom forming yet.
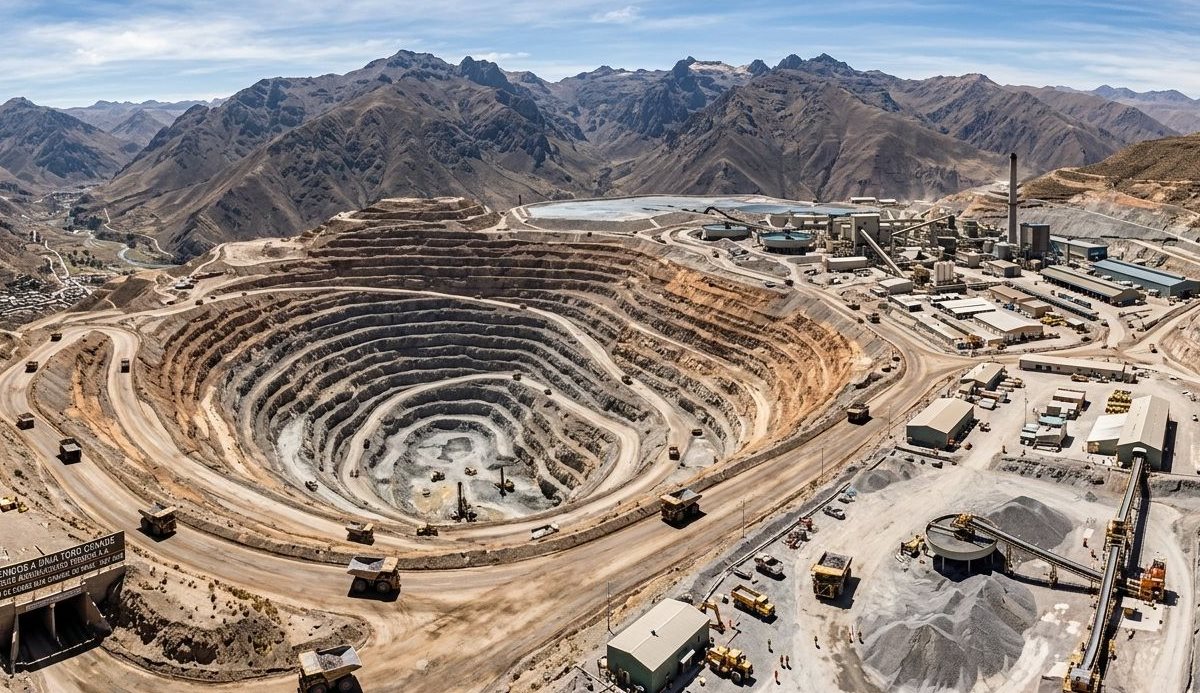
The Phoenix (Arizona)-based company, with its main mines in Peru and Mexico, remains well positioned to benefit from rising copper demand. It is also among the market’s lowest-cost producers. Although it is feeling the current decline in the price of the red metal, this does not threaten the company. Reported costs per pound of copper in the third quarter stood at USD 0.09 per pound (Net Cash Cost). Such low figures are possible because credits from by-products such as molybdenum and silver reduce overall costs. At USD 0.09 per pound, this was incidentally a substantial 77% below the figure for the same quarter of the previous year.
In terms of the figures alone, Southern Copper continues to do well. Total copper production was approximately 232,000 tonnes in the third quarter, a slight year-on-year decline of 1.1%. Revenue between July and September was around 39% higher at USD 4.7 billion, while net profit rose by more than 60% to USD 1.8 billion. The group again improved its EBITDA margin to 64.7%. The money mainly flows into the mines. In Q3, investment was mainly directed towards the Buenavista Zinc (Mexico) and Tia Maria (Peru) expansion projects.
From a purely technical perspective, the share is not yet a buy, and investors should wait for a bottom to form. The stock could fall as far as the March low before finding support.
Power Metallic Mines: Drilling and Waiting
Following the summer high, the blues have recently set in at Power Metallic Mines too. Shares in the Canadian developer have almost halved since their peak in early September. They are currently trading at CAD 0.84, well below the one-dollar mark for the first time in a while. From a technical perspective, there are at least signs of a bottom forming here.
Operationally, Power Metallic Mines established the initial framework with its first resource estimate for the NISK project. The inferred resource totals 4.145 million tonnes of ore, with an average grade of 3.89% copper equivalent or 2.07% nickel equivalent. The lower Inferred category adds a further 0.60 million tonnes of rock grading 4.01% copper equivalent or 1.61% nickel equivalent. Particularly positive: more than 85% of the total resource falls into the higher Indicated category, a result of extensive drilling. Alongside the main metals copper and nickel, this so-called Lion deposit also contains the critical metals platinum, palladium, silver and gold. Most of the resource is located in a near-surface zone, which should reduce future mining costs.
For future production, it is important that Power Metallic Mines can continue to expand the resource substantially. To this end, the Lion zone is currently being explored further at depth. Work is also taking place in the immediate vicinity. The layers beneath the resource, in particular, could still prove interesting for investors. Drilling results here show very high grades in places. The latest drilling results show that looking at depth is particularly worthwhile. At a depth of 845 m, drill hole PML-26-125 intersected an interval grading 14% copper equivalent over 5.70 m.
The first resource estimate for the NISK project will also form the basis for an initial, preliminary economic assessment (PEA). In this PEA, the company will provide initial (rough) data on potential production, mine life, cash flow and costs. Management currently plans to publish this PEA during the first half of 2027.
Those who believe in the long-term rise in copper demand can use Power Metallic Mines’ current situation to take a position. Analysts at Augsburg-based GBC Research recently recommended the stock a Buy. Their price target is CAD 3, representing the potential for the share price to more than triple.
Freeport-McMoran: Copper King Facing Many Challenges
Industry heavyweight Freeport-McMoRan has also faced many challenges recently. Gold sales in Q3 stood at around 105,000 ounces. 60,000 ounces of refined gold from Indonesia had to be shifted from Q3 to the final quarter due to suboptimal delivery timing. Extreme weather conditions such as heavy rain and winds, as well as power outages, also weighed on US production. Significantly higher operating costs due to increases in energy, diesel and labour costs also weighed on results. At least the company remains at the forefront of technology. Improvements to leaching technology provided Freeport with around 55 million pounds of additional copper in Q3 alone.
In terms of the figures, however, the Arizona-based group can be very satisfied thanks to the higher copper price in Q3. Despite the operational challenges, its financial metrics exceeded market expectations. Revenue of USD 7.55 billion was about +8% above the same quarter of the previous year. At USD 0.88, adjusted earnings per share exceeded analysts’ estimates by a tenth. The bottom line was a profit of USD 1.17 billion, up 70% from Q3 last year.
Strategically, Freeport-McMoRan continues to pursue a very investor-friendly policy. Around half of free cash flow is to be distributed to shareholders on an ongoing basis – split between the base dividend, the variable dividend and share buybacks. The rest goes into organic growth. The investment decision for the Bagdad mine expansion in Arizona is expected in the final quarter. The group still has USD 2.3 billion available under its existing share buyback programme, providing structural support for the share price. Recent repurchases were made at significantly lower prices. Freeport shares have lost around a quarter of their value since the August high. A bottom now appears to be forming between USD 58 and USD 60.
Conclusion
Election-related factors are currently moving the copper market, but the long-term trends remain intact. Freeport-McMoRan has faced recurring operational challenges since mid-2025, yet still generates strong cash flows. Power Metallic Mines’ next milestone is due in 2027. A significantly cheaper share price is the attraction here. Southern Copper’s dizzying rally ended abruptly; investors should currently wait for a bottom to form.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.