
Zefiro Methane taps into new revenue stream
Zefiro Methane has provided financial and technical support for the development of a new protocol for generating carbon credits by plugging orphaned oil and gas wells in North America. The framework developed by certification company Isometric provides for the direct measurement of methane emissions from leaking wells before they are sealed and the calculation of avoided emissions over a period of 20 years. Prerequisites for issuing credits include that plugging is not already planned under public programmes and would not take place without funding from carbon credits. An independent audit is intended to ensure compliance with the requirements.
Following the final adoption of the protocol, Zefiro intends to generate and market carbon credits, thereby tapping into a new revenue stream. The company already has relevant experience and has sold credits to institutional buyers such as Mercuria Energy America and EDF Trading in the past. Zefiro could draw on its existing teams, drilling rigs and methane measurement capabilities to implement new projects. Potential proceeds from carbon credit trading would complement the existing business. In the 2026 financial year (ended on 30 June), Zefiro generated record revenue of USD 42.5 million, representing an increase of 31.1 % on the previous year.
The new protocol comes amid a growing market for carbon credits. According to MSCI, capital committed and deployed globally for such credits reached a record USD 22 billion in 2025. By 2030, the market could reach a volume of USD 5 to 20 billion. By 2050, as much as USD 60 to 270 billion is forecast. Isometric is also gaining in importance. The certification company’s clients include Microsoft, Boeing and JPMorgan Chase. In September 2026, Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange, also acquired a stake. Together, the companies aim to combine Isometric’s certification technology with ICE’s market infrastructure.
200% share price upside even without carbon credit trading
Carbon credit trading could therefore drive Zefiro Methane’s growth as early as 2027. Even without this new revenue stream, analysts see considerable potential for growth in revenue, profit and the share price.
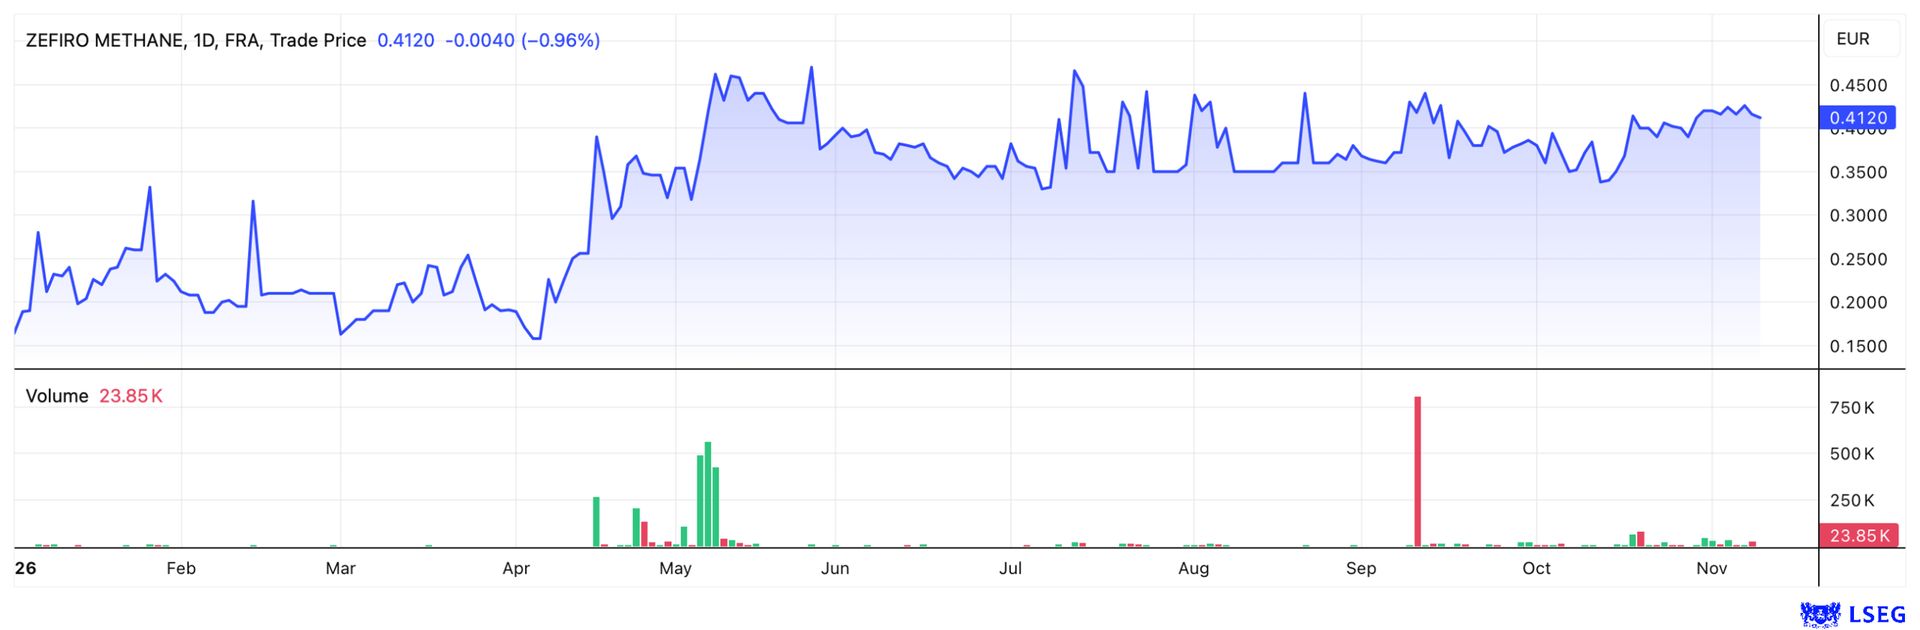
After Zefiro successfully completed a capital increase with gross proceeds of around CAD 5 million at the end of October, GBC Research reaffirmed its Buy recommendation. The fresh capital is to be used primarily to strengthen working capital and for general corporate purposes. Strategic acquisitions are also possible. The analysts see the fair value of Zefiro shares at USD 1.42 (CAD 2.01 or EUR 1.27). The stock is currently trading at EUR 0.42. This puts the share price upside at around 200%.
The analysts also point out that Zefiro has, for the first time, quantified the value of its government-funded contracts for plugging orphaned oil and gas wells. The order backlog amounts to around USD 40 million and extends through June 2029. Of this, around USD 4.9 million is to be completed in the current second quarter of the 2026/27 financial year. The remaining approximately USD 34.6 million is likely to be recognised as revenue predominantly in 2027 and 2028. The largest projects include a three-year contract with the Ohio Department of Natural Resources worth USD 19.6 million and another contract worth USD 11.5 million from the Great Lakes region. In addition, there are three projects in Ohio with a total value of around USD 5 million. This is a solid basis for the expected growth. Contracts from private oil and gas companies are not included in this backlog. Zefiro is also likely to benefit from a “special boom” driven by the expansion of AI data centres and the energy infrastructure required for them. These are often built on disused land in old oil and gas fields, which must therefore be inspected beforehand.
In their investment case, the analysts explicitly cite carbon credit trading as an additional growth driver. As mentioned, it is not yet included in the estimates. The analysts at GBC expect significant revenue and profit growth at Zefiro Methane in the coming years. Following record revenue of USD 42.49 million in the 2025/26 financial year, revenue is expected to rise by around 36% to USD 57.92 million in the current 2026/27 financial year. For 2027/28, analysts forecast USD 66.85 million, and for 2028/29, as much as USD 75.21 million. Earnings are expected to develop even more dynamically. EBITDA is expected to surge from USD 0.60 million in the past financial year to USD 10.02 million in 2026/27 and USD 15.04 million in 2028/29. GBC also expects strong momentum in net income. Following a loss of USD 3.55 million in the 2025/26 financial year, Zefiro is expected to generate a net profit of USD 4.21 million in the current year. By 2028/29, the analysts expect a further increase to USD 8.31 million. Earnings per share are then expected to stand at USD 0.08. This would bring the P/E ratio down from its current level of 10 to 5.
Huge market
The basis for the analysts’ optimism is the enormous market potential. According to GBC, there are around 2 million inactive oil and gas wells in the United States that have not yet been properly plugged. The cost of plugging the documented inactive onshore wells is estimated at around USD 280 billion. An additional approximately 1.2 million undocumented wells are not included in this figure. The US government has allocated around USD 4.7 billion for the remediation of orphaned wells under the Infrastructure Investment and Jobs Act (IIJA). However, this covers only a small proportion of the estimated total funding required. Additional demand comes from private oil and gas companies as well as infrastructure projects, for example the construction of new data centres.
More about the market in the video:
Conclusion
There are many reasons to expect positive business development at Zefiro Methane. A huge addressable market, a successful new management team and a strong market position provide the foundation for further growth. Added to this is a successful buy-and-build strategy that opens up additional growth opportunities. At the same time, the share’s valuation appears anything but demanding in light of analysts’ estimates.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.