
Nvidia: Without its figurehead, but not without a plan
Nobody would have imagined this personnel change a month ago. Jensen Huang, co-founder and the face of Nvidia for 33 years, resigned last Thursday. This followed reports of several affairs, including one with a woman who, according to research by The New York Times, is alleged to have worked for Chinese intelligence. CFO Colette Kress is now leading the group on an interim basis, while former Synopsys chief Harvey Jones is the new chairman of the board. “Nvidia’s strength has always come from its people”, emphasises the woman tasked with getting the AI pioneer back on track. At USD 154.00 (currently EUR 142.00 in Germany), the shares are trading more than a third below their all-time high from early October.
The first test without Huang comes this evening. Nvidia will present its third-quarter results around 22:20 German time, with the analyst conference call starting at 23:00. Revenue of around USD 109 billion is expected, up about 90%, alongside adjusted earnings per share of USD 2.48. An unofficial “whisper estimate” of USD 2.60 is even circulating among traders. The main points of interest will be the outlook and whether rising memory chip costs are weighing on margins. The options market is pricing in a share price move of around 10%, in either direction.
Although some analysts have cut their targets, they still see considerable upside potential. The average price target is USD 255, around 60% above the current level. Even US investment firm Robert W. Baird, which downgraded the shares to Neutral, and Bernstein believe they could reach USD 200, while UBS, Jefferies and Goldman Sachs see them reaching as much as USD 300. Although Morgan Stanley analyst Joseph Moore described Huang’s leadership as “crucial to the company’s direction”, he maintains his Overweight rating and a USD 267 price target. With a 2027 price-to-earnings (P/E) ratio of 17, the shares are trading well below their historical average. The technology, close customer relationships and a well-established management team support the case that Nvidia does not depend on a single person. Whether the resignation presents a buying opportunity should become clear tonight.
Micron Technology: Share price weakness without a scandal
What could become a cost problem for Nvidia is a business opportunity for Micron. The US group manufactures RAM and flash memory, with HBM in particularly strong demand. The abbreviation stands for “High Bandwidth Memory”, stacked memory chips that supply AI processors with data particularly quickly. At Micron, nobody had to resign to send the share price tumbling; the Democrats’ triumph in the US midterm elections was enough. There are now fears of delays or even construction halts at data centres. From a high of USD 1,255 in June, the shares have fallen to USD 735 (around EUR 665), a decline of more than 40%.
The figures were not to blame. In the 2026 financial year (ended on August 31), revenue surged from USD 37.4 billion to USD 133.2 billion, while earnings per share rose by just over 800% to USD 75.52. Revenue in the fourth quarter alone was USD 54.2 billion, compared with USD 11.3 billion a year earlier. For the current first quarter, management is forecasting revenue of USD 61.5 billion and earnings per share of USD 37.84. That would be about half as much in three months as in the entire previous year. Multi-year offtake agreements with customers are intended to secure more than 35% of revenue through 2030, while HBM production for 2027 is largely sold out. Instead, doubts over how long spending on AI data centres and rising memory prices will continue in the changed political landscape have weighed on the shares. Bank of America subsequently removed Micron from its list of top picks. Added to this is a trade union dispute in Taiwan, where a large proportion of DRAM chips are produced.
Most analysts remain unmoved, however. Their average price target is USD 1,493, more than double the current share price. Even the most cautious target from Goldman Sachs at USD 1,250 would leave just over 70% upside potential. UBS considers even USD 1,625 achievable. With a P/E ratio of 4.2 for the current financial year, the stock market appears to be pricing in the end of the memory boom already. From December 9, the group will also be permitted to buy back up to USD 35 billion of its own shares.
Power Metallic Mines: Good news, few listeners
Memory chips require high-purity metals, and Micron is now also investing in domestic raw material supplies. No data centre, power grid or electric vehicle can function without copper. This is where Power Metallic Mines comes in. The Canadian exploration company is exploring the Nisk project across an area of around 330 km² in northern Québec. At its heart is the Lion Zone, a deposit containing copper, platinum, palladium, gold, silver and nickel. Such polymetallic deposits containing several valuable raw materials in the rock are rare.
The business model is clearly defined. Power Metallic is not yet mining anything. Value is created through drilling that progressively confirms and expands a deposit. The maiden resource estimate for the Lion Zone was published in September: around 4.75 million tonnes of rock with an average copper equivalent grade of 3.9%. This metric converts all the metals contained into copper. Just over 85% of the tonnage is classified as “indicated”, meaning it is well supported by drilling. Just under 60% is close enough to surface for open-pit mining. In laboratory tests, more than 98% of the copper could be recovered. The location is suitable too: a main road and a substation are in the immediate vicinity.
The resource is therefore unlikely to end there. In September, the company reported an intersection just under 800 m below surface, around 25% deeper than the existing estimate extends. Management believes it is possible to increase the resource by up to 50%. The next step, in early October, is for engineering firm BBA to prepare a Preliminary Economic Assessment (PEA). It is intended to quantify mining, processing, capital expenditure and operating costs for the first time. “By commissioning BBA, we have strong engineering expertise behind our next major milestone”, says CEO Terry Lynch. The results are expected in the first half of 2027.
Prominent shareholders, planned Nasdaq listing
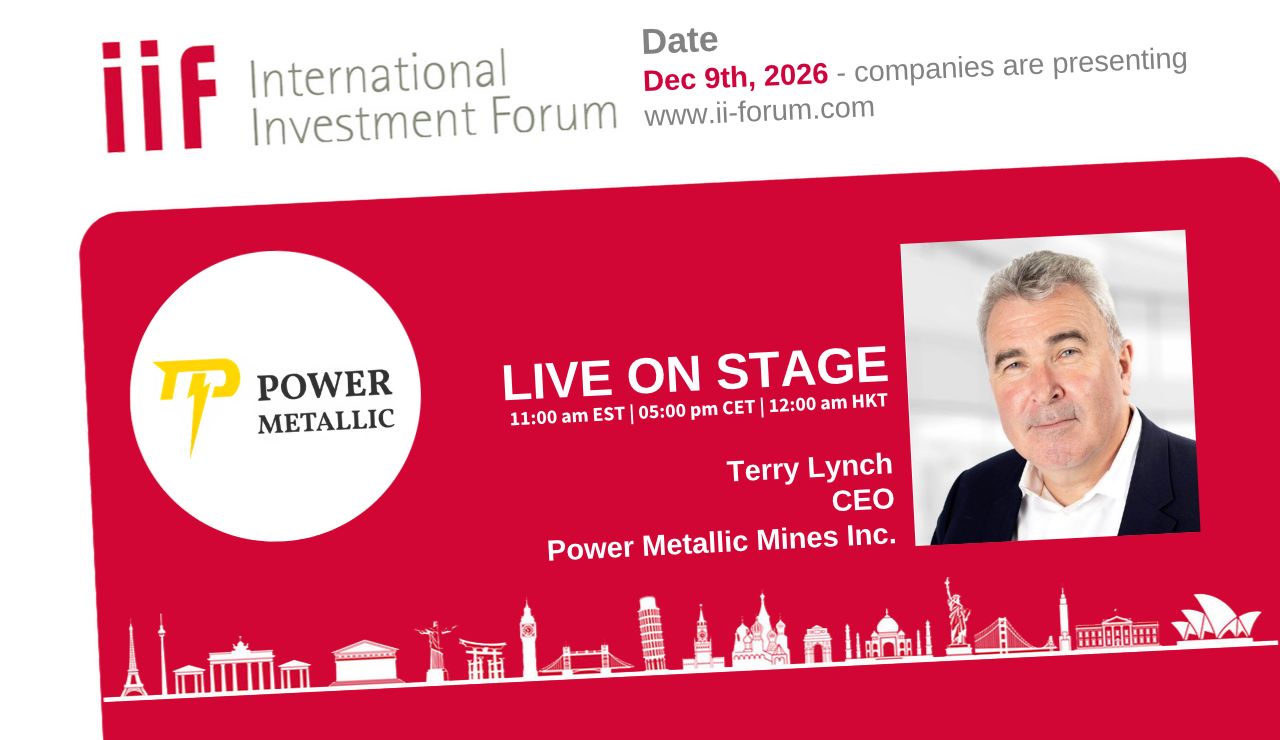
Funding for this stage is available. A capital increase in June brought in CAD 28.2 million, with commodities legend Eric Sprott also buying in. Shareholders also include heavyweights such as Robert Friedland and Rob McEwen. A Nasdaq listing is also planned to make it easier for major US investors to invest. Lynch wants to develop the mine himself rather than sell the project. He will explain his strategy on Wednesday, December 9, at 5 pm at the International Investment Forum (IIF), one of the few specialist conferences also open to retail investors. Follow this link to register: https://us06web.zoom.us/webinar/register/WN_e8tHYT16Tzy7t9vDH3fLkw#/registration
The share price does not come close to reflecting the company’s potential. The annual high was CAD 1.73 in January, and in early September the shares still cost just over CAD 1.50. Today they stand at CAD 0.80 (around EUR 0.50 on German trading venues). The market capitalisation is therefore now only around CAD 207 million. Some of the selling followed the resource estimate, whose tonnage was slightly lower than some had hoped. By contrast, the market has ignored the strong deep drilling result and the start of the PEA.
Analysts’ assessments stand in stark contrast to the share price performance. Augsburg-based research firm GBC recently raised its valuation of the project from CAD 570 million to CAD 660 million. That is more than three times the current market capitalisation. Accordingly, GBC confirms its Buy rating with a price target of CAD 3.00, almost four times the current share price. Roth Capital Markets is aiming just as high. London-based Hannam & Partners puts its target at CAD 2.70. Even the lowest target, CAD 2.00 from Noble Capital Markets, is 150% above the current share price. Further drilling and laboratory results before the end of the year could provide the next occasion to take a fresh look at the shares.
Rheinmetall: Not indifference, but disappointed love
The supply of raw materials has long been an essential part of security policy too. Few companies have benefited as much as Rheinmetall in recent years from the need to protect Europe against potential threats. For a long time, the shares were regarded as a safe bet in the DAX: government orders in a disastrous geopolitical environment seemed like a guarantee of growth. But the former stock market darling has recently disappointed those hopes. In January, Rheinmetall shares still cost EUR 1,965.00; today they stand at EUR 789.00. That represents a 60% decline. The nine-month results on November 5 triggered the latest downward move. Group management lowered its revenue forecast for 2026 to around EUR 13.2 billion, having already tempered expectations in August because of the halted F126 frigate project. The operating margin is now expected to be around 18.5%, down from the previously expected 19%.
The cause is delays, not a lack of demand. The major order for Boxer wheeled armoured vehicles for the Bundeswehr will not be placed until 2027, while acceptance tests for artillery ammunition are also being delayed. Bank of America and JPMorgan dropped their Buy recommendations. Berenberg also expects Rheinmetall to cut its 2030 revenue targets by 14% at its capital markets day on November 26 and 27. In the first nine months, revenue nevertheless rose 38% to EUR 8.4 billion, while earnings per share almost doubled to EUR 14.44. The order backlog stands at EUR 78 billion.
The now attractive valuation is noteworthy. At a P/E ratio of 15.5 based on consensus estimates for 2027, the shares are trading well below their three-year average. On average, analysts put fair value at EUR 1,461, almost 85% above the current share price. Even Berenberg gives a target of EUR 900 in its Hold recommendation. Bernstein Research likewise does not recommend buying the shares, yet still puts fair value at EUR 1,000. Morningstar puts it as high as EUR 2,380. According to Berenberg, the valuation discount to comparable defence groups has now reached 35%.
Undervaluation, lost confidence and optimistic analysts
The four shares have fallen for very different reasons. For Nvidia, it was a scandal; for Micron, fear of the end of the AI boom; for Power Metallic Mines, simple indifference; and for Rheinmetall, a forecast that had to be lowered twice. What they have in common is that analysts see fair value well above the current share price. Nvidia’s figures this evening will provide some initial clarity, as will Rheinmetall’s capital markets day in late November. In both cases, management’s main task is to regain lost confidence. By traditional metrics, Micron Technology appears the most undervalued, with a P/E ratio of just over 4. Power Metallic Mines, in turn, offers the greatest leverage. The economic assessment in the first half of 2027 could show what the copper deposit in Québec is actually worth. The price targets from GBC and Roth Capital Markets are almost four times the current share price.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.