

Commerzbank: UniCredit Takeover Battle Puts Investors’ Nerves to the Test
Commerzbank’s stock has recently suffered several setbacks and come under noticeable selling pressure. With daily losses recently reaching nearly 3% at times, the stock slipped toward EUR 38, making it the worst performer on the DAX on some days. One of the main reasons for the gloomy sentiment was the revised outlook from several leading analyst firms. Both RBC and Deutsche Bank have withdrawn their “Buy” recommendations and now rate the stock as “Neutral”. The experts emphasize that much of the previous share-price drivers, such as higher interest income and higher dividends, are now priced in.
Operationally, the Frankfurt-based group is attempting to counter this trend, but the shadow of the looming takeover is impossible to ignore. The company points to its ongoing share buyback program, under which it has already repurchased 6.25 million shares as of the end of September. In addition, management is optimistic about new growth areas such as the planned retirement savings account, in which, according to a YouGov survey, 38% of respondents have expressed interest. Nevertheless, RBC lowered its price target from EUR 43.00 to EUR 40.00, as rising equity costs are limiting earnings potential.
However, the dominant factor in the market remains the aggressive expansion strategy of the major Italian shareholder, UniCredit. Its CEO, Andrea Orcel, is seeking control and is already aiming to hold an extraordinary shareholders’ meeting in January. UniCredit plans to replace all ten shareholder representatives on the supervisory board and is seeking to oust Commerzbank CEO Bettina Orlopp. Although the German government is demanding binding commitments to maintain Frankfurt as a business location, it has little legal recourse to stop the Italians’ actions. For investors, this ongoing power struggle is significantly increasing uncertainty.
And from a technical analysis perspective, the momentum now seems to have finally run out. The question every investor is asking is this: What is the downside risk versus upside potential? The risk-reward ratio simply no longer makes sense: risking EUR 5 or more for a potential EUR 2 gain.
While Commerzbank is grappling with analyst downgrades, its Italian suitor, industry leader Deutsche Bank, just around the corner in Frankfurt, faces a very different set of challenges stemming from the interest-rate environment.
Deutsche Bank: Rate-Cut Blues Halt the Frankfurt Giant’s Uptrend
After months of stellar performance, Deutsche Bank’s stock is noticeably losing momentum. In early September, the stock still climbed to a multi-year high of EUR 35.84 before a steep correction of over 10% set in, pushing it toward EUR 30. The stock is now trading at around EUR 30.50 and has already broken below the 50-day SMA. However, the 200-day SMA was successfully tested. The sudden shift in sentiment is due to sharp price declines in the international bond market, which could leave a noticeable mark on the balance sheet.
Financially, the group has fulfilled its capital return obligations on schedule. The share buyback program announced on August 24 was completed on September 25. In total, Deutsche Bank acquired 15.06 million of its own shares for about EUR 500 million at an average price of EUR 33.19. However, the balance sheet risks posed by rising government bond yields currently outweigh the reduced number of shares. The yield on 10-year German government bonds rose to over 3.60%, which could significantly weigh on the value of existing bond portfolios.
Despite the short-term selling pressure, many analysts remain surprisingly confident about the banking giant’s long-term potential. Experts at Goldman Sachs and JPMorgan continue to see the fair price target, on average, at just over EUR 42. However, a sustained slide below the EUR 30 mark could trigger a decline toward EUR 25. Only a return above the EUR 32.50 zone would sustainably brighten the chart picture again. Investors may want to wait for a clear bottom to form before entering the market.
Moving from German financial institutions to commodities —specifically tungsten, a material urgently needed by both the defense industry and AI developers.
Almonty Industries: Rapid Consolidation Creates New Upward Momentum
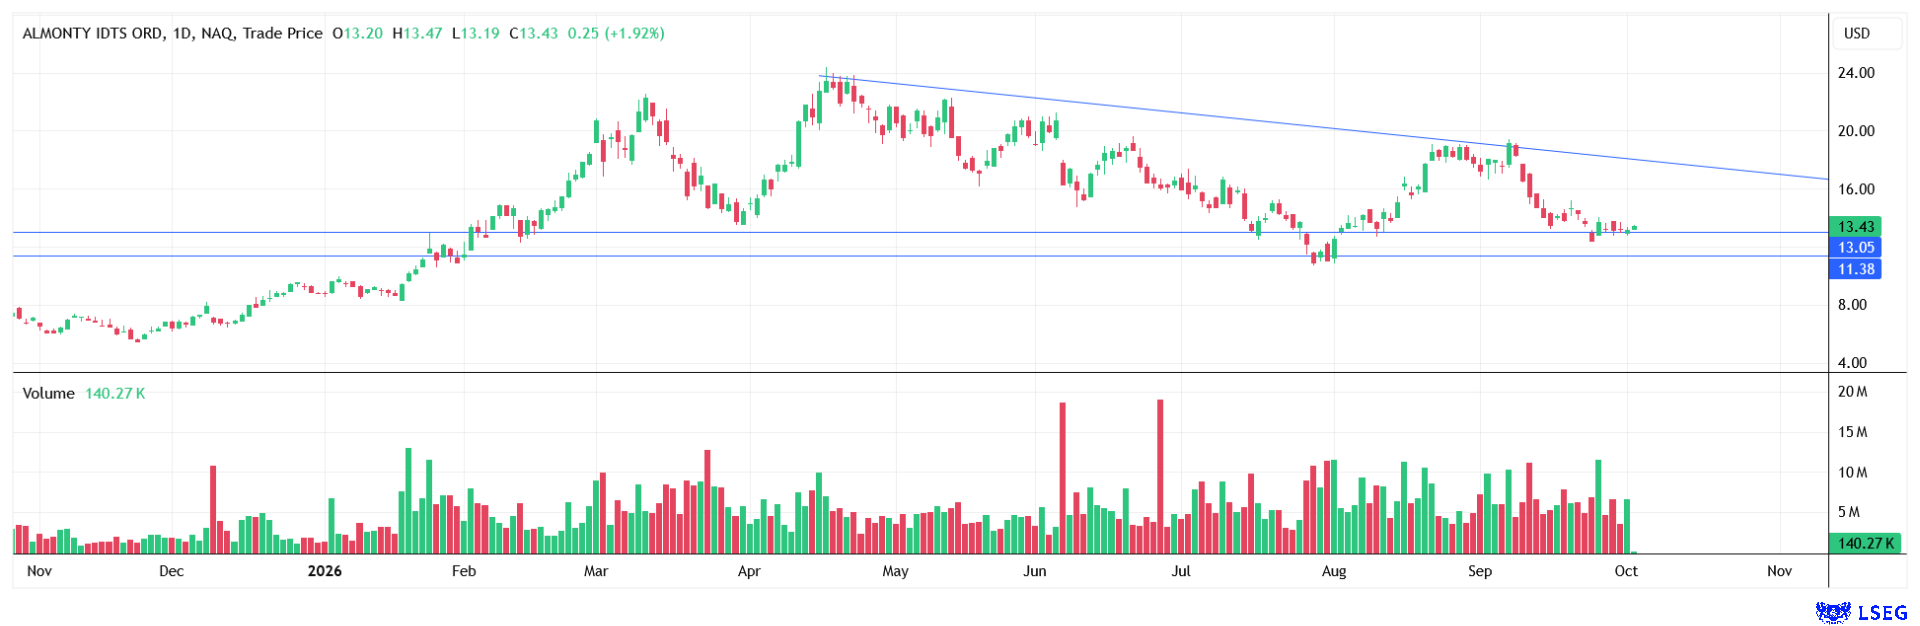
Almonty Industries, a tungsten specialist headquartered in the US with Canadian roots, is currently attracting increased attention from strategic investors in the financial markets. After an impressive rally that propelled the share price from just under USD 11.00 to a high of approximately USD 19.50, a rapid, sharp consolidation phase set in. In recent trading days, however, this pullback has slowed noticeably, suggesting the selling wave may soon come to an end. The stock is currently stabilizing within a range between USD 13.00 and USD 14.00.
Fundamentally, the company’s latest news reinforces operational confidence. In the most recent CEO newsletter dated September 26, CEO Lewis Black expressed extreme optimism regarding progress on the flagship project in South Korea. The restart of the Sangdong mine, which has already begun, is expected to make Almonty one of the world’s leading tungsten producers outside of China in the future. As global efforts to secure critical raw materials intensify, the group’s strategic focus is quickly gaining importance.
From a technical analysis perspective, the current market situation offers an extremely attractive risk-reward ratio for bold investors. Strong horizontal support shields the stock in the range of USD 13.00 to USD 14.00, with another safety net below at USD 11.50 to USD 12.50. A renewed surge in momentum could quickly propel the price toward the upper boundary of the wedge formation at USD 17.00 to USD 17.50. If the stock manages a sustained breakout above this hurdle, prices could quickly reach USD 18.00 to USD 20.00. Based on the broader chart pattern, there is even upside potential of up to USD 24.00 in the medium term.

This is also supported by a recent report from the US research firm Stifel.
On September 25, 2026, the firm initiated coverage of Almonty Industries stock with a clear “Buy” recommendation and a price target of USD 25.
Because of the protracted takeover negotiations with UniCredit, Commerzbank remains a volatile speculative investment with elevated risk for now. At Deutsche Bank, weakness in the bond market is weighing on momentum, so investors should wait for a clear bottom to form before entering the market. Almonty Industries, on the other hand, offers a promising technical setup for opportunity-seeking commodity investors following its recent consolidation.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.