

Nel ASA: The hydrogen pioneer in a tough fight for survival
Former stock market darling Nel ASA simply cannot escape the deep doldrums of the hydrogen industry. The share price has been in a downtrend for months and is trading dangerously close to its multi-year lows, just below EUR 0.17. While green energy dreams repeatedly spark brief flurries of excitement in the markets and spikes in the share price, sobered investors are looking at a company that remains deeply in the red operationally and must face the harsh realities of the market.
A look at the latest quarterly figures reveals the dramatic situation facing the Oslo-based group. Revenue from customer contracts plunged 63.0% to just NOK 112 million in the third quarter, missing market expectations by miles. Although the proton exchange membrane segment is growing, the long-established alkaline electrolyser business slumped by more than 90% and dragged the overall operating result down. On the bottom line, Nel posted a net loss, while its cash buffer stands at NOK 1,078 million and, at an unchanged rate of cash outflow, could theoretically last for around another 18 months.
Investors in Nel also face a tough task: navigating between technological dreams for the future, which inspire hope and acute time pressure. With a fairly modest market capitalisation, the stock is an interesting but also quite speculative investment, driven heavily by trader sentiment and political impulses. The stock, which analysts mostly view cautiously, offers exciting prospects thanks to its healthy order backlog and strategic partnerships, but without a sustained turnaround in operating margins and fresh tailwinds, the situation remains highly precarious.
The shares are trading below both key moving averages (the 50-day and 200-day SMAs). Until this changes, the downtrend remains intact, and hope continues to fade with each passing day.
From Nel, our path leads us to the hallowed halls of German premium sports car manufacturer Porsche, where the long-established group is battling declining sales volumes and tough structural reforms.
Porsche AG: The luxury sports car manufacturer seeks to weather the crisis with ironclad cost-cutting measures
Luxury sports car manufacturer Porsche is also clearly feeling headwinds in global automotive markets, particularly in crisis-hit China. Following declining deliveries in the current year, the long-established Zuffenhausen-based group is facing palpable pressure and growing scepticism on the stock market. Nevertheless, management has so far shown resilience by explicitly confirming the full-year forecast despite a noticeable decline in sales volumes. Or is this merely a bluff and a high-stakes gamble?
Operationally, the financial metrics for the first nine months of 2026 look quite robust, even if the dip is unmistakable. Group revenue reached EUR 25.28 billion, while the operating result came in at EUR 1.74 billion and worldwide deliveries fell by 16.0% to around 179,000 vehicles. In light of these figures, Porsche is pursuing a drastic restructuring, with the model range set to shrink by 20% and management ranks to be cut by 40% by 2035 to bring the break-even point sustainably below 200,000 units. With an operating margin of over 4%, the third quarter at least showed that core earnings power has remained intact.
Experts’ views on the stock market currently differ widely, as illustrated by price targets ranging from just under EUR 40 to an optimistic level well above EUR 60. While 2027 is seen as a painful transition year and a possible low point, long-term investors are positioning themselves for the period from 2028 onwards. Those who regard the current period of weakness and the tough cost-cutting programme as a necessary evil are getting a world-famous premium stock with substance here, but may have to brace themselves for further bumpy quarters in 2027 as well. Interesting for long-term investors.
Those looking to turn their backs on the tough and currently challenging automotive industry and volatile hydrogen stocks may find a very different risk-reward profile in the commodities sector, perhaps with a smaller gold exploration company in West Africa.
Desert Gold: On the Road to Becoming a Gold Producer with Multibagger Potential
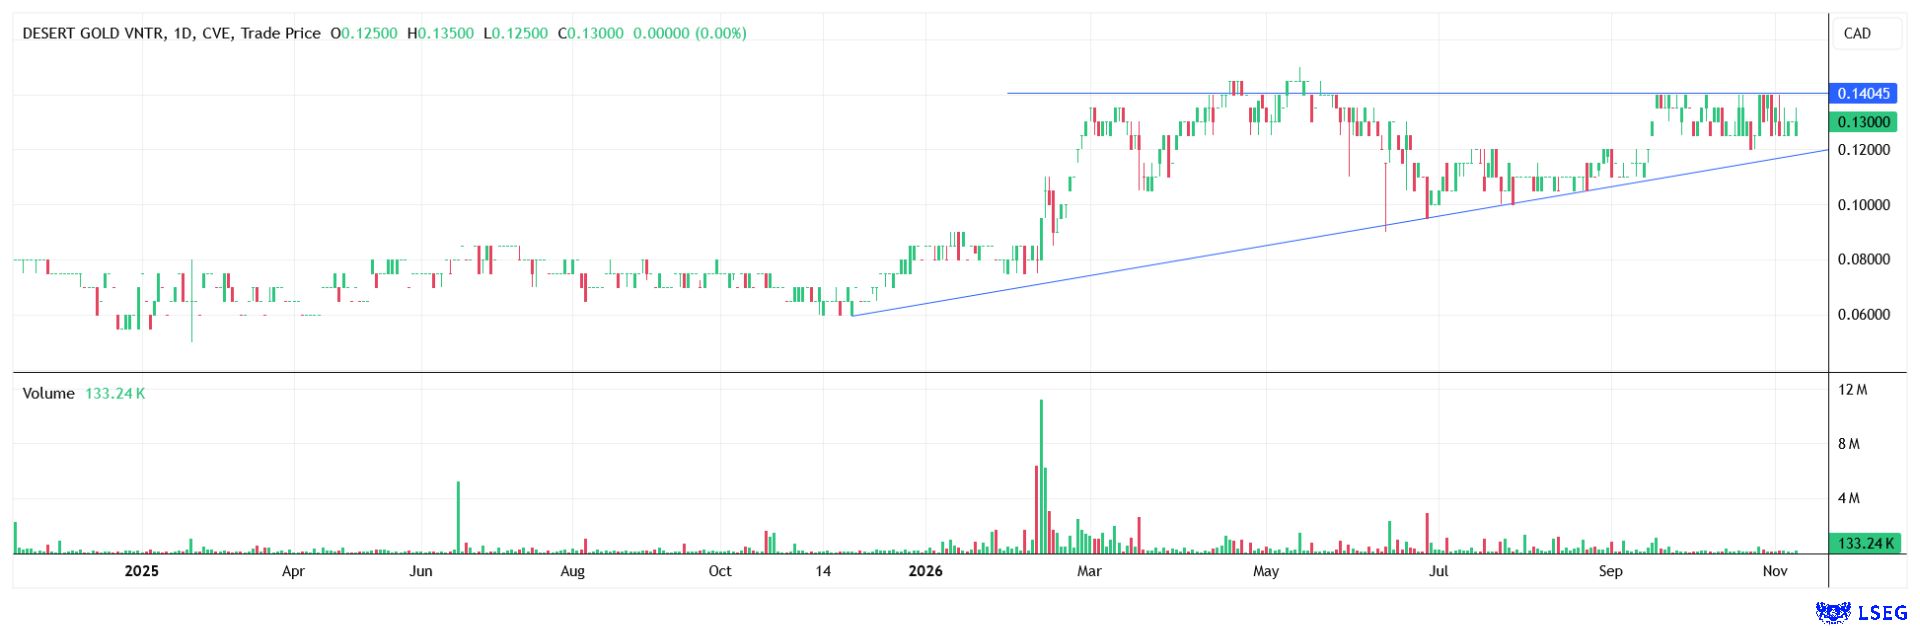
Canadian gold developer Desert Gold Ventures plans to move up from being a pure explorer to a producing company. This puts the stock squarely in the spotlight for speculative retail investors. Currently trading at a modest CAD 0.13, the company offers an extremely exciting starting position for the coming months, both technically and fundamentally. Driven by the latest operational progress in Mali, the stock is approaching a decisive catalyst that could change the company’s valuation for the long term.
Progress made in September 2026 at the company-owned project is also central to recent developments. The gravity processing plant and a powerful generator have been successfully delivered to the site, setting the stage for targeted gold production. Despite difficult logistical conditions and regional challenges, management is consistently driving the project forward. Once commissioned, gold should be extracted with the promising economics and low capital costs outlined in the preliminary economic assessment (PEA). The team is working purposefully towards the first cash flow.
The return potential of this stock is considerable given GBC analysts’ price target of CAD 0.93 (EUR 0.59). Should the share price sustainably overcome the technical resistance at CAD 0.15, the path upwards would, from a technical perspective, be completely clear initially to the CAD 0.30 level and subsequently towards GBC’s price target. While this is a speculative investment with project-specific risks in West Africa, production that may start soon, several exploration opportunities and solid support make Desert Gold one of the most exciting opportunities beyond the major indices.

Conclusion:
Nel ASA remains a high-risk restructuring project in the hydrogen sector, where liquidity is shrinking, and the turnaround has yet to be proven. Porsche AG is navigating a tough automotive crisis and offers long-term investors solid fundamentals despite declining sales volumes. With the planned start of production in Mali, Desert Gold combines exciting prospects with enormous share price upside to GBC’s target of CAD 0.93 for risk-aware investors.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.