

Major Development at Desert Gold Ventures
The exploration company reported significant progress yesterday in establishing its first gold production at the 100% owned SMSZ project in western Mali. The stock responded in early trading with a jump of nearly 5%. The gravity processing plant, with a planned capacity of 200 metric tons per day, and a 650-kVA generator have now arrived at the Barani site.
Access roads have been improved, and key construction materials and other resources have been delivered to the construction site. After delays caused by ocean freight, regional fuel shortages, construction materials and the rainy season, the company can now move full steam ahead with gold production.
Starting production with a relatively small gravity processing plant makes strategic sense. Desert Gold can initially gain experience in mining, processing, logistics and cost control. In addition, production generates important operating cash flows. It can use these cash flows to finance further drilling programs and resource expansions without major capital increases.
For Barani and Gourbassi, the updated NI 43-101 PEA envisages a 10-year oxide open-pit mine. At a gold price of USD 2,850 per ounce, the after-tax NPV10 is reported at USD 61 million with an internal rate of return (IRR) of 57%. At USD 4,070 per ounce, the NPV10 rises to USD 124 million and the IRR to 101%.
Gold Production Set to Begin in Q4
The plant is scheduled to begin operations by the end of October. This will be followed by ramp-up and the first processing steps in November. Desert Gold is thus sticking to its goal of producing gold for the first time in the fourth quarter of 2026.
The water supply, critical for a project of this kind, also appears to be secured. Positive flow rates were measured in three out of four drill holes. The site’s operational environment is also positive. So far this year, there have been no reports of project-specific safety incidents, labour issues, or conflicts with local communities. With the end of the rainy season, management also expects a noticeable acceleration of work. The upcoming transition from construction to commissioning would be an important step in Desert Gold’s journey from an exploration company to a producing gold company.
New Acquisition Potential
With the start of production, Desert Gold could not only make the transition from an explorer to a potential producer but also increase the attractiveness of the entire project. After all, Barani East is just one component of the larger SMSZ project. Currently, SMSZ already has a resource of approximately 1.2 million ounces of gold. Management repeatedly points out that the resource is likely to be significantly larger.
With the start of production, takeover speculation should also once again become a potential driver of the share price. Large mines operated by Allied Gold, B2Gold and Barrick Mining are located in the immediate vicinity. B2Gold is currently expanding its presence and received a new mining license for Menankoto in August 2026. Chinese gold producers are also seeking to establish a foothold in the region. Zijin Gold, for example, failed in its attempt to acquire Allied Gold earlier this year.
Is the Stock Poised to Multiply in Value?
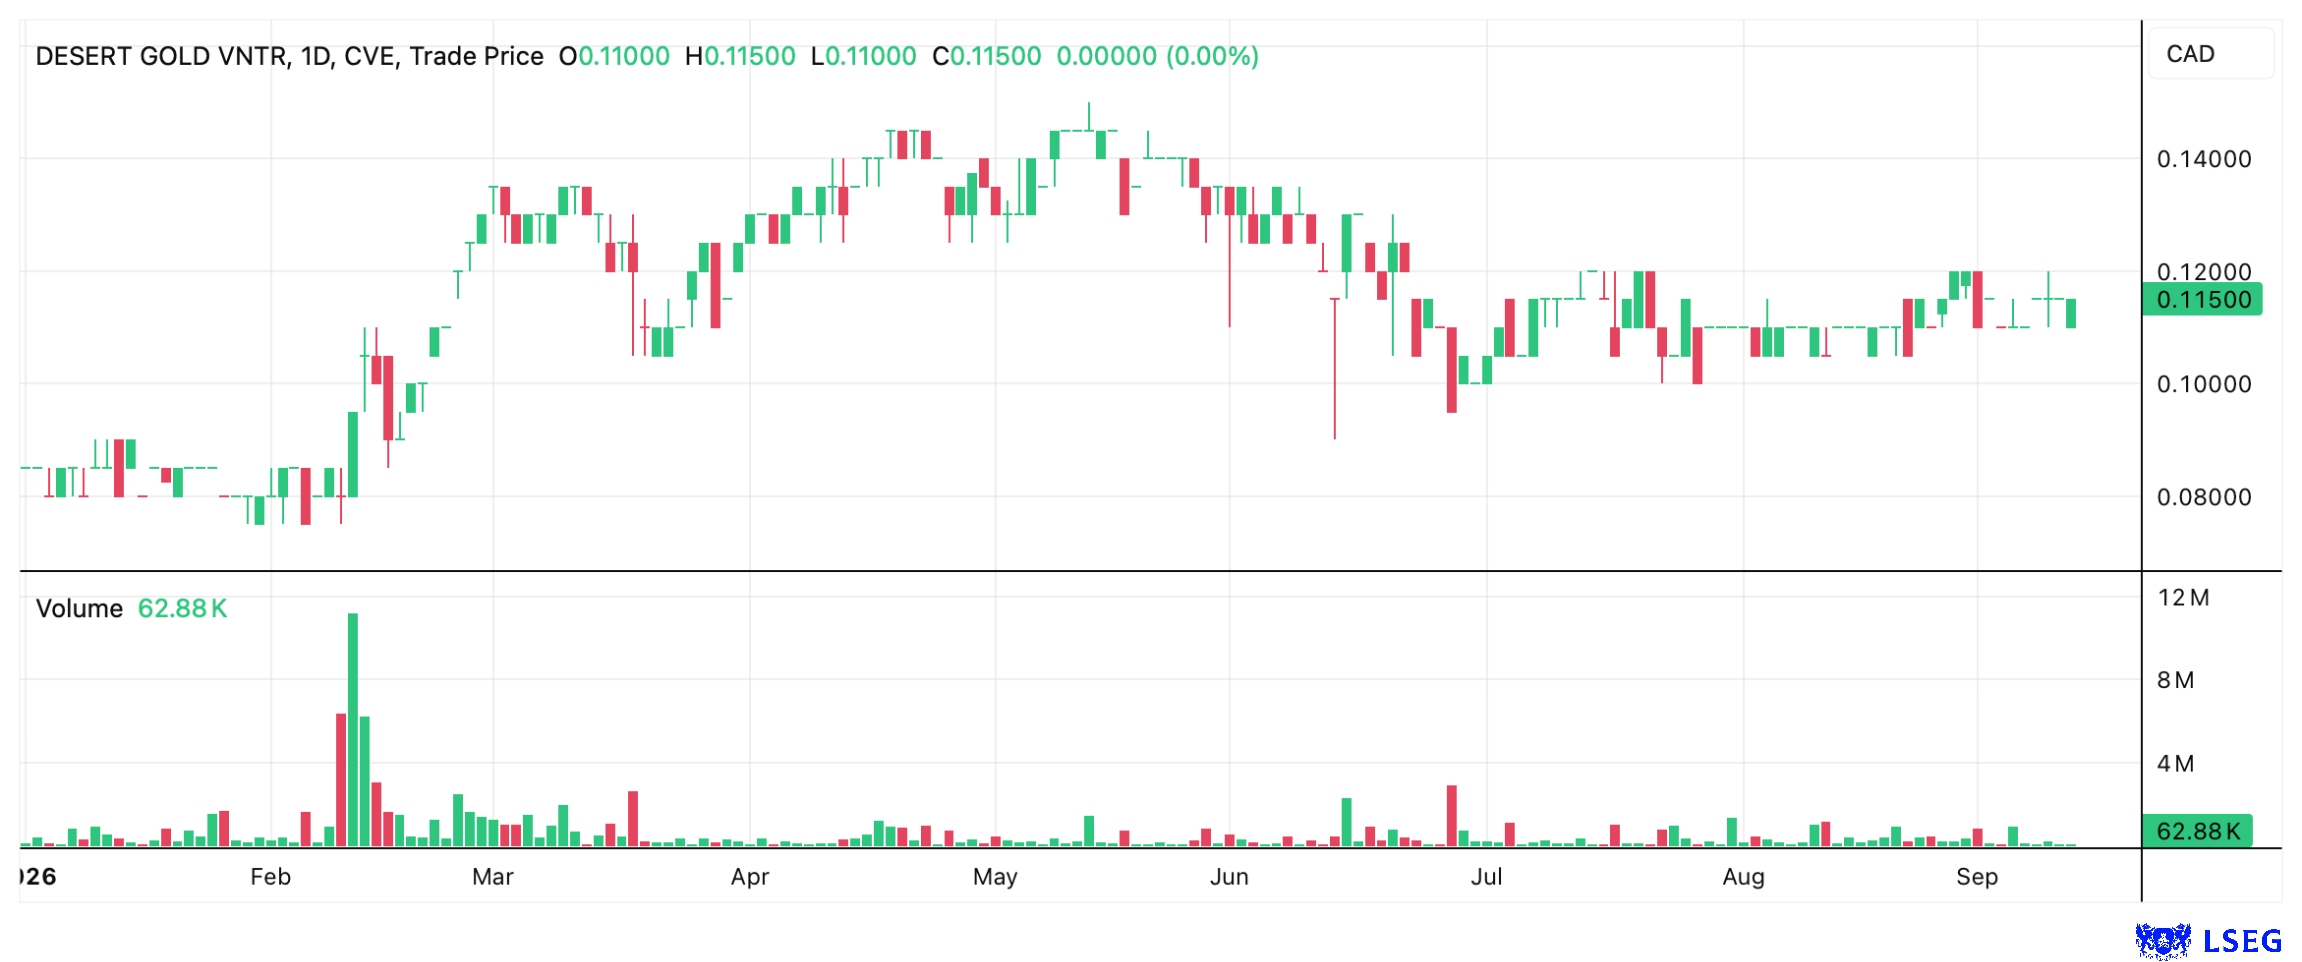
Once production begins, the sideways movement in Desert Gold’s stock should come to an end, and a new rally should begin. After all, GBC Research believes the stock could multiply in value to CAD 0.93. With estimated production costs of about USD 1,110 per ounce and a conservative gold price estimate of USD 2,850 per ounce, analysts expect annual revenue of around USD 33 million and EBITDA of over USD 20 million for 2027. Currently, Desert Gold is valued at approximately CAD 40 million at a share price of CAD 0.11.

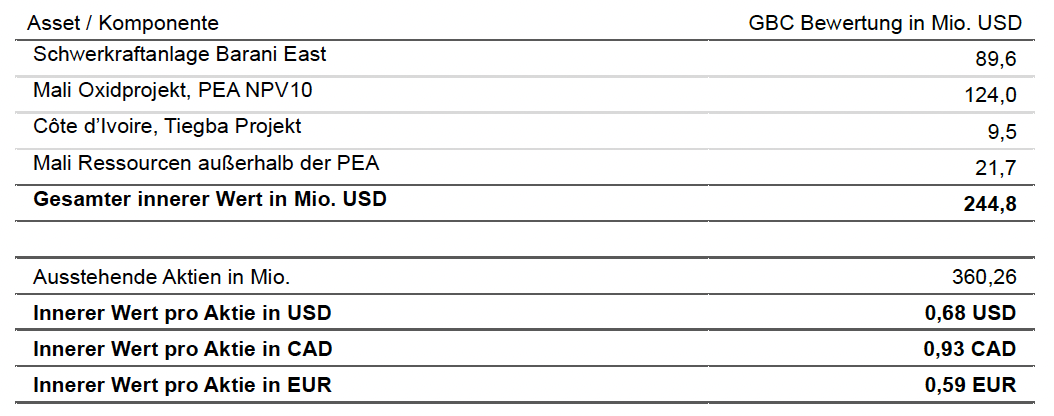
GBC Research’s sum-of-the-parts valuation also illustrates the upside potential of Desert Gold’s stock. According to this valuation, the company’s total intrinsic value stands at USD 244.8 million. Of this, USD 89.6 million is attributable to production at Barani East. The remaining Mali project is valued at USD 145.7 million. The still-young Tiegba Gold project in Côte d’Ivoire already contributes USD 9.5 million to the total valuation. With approximately 360.26 million shares outstanding, this results in an intrinsic value of USD 0.68, or CAD 0.93, or EUR 0.59 per share. Desert shares were trading at EUR 0.0745 on Tradegate yesterday.
There are good reasons to expect a rally in the Desert Gold share price in the coming weeks. Gold production is set to begin soon. If this milestone is achieved, it would not only provide solid self-financing for further expansion but also fuel takeover speculation. GBC’s valuation is conservative, and reaching its price target would mean a multi-bagger for the stock.

Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.