

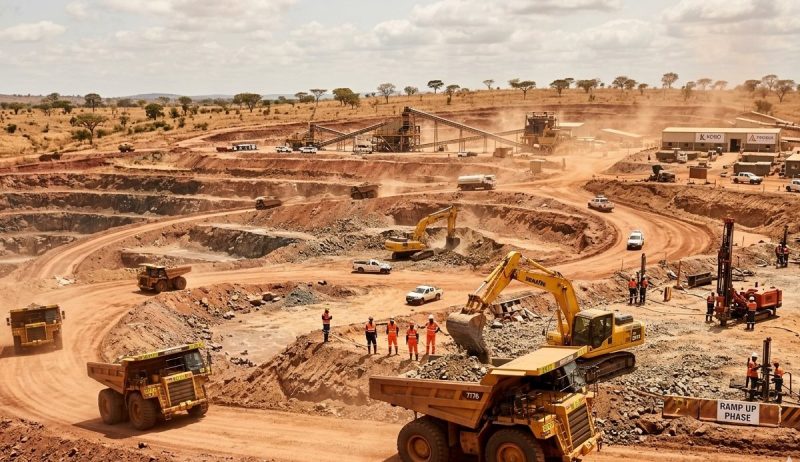
K92 Mining: The Gem in PNG
The recent correction in the gold price did not hit K92 Mining’s stock as hard as it did many of its competitors. The stock is currently trading just over 10% below its August high. This speaks to a strong shareholder structure at the gold producer. And, of course, there are reasons for this. The Canadian company is aggressively expanding its Kainantu mine in Papua New Guinea, making itself an attractive target for some of the industry’s biggest gold miners seeking growth.
In fact, several industry giants are now active in this Pacific nation. For example, Barrick Mining operates the Porgera gold mine in partnership with China’s Zijin Mining. South Africa’s Harmony Gold is also active in the country with the Hidden Valley mine. And last but not least, global market leader Newmont acquired the Lihir gold mine in PNG, as the country is commonly abbreviated, through its takeover of Newcrest. What do all these companies have in common? Despite the recent correction in the gold price, they are generating high profit margins—sometimes exceeding USD 2,500 per ounce. The money is flowing into share buybacks and dividends, yet they must also invest for the future. K92 would likely fit well into many a mining portfolio.
It is not just about production growth. Because of the deposit’s geology, K92 Mining can mine gold at Kainantu at a production cost of just USD 1,376 per ounce (AISC) despite global inflation, as the Q2 figures showed. Gold production itself totaled 42,931 ounces between April and June, representing a 32.4% increase over the previous year’s figure. Management expects that expansion in the second half of the year will enable the company to achieve the best production results in its history. The next phase of expansion in 2027 is then expected to enable annual production of 400,000 ounces of gold equivalent.
The stock is suitable for investors who favour growing gold miners and appreciate a dash of M&A potential in their investments. Even if a takeover does not materialize, the stock offers significant upside potential due to the expansion.
Kobo Resources: High Expectations
The weeks leading up to the first resource estimate are usually a period of uncertainty for mineral explorers. For investors, this phase is often like waiting for a gift. Typically, months of drilling have been carried out beforehand, data collected, and geologists’ reports evaluated. A lot of money has been invested in the rock, and now it is time to reap the first part of the harvest. It is the toughest part of speculation: enduring the uncertainty.
This is likely how shareholders, and even the management of Kobo Resources, are feeling right now. With Kobo Resources’ Kossou project, those involved are right in the middle of this phase. The management team, led by founder and CEO Édouard Gosselin, has postponed the project’s first resource estimate until the new year. And “for good reason”, as the Franco-Canadian recently told investors in Munich. Because Kobo keeps scoring—to use soccer terminology. First, the company reported 5 m at 4.55 g/t gold, 6 m at 2.30 g/t gold, and a 1 m interval at a whopping 68.6 g/t gold in the so-called Road Cut Zone. These are top-notch results, but the final whistle for the drilling program is far from sounding.
Gosselin, who holds about one-eighth of the shares, now plans to continue drilling to a depth of 200 m. The lab released the latest drilling data at the end of September. In the aforementioned zone, drill hole KDD0191 yielded 19 m grading 1.94 g/t gold starting at a depth of just 67 m. This included an additional 14.2 m grading 2.44 g/t and 9 m grading 3.29 g/t gold.
These strong drilling results provide a clear, retrospective rationale for the delay in the resource announcement. The goal is to incorporate as much data as possible. So while Kobo is releasing spectacular drilling data, the stock is still trading sideways, partly due to market conditions. Currently, the momentum has slowed somewhat for resource explorers given the gold price’s recent correction. On the other hand, this presents an opportunity for patient investors. The resource estimate is coming, as Gosselin assures us. And then this small-cap stock, which currently has a market capitalization of just EUR 16 million, could take off.
Investors need not worry about the location. The project is situated only about 20 km northwest of Yamoussoukro, the capital of Côte d’Ivoire. This, combined with its proximity to the Kossou Dam, ensures access to labour, decent road infrastructure and energy and water. Last but not least, many gold miners are active in this region. For example, Perseus Mining’s Yaouré gold mine is located just about 10 km away. The Australians are being touted as a potential acquirer of Kobo Resources. At least, speculation to that effect has been circulating in the industry for some time.
B2Gold: Stock Shows Resilience
The rally in B2Gold’s stock was abruptly interrupted by the correction in the gold price. Nevertheless, the stock is holding up surprisingly well and remains well above the USD 5 mark. By comparison, before the release of the Q2 results, the stock was trading for less than USD 4.
The previous rally was driven by the positive outlook for the gold miner, which has mines and projects in Canada and West Africa. Production is expected to continue growing in the coming years. B2Gold is currently ramping up operations at the Goose Mine in Canada. There, the mine is expected to produce an average of 300,000 ounces of gold per year in the first six years; in peak years, production could reach up to 330,000 ounces.
At the Fekola complex in Mali, meanwhile, between 390,000 and 420,000 ounces of gold are expected to be mined this year. However, the planned expansion is expected to enable production of 500,000 ounces of gold here in the long term. The first effects are likely to be seen as early as next year, when higher-grade ore is extracted from underground.
Analysts are optimistic about the stock, which is still suffering from the “Mali penalty”. They expect significant gains in net income. Their price targets are mostly between USD 6.15 and USD 6.50. Raymond James even considers USD 7.50 per share to be fair. Investors not deterred by Mali’s country risk could enter the stock as soon as the gold price changes direction again. Incidentally, takeover speculation comes free with B2Gold: Endeavour Mining, the largest Western gold producer in West Africa, is repeatedly mentioned as a potential acquirer.
With K92 Mining, investors are betting on a rapidly growing mining company in a booming gold mining sector. Those who are not put off by the country risk in Mali could also consider investing in B2Gold. With Kobo Resources, investors are banking on a compelling resource estimate following strong drill results. Takeovers are possible for all three stocks sooner or later.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.