

Plug Power: The Once-Shining Hydrogen Star Now Fighting for Survival
Hydrogen has long been regarded as the sure saviour of the global energy transition. For many, that is still the case today, but this is not about debating whether it is or is not. In any case, the markets currently look noticeably bleaker. The general weakness across the entire hydrogen sector is, almost without exception, mercilessly dragging investors’ former darlings down with it. High interest rates and sluggish commercial adoption are taking a heavy toll on the H2 pioneers. Investors are increasingly pulling back from highly speculative growth stocks and avoiding risky bets on the future.
Fundamentally, Plug Power continues to grapple with major challenges, such as its equipment division. This division devours vast amounts of capital every single day. Operating margins remain deep in the red and are weighing heavily on the balance sheet. Persistent cash outflows and dwindling investor confidence have now pushed the market capitalization below USD 3 billion. The broad product portfolio costs a fortune but has so far failed to deliver the urgently hoped-for profitability. Shareholders have been waiting in vain for a dividend from this massive cash-burner—and will likely continue to do so for some time to come.
The current technical chart situation reflects this fundamental disaster ruthlessly and with complete honesty. Recently, the share price on the US stock exchange slipped to around USD 2.05. In doing so, the stock broke through key support levels, including the 50-day SMA at USD 2.18. The 200-day SMA is already far away at USD 2.48. By definition, the stock is thus in an unbroken downtrend. The stock is now miles away from its previous record highs—such as those from 2021, when it traded above USD 70. Right now, there are no clear operational signals pointing to a speculative turnaround. The investment thesis here is simply to exercise the utmost caution. Doing nothing might be the better choice.
Investors who have already been burned by Plug Power — or would rather avoid getting burned in the first place — could look to companies with proven business models. One such opportunity is offered by a leading German software company at the forefront of AI and digitalization.
TeamViewer: On a Growth Trajectory with Smart Financing and AI
Global remote support is no longer just a flash in the pan from the COVID-19 era, but a vital backbone of today’s modern workplace. The Göppingen-based software group is proving that it can hold its own in this highly competitive market over the long term. Management is moving forward with bold technological ambition, and with its new AI agent, “Tia Troubleshooting”, the company is fundamentally revolutionizing automated IT troubleshooting. This “smart assistant” can independently analyse routine problems and resolve them immediately upon approval.
Behind the scenes, the group has also done extensive work on its long-term capital structure. To support the ambitious acquisition of the British specialist 1E, the company secured fresh capital. A newly issued promissory note loan of exactly EUR 125 million ensures stability in the books. Added to this is the drawdown of a EUR 40 million tranche from the European Investment Bank. Furthermore, the important revolving credit line of EUR 150 million was extended ahead of schedule through 2031.
These strategic moves have been received largely positively on the capital market. The stock is currently trading around EUR 6.60, up significantly from its low of EUR 4.09. The stock is already well above the closely watched 200-day SMA, which stands at EUR 5.69. As a solid IT investment, the stock now offers an exciting mix of financial stability and operational AI growth potential. Where else would you find that in this form with a German stock?
From a purely technical analysis perspective, once the stock breaks through the resistance level at EUR 7.20, it could gain further momentum toward EUR 8–9. It would not be entirely absurd for the stock to find its way back into double digits either. Interesting!
While some companies solve virtual IT problems, others are fighting very real threats to our environment. That brings us to Zefiro Methane.
Zefiro Methane: Tackling the Methane Time Bomb
In North America, millions of unplugged oil and gas wells are rotting away unnoticed. Climate-damaging methane flows unhindered from these abandoned wells into the atmosphere and could gradually “contaminate” the groundwater. CEO Catherine Flax cuts to the chase in a recent video. The danger is so immense that escaping gases can even cause residential buildings to explode. Investors who want to grasp the full scope of this underestimated crisis should watch this insightful interview:
This enormous need presents a massive business opportunity for specialized problem-solvers. Zefiro Methane has turned this real danger into a thriving business model. In September 2026 alone, the company announced several developments. First, it secured a major state-funded contract in the Great Lakes region worth USD 11.5 million. Shortly thereafter, three additional projects in Ohio and Pennsylvania followed, valued at approximately USD 1.9 million. As the sole bidder, the environmental company was able to secure prices that were, in some cases, a substantial 40% above the government average.
The hard work is paying off, as revenue over the past 12 months grew by exactly 21% to USD 41.2 million. The company also generated a positive operating cash flow of USD 4.3 million.

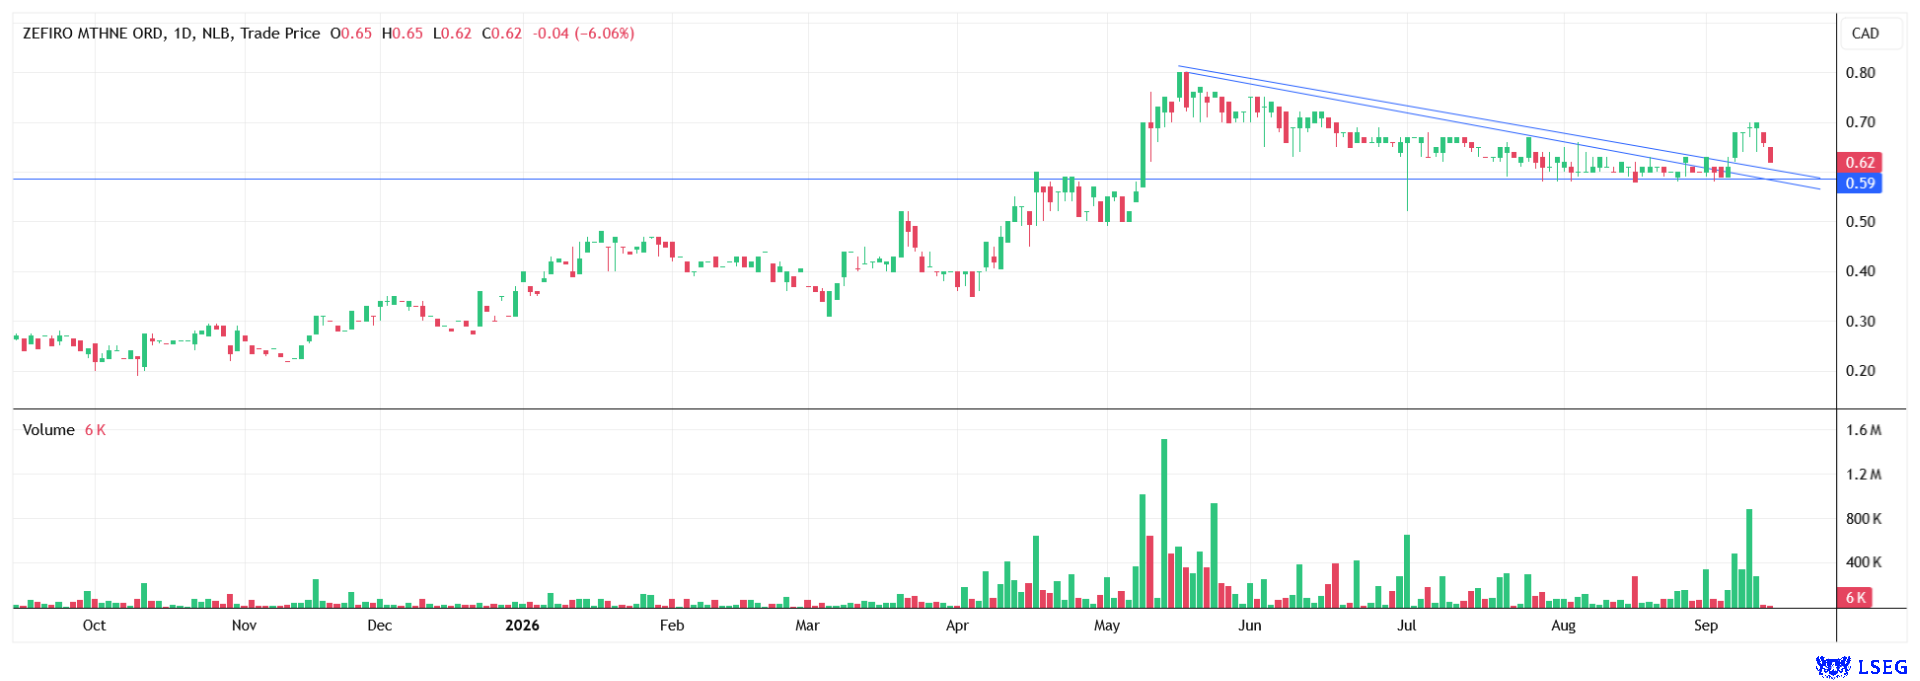
This fundamental strength is reflected in an extremely exciting chart pattern. Following a spectacular breakout in May above CAD 0.60 to a high of CAD 0.80, the stock initially consolidated at a high level. In early September, the stock then broke out upward from a wedge formation amid high trading volume. The high following this breakout was exactly CAD 0.70. Currently, the stock has consolidated somewhat again and is trading at a more attractive CAD 0.62. This most recent consolidation occurred on very low volume, which is extremely positive from a technical analysis perspective. Once strong volume returns, it could propel the stock upward quickly. Currently, the stock is at a fairly well-supported level. It is benefiting from both strong horizontal support and the previously downward-sloping consolidation or trend line, which now provides support from above. Should the stock break out above CAD 0.70 in the near future, it could rise directly toward CAD 0.80. There, the opportunity to set a new annual high awaits. If this resistance level is breached, a rapid rise toward CAD 1.00 would be entirely possible.

For Plug Power, the situation remains highly challenging to extremely difficult given its heavy cash burn and weak sector trends. TeamViewer, by contrast, stands out thanks to solid refinancing and promising AI innovations, which make it an attractive long-term investment. Zefiro Methane currently stands out as a highly compelling niche player. With lucrative government contracts, solid margins and a favourable chart setup, the environmental company has strong potential for further share-price gains.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.