

Barrick Mining & Agnico-Eagle: Still on the Right Track Even with a Lower Gold Price
The stock market is in turmoil! This gives level-headed investors time to rebalance their portfolios. Perhaps the adage “Buy on every dip” will be thrown overboard, even though it has worked for the past three years—at least on the NASDAQ. The sell-off in precious metals has fairly simple reasons: liquidity! Fund managers worldwide must offset losses from underperforming assets to secure their management mandates into next year. This intensifies the pressure on the historical performance of gold and silver over the past 24 months.
When it comes to the major mining companies, it is time to do the math! Thanks to its enormous size and global diversification, mining giant Barrick Mining is showing remarkable operational resilience amid falling precious metal prices. The company is consistently focusing on high-grade, large-scale projects such as Goldrush and Reko Diq, which deliver strong margins even during temporary market weakness. Admittedly, the company will face a noticeable increase in all-in sustaining costs (AISC) in 2026, ranging from approximately USD 1,760 to USD 1,950 per ounce. However, through its strategic focus on organic growth and profitable joint ventures such as Nevada Gold Mines, management is successfully avoiding expensive, low-return acquisitions. With revenue over USD 20 billion in the past twelve months, this industry heavyweight’s profitability remains structurally intact. For income-seeking investors, this fundamental strength is further underpinned by a reliable dividend yield of about 1.7%. Analysts on the LSEG platform expect an average upside potential of 35%.
The outlook for Agnico-Eagle Mines is no less promising. The company is regarded on the stock market as a model of efficiency and stands out for its exceptionally low-risk profile. Its focus on politically stable regions, particularly the Abitibi Belt in Canada, shields the group from the geopolitical risks that plague many competitors. Even with lower gold prices, Agnico-Eagle achieves an impressive net profit margin of more than 40% thanks to its excellent cost structures. Unlike Barrick, Agnico has very low debt, making its balance sheet exceptionally resilient in rough market conditions. Recent quarterly figures underscore this strength with a robust 35% year-over-year increase in revenue. Investors looking for a long-term, crisis-tested stock in the gold sector will find a resilient, high-quality leader in Agnico-Eagle. The price correction from USD 250 to USD 180 creates attractive entry opportunities, as the 2027 P/E ratio has also fallen from 25 to 17.
Fresnillo plc: The Silver Market Could Still Offer Golden Entry Points
Fresnillo plc, a standard silver stock, has been hit hard. In January, the British producer, which focuses on Mexico, reached all-time highs of over EUR 52. In yesterday’s trading, however, the stock lost another 3% and closed at EUR 31.60, hitting the 40% retracement level from the high. From a purely technical perspective, this marks the completion of the first Fibonacci retracement, but a few negative developments remain. A significant downward revision of the annual forecast for silver and gold production is particularly telling. The company’s aging mines are suffering from declining ore grades. To counter this trend, management must shift to narrower veins and adjust operational planning, which will curb short-term efficiency. At the same time, persistent inflation in Mexico is sharply driving up operating costs for energy, equipment, and wages. Although the at-times very high commodity prices in the first half of the year masked these structural weaknesses in the financial statements, the recent decline in silver and gold prices has ruthlessly exposed these vulnerabilities. In addition, regulatory hurdles and protracted approval processes for new projects are delaying the exploration timeline. Despite ample cash reserves and high dividends, many investors are shunning the stock; however, attentive investors may see further price declines as an entry point. At least the sharp decline in the share price has brought the estimated 2027 P/E ratio down to 12.2. Keep the stock on your watchlist, as the downward trend could still gain momentum.
Lahontan Gold: From Developer to Producer in Rapid Mode
In addition to the industry’s major players, it is always worth keeping an eye on suitable “followers”. In Nevada, we come across the explorer and developer Lahontan Gold. Observers took real notice during the latest massive resource update for the flagship Santa Fe project. The new data underscores the geological potential: open-pit resources climbed to approximately 1.2 million ounces of gold equivalent in both the “Indicated” and “Inferred” categories, a substantial 22% increase over previous estimates. In particular, the near-surface oxide zones Slab and York stood out with a veritable volume boom of over 37%.
For visionary founder and CEO Kimberly Ann, these strong figures provide the perfect springboard for the upcoming preliminary economic assessment (PEA).
*In an interview with IIF host Lyndsay Malchuk, the company’s CEO made the company’s uncompromising focus clear, putting it bluntly: “This is a business—cash flow is what matters most!*”
To ensure the planned mine restart is completed on schedule, mining experts are already working full steam ahead on the optimal design for cost-effective heap leaching. The company’s rapid upward trajectory is further underscored by the latest results from the ongoing drilling program in the Calvada East sector. One drill hole in particular, along the prominent Summit Fault, caused a real sensation, intersecting 13.7 m of fine 1.10 g/t gold equivalent in volcanic rock. Because this new gold zone remains open in multiple directions, the system extends beyond the model pit boundaries and adds substance to the resource. Thanks to the already developed brownfield site with existing infrastructure, the new ounces can also be converted into actual production more quickly. Given a moderate market capitalization of just under CAD 165 million, the stock offers bold commodity investors a first-class, countercyclical entry opportunity with additional leverage relative to the precious metals market.

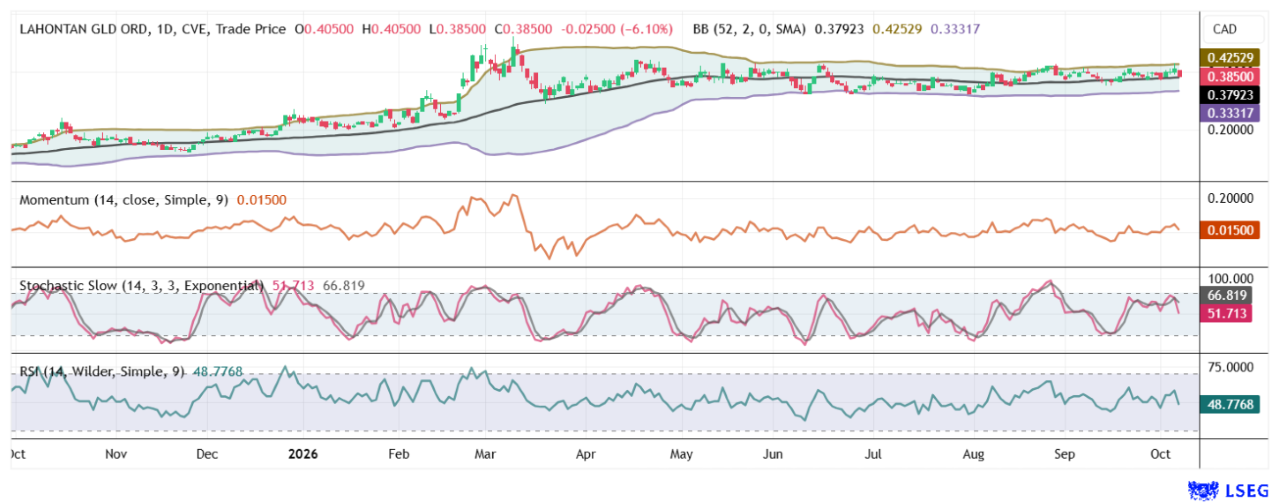
The current consolidation wave in the precious-metals sector is unlikely to end until liquidity pressures in other asset classes have eased. It is harder to say when the tech sector will complete its own consolidation, as long investors are only now beginning to lose their footing. If the stock-market downturn extends further, gold could once again emerge as a safe haven. So stay ready for what comes next.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.