

NextEra Energy: Strong Balance Sheets Secure Investments
Corporations are leveraging their strong balance sheets to invest despite challenging conditions in the United States. US utility NextEra Energy expanded its order backlog of contractually secured wind, solar, and storage projects by 3.6 GW to approximately 35.1 GW in the second quarter of 2026. The driving force behind this growth is the rapidly increasing electricity demand from data centres for artificial intelligence. According to the company, hyperscalers accounted for around 30% of new project commitments as early as the first quarter. These technology customers rely on enormous amounts of electricity with extremely short lead times. NextEra Energy passes on the increased financing and material costs to these financially strong customers through long-term power purchase agreements. With total assets of USD 232.8 billion and direct access to the bond market, the company can pre-finance equipment over the long term. In the first half of 2026 alone, NextEra raised approximately USD 15.6 billion in long-term debt to fund investments totaling about USD 19.4 billion. Smaller market participants do not have this financial flexibility.
First Solar: Domestic Manufacturing as a Shield Against Tariffs
Domestic PV module manufacturers, by contrast, are benefiting from trade barriers. First Solar leverages the associated advantages through its proprietary thin-film technology. The company relies on cadmium telluride, a semiconductor material that can be applied in an ultra-thin layer to glass substrates and replaces crystalline silicon cells. As a result, the manufacturer completely bypasses the polysilicon supply chains from Asia that are at risk of sanctions. According to industry analyses, this technology accounts for a large portion of US cell production. First Solar reports a contractually committed order backlog of 45.1 GW with deliveries through 2030. According to pv magazine USA, modules with US-manufactured cells cost around USD 0.46 per watt in the first quarter of 2026—significantly more than imported products. In the second quarter of 2026, First Solar generated revenue of USD 1.06 billion, a gross margin of 57%, and earnings per share of USD 3.92. The margin was boosted, among other things, by a tariff refund and tax credits under Section 45X.
RE Royalties: Royalties as the Method of Choice for Project Developers
In light of growing investment barriers for regional solar projects, the project financier RE Royalties is attracting renewed attention. The company adapted the mining industry’s royalty model and applies it to renewable energy. RE Royalties provides developers with capital and, in return, secures a percentage share of future gross electricity revenues. This structure protects developers from dilution of their equity stakes and ties payments directly to the plants’ electricity output. Rising operating and maintenance costs therefore do not directly affect RE Royalties. However, fluctuations in electricity production and default risks among lending partners remain. The strategic dimension of this approach is illustrated by the partnership with the US developer Solaris Energy. In three tranches beginning in January 2026, RE Royalties provided the company, which specializes in decentralized solar power plants, with a total of USD 4.8 million for 16 projects totaling 15.24 MWdc. On August 5, 2026, RE Royalties also announced a non-binding letter of intent with Solaris Energy for up to an additional USD 62.7 million for 96 more projects.

Including funds already secured, the potential volume totals USD 67.5 million. Future investments are subject to due diligence, approvals, and final agreements. The royalty rate will be adjusted to ensure that an agreed-upon minimum return is achieved over 25 years. After that, payments will continue for the remainder of the assets’ operational life. According to Solaris, the capital will accelerate construction progress and support the ongoing debt and tax-equity financing of the company’s first proprietary portfolio.
Key Return Metrics and Strategic Review
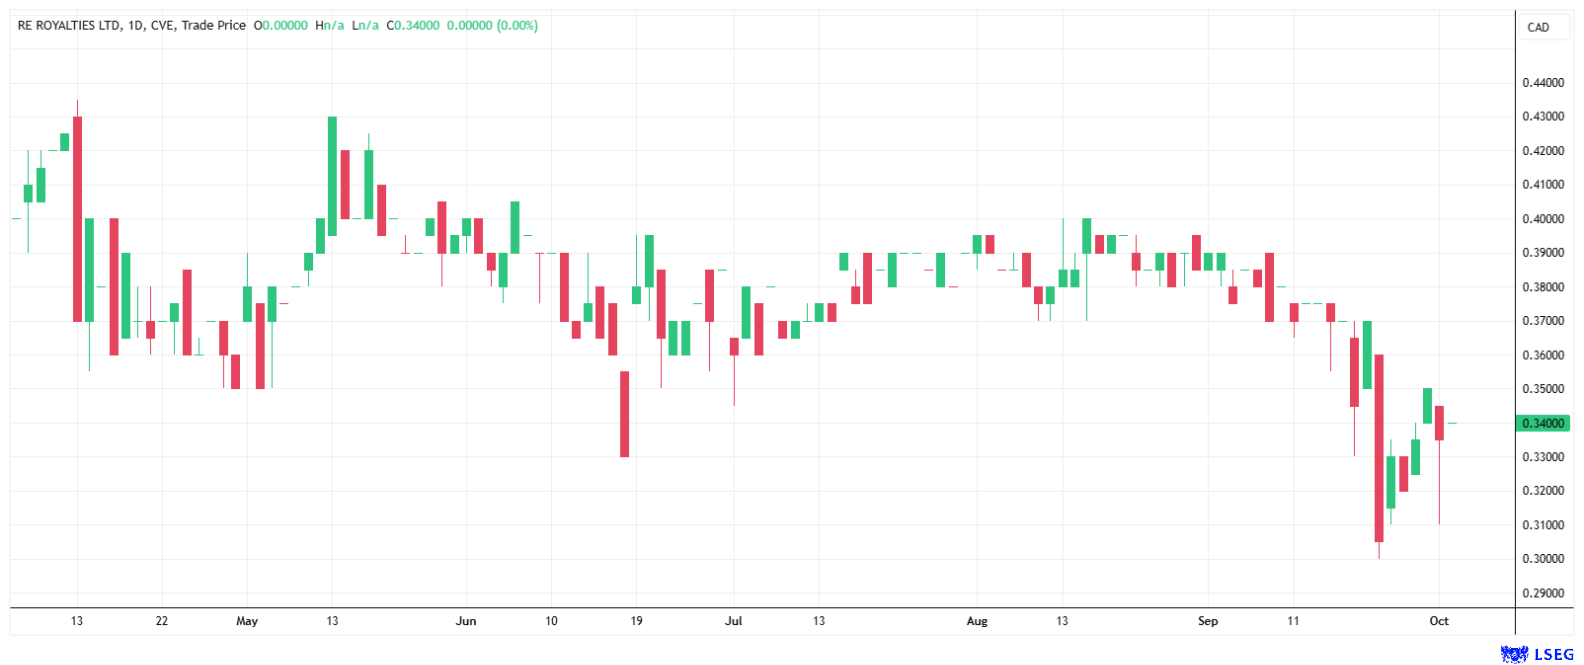
RE Royalties’ portfolio comprises over 100 royalties on approximately 135 solar, wind, hydroelectric, and energy storage projects in North America, South America and Asia. According to the company, it has invested over CAD 83 million in 27 completed transactions. Since its inception, the portfolio has generated an unlevered internal rate of return (IRR) of approximately 19% with a 1.5x return on capital, according to the company. Refinancing is provided through green bonds with coupons ranging from 6% to 9%. Shareholders receive an annual dividend of CAD 0.04, which, at the current share price of approximately CAD 0.34, corresponds to a dividend yield of more than 11%. This contrasts with a low market capitalization of approximately CAD 15 million. In March 2026, the Board of Directors initiated a formal strategic review with PwC Corporate Finance. It is evaluating all options, including a complete sale of the company. Whether this will result in a transaction remains to be seen. The company emphasizes that there is no guarantee of this.
For investors, opportunities lie primarily in further growth through partnerships such as the one with Solaris and in the outcome of the strategic review. A buyer would secure a diversified portfolio of revenue-based claims. Risks include credit defaults: In 2024, provisions and write-offs of loans significantly weighed on earnings. Nevertheless, thanks to the new conditions in the US market, RE Royalties is perfectly positioned for the current environment.

Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.