

Sandvik Fights to Secure European Raw Material Resources—and Bets on Almonty
For specialized industrial groups like Sandvik, dependence on Chinese supply chains is a problem. The Swedish tool specialist operates, through its Austrian subsidiary Wolfram Bergbau und Hütten, the only integrated tungsten smelter outside of Asia and Russia, but it relies on a steady supply of tungsten. China’s APT exports fell from 782 metric tons in 2024 to 243 metric tons in the first eleven months of 2025; since early 2026, they have virtually come to a standstill. The APT price in Rotterdam recently rose to around USD 3,000 per metric ton unit (MTU). This is forcing the Swedish company to seek new partnerships. On September 17, Almonty announced that the Sandvik subsidiary WBH will in the future purchase concentrate from the reprocessing of tailings from Almonty’s Los Santos project in Spain.
Legislative Developments Put Pressure on Lockheed Martin
Across the Atlantic, the raw materials crisis is affecting the defence industry. The US defence contractor Lockheed Martin requires tungsten heavy-metal alloys for missiles such as the Patriot PAC-3 MSE, Precision Strike Missiles, and anti-tank weapons, as well as for ballast weights in the F-35 stealth fighter. At the same time, milling the massive titanium structural frames consumes thousands of extremely hard cutting tools. A halt in tungsten deliveries is likely to quickly threaten production at Lockheed Martin as well. The situation is exacerbated by US legislation that extends beyond the country’s borders. Effective January 1, 2027, the Pentagon will prohibit the purchase of defence equipment containing tungsten sourced from China, Russia, North Korea, or Iran. Supply chains must be fully documented going forward.
Almonty Develops One of the Largest Deposits in the Free World
The mining company Almonty is benefiting from the new tungsten landscape. The long-standing tungsten specialist controls the largest mining sites outside China’s sphere of influence. Its flagship is the Sangdong Mine in South Korea, where flotation began in mid-2026 following extensive preparatory work. The first phase of expansion at Sangdong aims for an annual throughput of 640,000 metric tons of ore and will produce approximately 230,000 MTU of tungsten trioxide concentrate. Upon completion of the second phase, the company plans to double its capacity and thereby supply approximately 40% of total tungsten demand outside of China. Offtake for Phase 1 has long been secured: A 21-year contract commits 90% of the concentrates from the initial phase to the processor Global Tungsten & Powders, a subsidiary of the Austrian Plansee Group. In addition, at least 40 metric tons of oxide per month are to be supplied directly to Tungsten Parts Wyoming for ballistic defence equipment.

Almonty: Strong Business in Africa and Europe as Well
In addition to its main project in Asia, Almonty is developing other existing properties. One example is the Los Santos project in Spain, which the company plans to reactivate in order to supply tungsten directly to the European processor Sandvik in the future. Using a proprietary wet-mechanical process, scheelite is to be recovered from the tailings of previous mining operations. The Sandvik subsidiary Wolfram Bergbau und Hütten secured at least approximately 1,720 metric tons of tungsten trioxide from these tailings through a take-or-pay contract. In exchange for the purchase rights, it agreed in advance to a conditional one-time payment of USD 3 million. The deliveries themselves will be billed at index-linked prices with a floor, while the Swedish company receives the urgently needed tungsten. European production is complemented by the long-established Portuguese underground mine Panasqueira, which has been reliably supplying high-purity concentrates for decades. In the US, Almonty also holds the Gentung Browns Lake project in Montana to establish a mining presence in the United States in the future. A joint venture with the government of Rwanda, concluded last week, secures Almonty additional material from small-scale mining operations in East Africa. In the medium term, Almonty also plans to build a processing plant in Rwanda.
Almonty: Jefferies Sees Significant Upside Potential
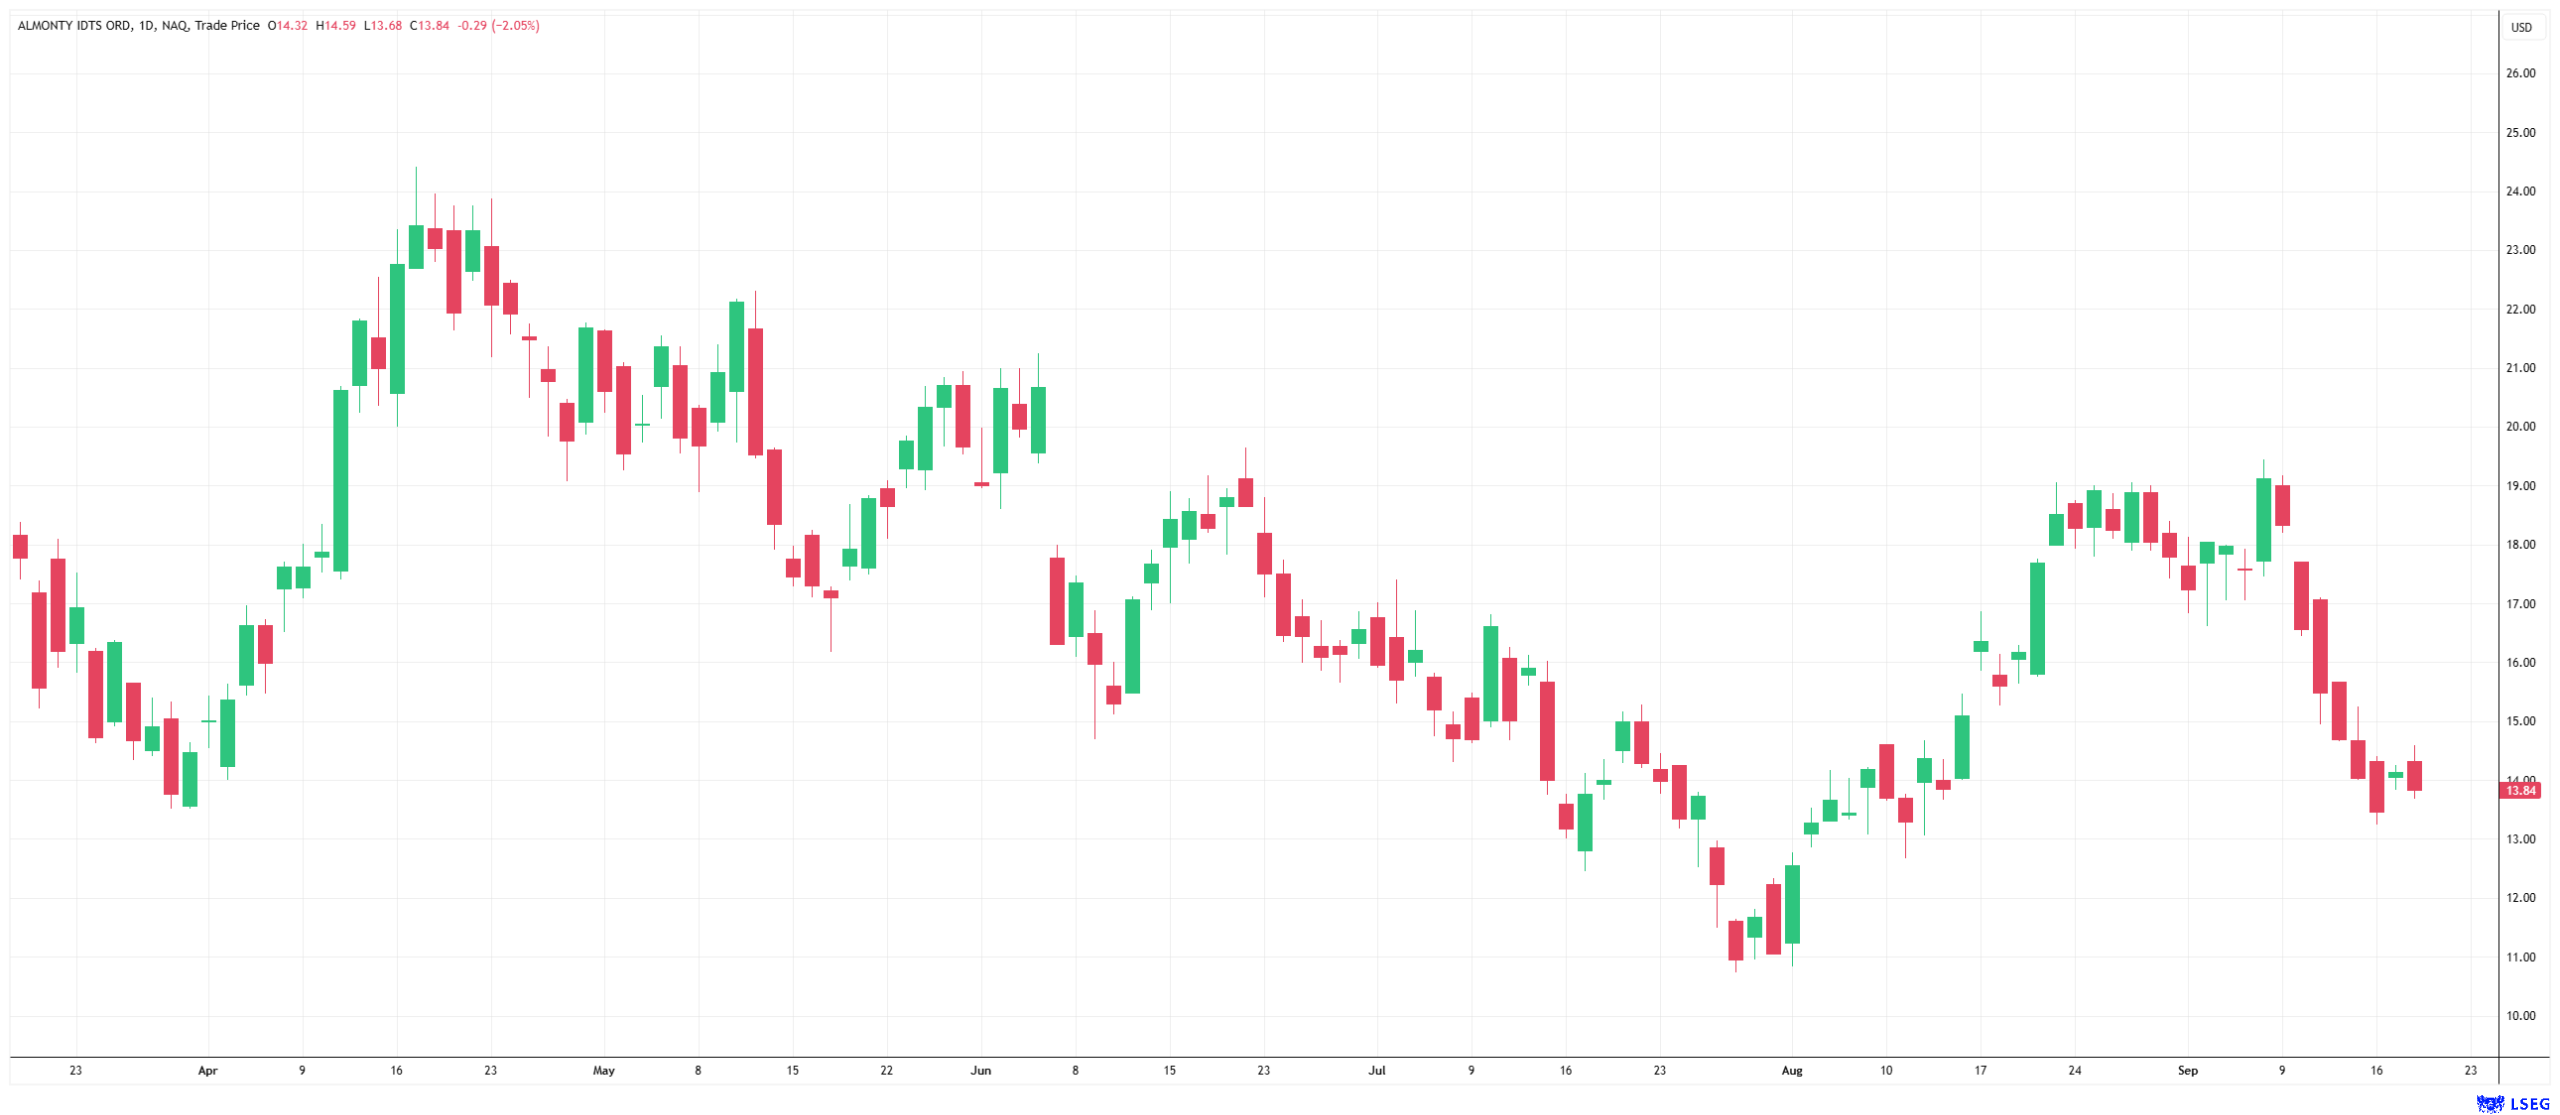
On September 2, the US investment bank Jefferies initiated coverage of Almonty with a “Buy” rating and a price target of USD 26.25. At the then-current price of USD 17.80, this implied 47% upside; at the current price of around USD 14, the implied upside is just over 85%. Jefferies bases its valuation on a solid cash flow model grounded in a long-term tungsten sales price of USD 1,300 per MTU, supported by a 21-year offtake agreement with minimum price guarantees. In addition to the upcoming ramp-up of the Sangdong mine in South Korea, analysts view the timeline for Phase II and sustained price premiums for Western tungsten as particularly crucial to the company’s future potential. Nevertheless, Jefferies also highlights risks in its Risk Radar: delays in reaching full production capacity in Phase 1, a possible postponement of Phase 2 beyond 2027, ongoing volatility in the commodities market, and debt-servicing and interest costs are the main hurdles. However, if management navigates this transition to full-scale industrial production smoothly, Almonty will secure a pivotal role in the Western supply chain, including all the opportunities that come with it.

Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.