

Technical analysis: momentum towards a chart breakout
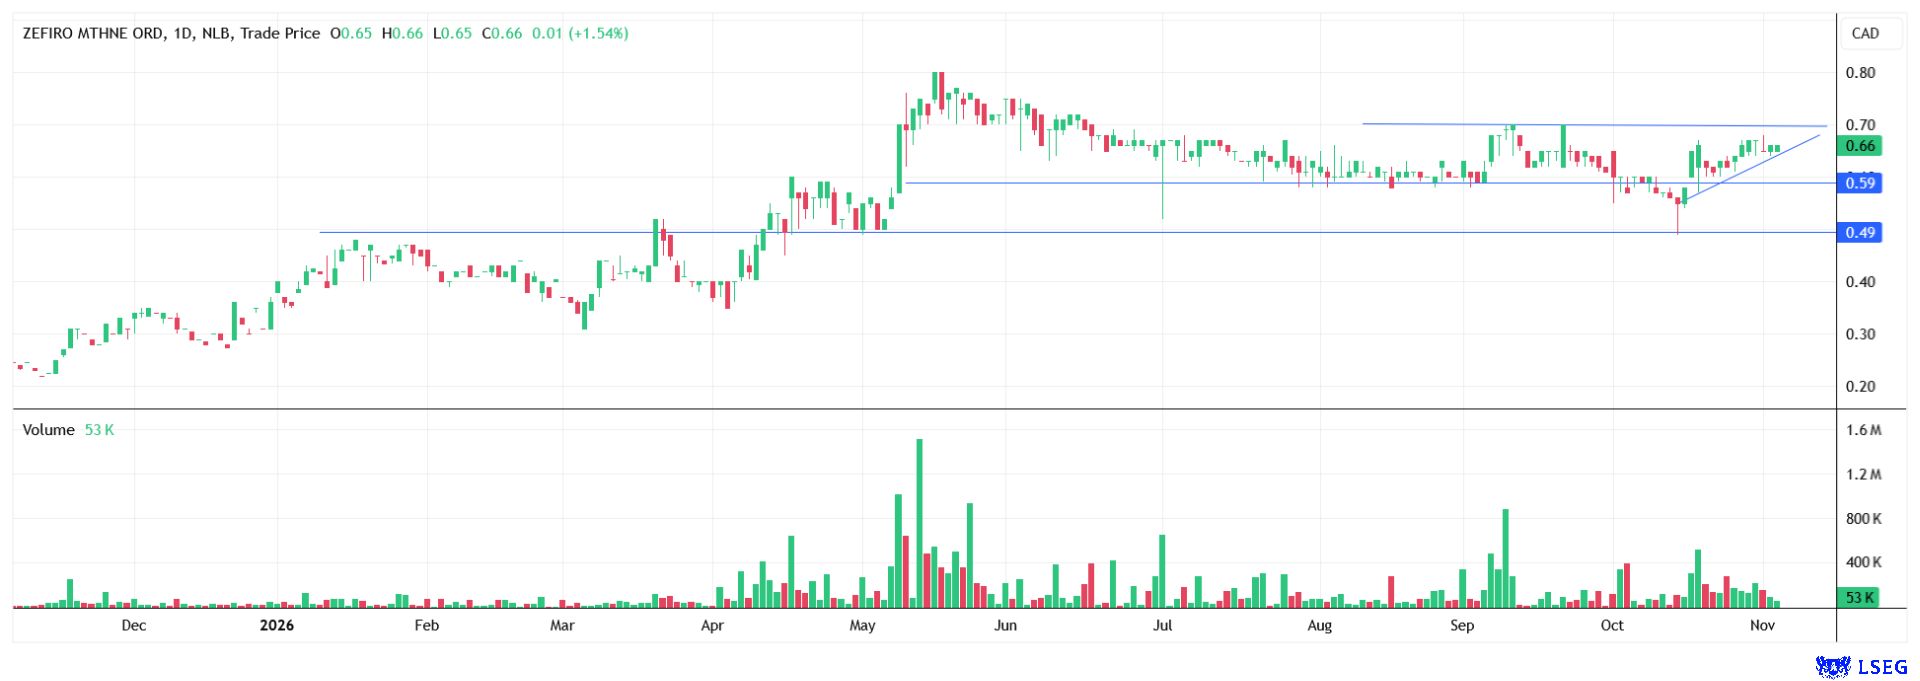
The stock market world is constantly looking for companies that combine operational growth with a globally relevant mission. This is precisely where Zefiro Methane comes in, a North American environmental services provider specialising in the meticulous plugging of abandoned and leaking oil and gas wells. The share staged a spectacular rise from CAD 0.20 in October 2025 to a peak of CAD 0.80 in May 2026, and has since undergone a solid correction. The stock is currently trading at CAD 0.66 and is awaiting fresh momentum. Prices between CAD 0.70 and CAD 0.71 would complete the decisive breakout, potentially paving the way straight back to the previous high of CAD 0.80. Above that, the technical picture even opens the floodgates towards the magic CAD 1.00 mark, while stable horizontal support serves as a reliable safety belt on the downside.

Operational strength: A powerful model meets fresh capital
Behind this share price momentum is an extremely robust, diversified business model that can grow beyond government funding alone. The company’s roots run deep, with more than 50 years of operating history in the Appalachian Basin through its subsidiary Plants & Goodwin. With a fleet of 25 drilling rigs, 14 wireline units and 6 cementing spreads, as well as 147 dedicated crew members, Zefiro now operates in 15 US states as one of the largest operators. With the recently announced private placement generating gross proceeds of approximately CAD 5.0 million and the successful integration of the Viking equipment, management has impressively demonstrated its financial firepower. The placement involved the issue of 7,575,758 units at CAD 0.66 each, accompanied by warrants at CAD 0.80. Notably, the placement occurred above the prevailing share price at the time.
Moreover, the acquisition of the Viking equipment, which generated revenue of around USD 1.54 million in August and September 2026 alone, underscores successful scaling toward the annual target of USD 10.0 million. As a result, Zefiro has already secured seven new Master Service Agreements (MSAs), five of which are generating initial revenue.
Realignment with improved earnings
The operational foundation is also reflected in the financial figures for the fiscal year ended June 30, 2026. Zefiro reported record revenue of USD 42.5 million, up 31.1% from the previous year. At the same time, gross margin widened from 23.0% to 29.2%, while adjusted EBITDA improved significantly to USD 3.8 million and the net loss narrowed to USD 3.5 million. The company benefits from massive structural demand driven by the US infrastructure fund, or rather the Infrastructure Investment and Jobs Act (IIJA), with a total allocation of USD 4.7 billion for abandoned wells, as well as by private industrial, energy and data centre developers. Substantial funding is flowing into states such as Pennsylvania, Ohio and West Virginia alone, where Zefiro often acts as the preferred or sole bidder thanks to its technological base and reliability.

Carbon markets as a growth accelerator: upside potential in a niche trend worth millions or even billions
Additional upside potential lies dormant beyond the traditional services business in the area of carbon credits and voluntary carbon markets. By supporting Isometric’s new protocol, Zefiro is positioning itself to generate valuable emission credits again in the future and benefit from a rapidly expanding global market.
Analysts point out that global capital commitments for carbon credits by corporate buyers reached a record USD 14.2 billion in 2025 (USD 22.0 billion in total) and could grow to as much as USD 270.0 billion by 2050 (the upper end of MSCI’s forecast for the market value of traded credits).
Investors gain access here to a business model driven by increasing regulatory pressure, the urgent need for clean sites and government budgets. Zefiro Methane combines proven field operations with a forward-looking ESG story.
The investment story receives additional tailwinds from analysts’ views: GBC AG recently confirmed its Buy recommendation and set the price target at USD 1.42 following the successfully completed capital increase with gross proceeds of CAD 5.0 million (net proceeds of around CAD 4.7 million or USD 3.35 million).
Particularly striking is the government project pipeline, quantified for the first time, with a substantial order backlog of around USD 40.0 million, contractually extending through June 2029 and guaranteeing excellent planning certainty over several years.
In addition to the major contract in Ohio, new exploratory preparatory contracts could open up additional, lucrative revenue streams, which should impressively reinforce Zefiro’s market position as an “indispensable environmental services provider”.
Conclusion
Zefiro Methane stands out for its solid operational foundation, strong revenue growth and exciting future opportunities in methane abatement. Following a healthy correction, the stock offers an attractive entry opportunity for investors seeking growth, with a potential technical breakout on the horizon.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.