
Heidelberger Druck: A Restructuring Filled with Obstacles
The printing press manufacturer is in the midst of a transformation. So it is not necessarily surprising that the first quarter of fiscal year 2026/27 turned out to be sobering. Revenue fell to EUR 404 million, down from EUR 466 million in the previous year. Adjusted EBITDA plummeted to just EUR 1 million, resulting in a net loss of EUR 32 million. The Italian business, in particular, caused problems after a government subsidy program expired. Order intake declined by 4% to EUR 537 million.
Despite all this, management is sticking to its full-year forecast. Revenue is expected to remain stable, and the adjusted EBITDA margin is expected to improve significantly. To reduce its dependence on the cyclical printing business, Heidelberg is focusing on new areas. The acquisition of manroland sheetfed and POLAR has been completed. In addition, a planned joint venture with PHENOGY for the production of sodium-ion battery cells is underway, and a partnership with Skyeton in the defence sector is in the works. There is also a new appointment: Chief Financial Officer Christoph Burkhard will take office on October 1.
Heidelberger Druck’s valuation appears historically attractive. The stock is trading around EUR 1.35; its 52-week high, set in October 2025, was EUR 2.40. Analysts such as Warburg Research confirm their “Buy” recommendation with a price target of EUR 1.80. mwb research lowered its target to EUR 2.35 but remains positive. Insider purchases by executives also signal confidence. An investment, however, remains a bet on the second half of the year.
From a technical analysis perspective, the stock would need to break through the EUR 1.60 resistance level; once it does, it could break out and target the EUR 1.80–2.00 range. On the downside, the stock is well supported in the EUR 1.30–1.40 range. It should not fall below this level, or it risks slipping toward EUR 1.00.
Adidas: Strong Operational Performance, but the Market Has Its Doubts
The sporting goods manufacturer is actually posting solid figures. In the second quarter of 2026, revenue rose 14% on a currency-adjusted basis to EUR 6.7 billion, but operating profit reached “only” EUR 574 million, falling short of expectations.
Nevertheless, the company raised its full-year revenue forecast. The company is aiming for revenue growth of 9 to 10%, with an EBIT target of around EUR 2.3 billion. Despite this, the stock is currently trading at EUR 142—once again well below its July level, when it was nearly EUR 190.
Adidas is being weighed down by rising freight and procurement costs, as well as higher marketing expenses. Added to this is the impending loss of the DFB equipment contract at the end of the year. Nevertheless, executives are buying heavily. CEO Bjorn Gulden purchased 3,600 shares for approximately EUR 504,000, and Executive Board member Birgit Kretschmer acquired 720 shares for about EUR 101,000. Such insider purchases are seen as a strong signal of commitment to the company and a statement that the share price is too low.
The valuation appears attractive. The expected P/E ratio for 2027 stands at 12.3, while Puma is valued at over 40 and Nike at just under 16. Although DZ Bank lowered its price target from EUR 215 to 205, it maintained its “Buy” rating. The Q3 results are due on October 29 and could provide more insight into the company’s financial performance. This could be an interesting opportunity for investors if sentiment shifts and the company’s operational strength overshadows margin-pressure concerns.
Desert Gold: On the Verge of a Breakthrough
The Canadian mining company is on the verge of a pivotal moment. On September 16, 2026, Desert Gold reported on construction progress at the Barani Mine in western Mali. The gravity separation plant and a 650-kVA generator have arrived on site. This is extremely important, as they were long-awaited. Construction work is moving forward, with commissioning scheduled for late October and the first gold production even targeted for the fourth quarter of 2026.
The company has recently struggled with significant delays. Freight difficulties, regional fuel shortages, and the rainy season have slowed the schedule. However, CEO Jared Scharf emphasizes: “The delivery of the plant and the generator is a crucial project milestone.” Things are looking good now. Drilling confirmed the presence of water on site; three boreholes yielded positive flow rates of 24, 9, and 8 cubic meters per hour. Equally important: no safety-related incidents were reported.
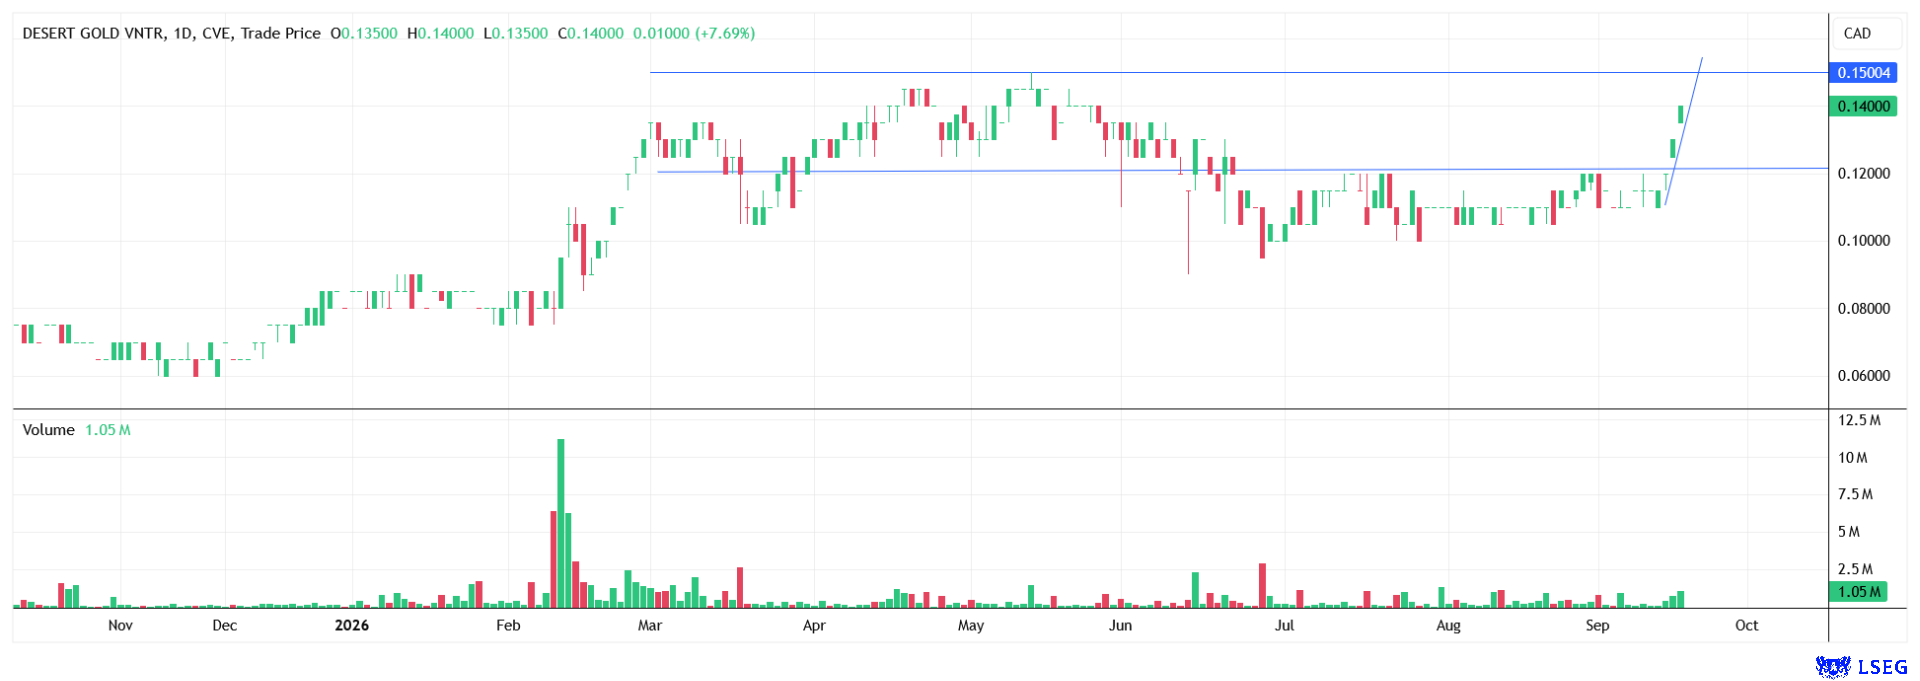
The potential is enormous. The stock is trading at around CAD 0.14. From a technical analysis perspective, there is room above CAD 0.15 all the way up to CAD 0.30. Analysts at GBC see a price target of EUR 0.59 or CAD 0.95. This represents a potential gain of several hundred per cent. The start of production could drive the stock higher. A break above CAD 0.15 would clear the path toward CAD 0.30. Of course, a further rise into higher price ranges remains possible as well.
Desert Gold has a solid resource base. Mineral resources at the SMSZ project total 336,800 ounces in the “M&I” category and 879,000 ounces in the “inferred” category. The PEA shows an NPV of USD 126 million and an IRR of 101% at a gold price of USD 4,070. Given these figures and values, and backed by the latest news, the chance of a re-rating is real.
Heidelberger Druck is undergoing a restructuring but offers a speculative opportunity with its attractive valuation. Adidas is performing well operationally but is struggling with margin pressure and market skepticism. The stock remains a long-term investment with potential and trades at a lower P/E ratio than its competitors. Desert Gold is on the verge of its first gold production, which could significantly boost its share price.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.