
thyssenkrupp: Up 100% in Just a Few Months
Steel is shining again! Few investors likely expected thyssenkrupp’s stock to perform this well since April. Since the end of March, the price has risen from EUR 7.12 to nearly EUR 16. In light of that, the current correction to EUR 13 seems manageable.
There are good reasons for this price performance. In particular, expectations for the steel division’s future profitability have improved significantly. At the end of September, thyssenkrupp Steel Europe presented ambitious medium-term targets. Adjusted EBITDA is expected to rise from around EUR 400 million to at least EUR 1.2 billion. A comprehensive restructuring program is intended to contribute to this, which, among other things, calls for the elimination or outsourcing of approximately 11,000 jobs. Brussels is also providing tailwinds. New EU trade defence measures aim to better protect European steelmakers from low-cost imports and reduce price pressure.
This positive trend is also supported by the latest financial results. In the third fiscal quarter of 2025/26, revenue rose by 8% to EUR 8.8 billion. Adjusted EBIT improved from EUR 155 million to EUR 183 million. In August, the Group also raised the lower limit of its full-year earnings forecast from EUR 500 million to EUR 600 million.
thyssenkrupp is also making progress on the future-oriented topic of green steel. For the multi-billion-euro restructuring of steel production in Duisburg, the company reached an agreement with the European Commission on revised funding terms. This is intended to secure government support of approximately EUR 2 billion despite the difficulties in establishing a viable hydrogen supply. In total, the transformation of steel production will cost around EUR 3 billion. In the long term, the use of hydrogen is expected to significantly reduce CO₂ emissions and open up new market opportunities for thyssenkrupp.
Analysts continue to view thyssenkrupp’s outlook positively. This week, Jefferies raised its price target from EUR 13 to EUR 16.50 and reaffirmed its “Buy” recommendation. Experts are banking on a recovery in the steel business and additional upside potential from the planned spin-off of the materials trading division. Deutsche Bank even expects the stock to rise to EUR 18.
Salzgitter: Pushes Ahead with Its Transformation
Salzgitter is also pushing ahead with its transformation into one of Europe’s leading green-steel producers. The company is making concrete progress. At its subsidiary, Hüttenwerke Krupp Mannesmann (HKM), in Duisburg, the company permanently shut down a blast furnace in September after more than 53 years of operation. In the future, one of Europe’s largest electric arc furnaces is set to produce significantly lower-carbon steel there. The new facility is scheduled to go into operation in 2029 and reach an annual production capacity of up to 2.5 million metric tons. Construction began in August and is being subsidized by the federal government and the state of North Rhine-Westphalia with EUR 200 million. With this investment, Salzgitter is laying the groundwork to make steel production more competitive and climate-friendly in the long term.
Salzgitter is also making progress in the area of energy supply. In mid-September, the subsidiary Salzgitter Flachstahl signed a long-term green power contract with the energy company Zelestra. The contract covers two solar projects with a total capacity of 147 MW, plus battery storage systems with a capacity of 79 MW and a storage capacity of 237 MWh. The facilities are being built in Brandenburg and Thuringia and are intended to cover part of the future electricity demand for low-carbon steel production. The combination of solar energy and battery storage enables more flexible use of renewable electricity. For Salzgitter, this is another building block in its transformation. If the group keeps production costs under control and meets growing demand for climate-friendly steel, the multi-billion-euro restructuring could also pay off for shareholders in the long term.
Strategic Resources: A Stock with Upside Potential?
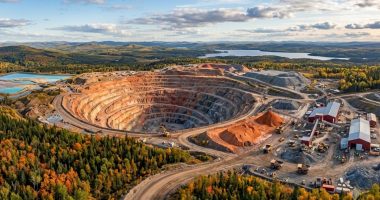
But who benefits when steel companies like thyssenkrupp switch to more climate-friendly production processes? One possible answer is Strategic Resources. The Canadian company aims to produce high-quality iron ore pellets for direct reduction, thereby supplying a key raw material for the green steel industry. With a planned annual production volume of 4 million metric tonnes, Strategic Resources could become an attractive supplier.
To this end, the company is pushing forward with the development of the BlackRock project in the Canadian province of Québec. The planned open-pit mine for vanadium, titanium, and iron, as well as a processing plant, have already received full approval. In addition, there are plans for a metallurgical complex at the Port of Saguenay, which is to be connected to the mine via a rail link approximately 400 km long. The project enjoys the support of the Government of Québec as well as local municipalities and Indigenous communities.
Annual production is projected to be approximately 550,000 metric tons of high-purity pig iron, 120,000 metric tons of titanium, and 40,000 metric tons of vanadium. Vanadium, in particular, offers significant potential, as North America currently has no domestic primary mining production of this metal. The metal is used, among other things, in high-quality steel alloys, the aerospace industry, and battery storage. Strategic Resources could thus become a key supplier of critical raw materials in North America. The long-term outlook is supported by large raw-material deposits. For the first open-pit mine alone, the company cites a potential operating life of 39 years. The company therefore sees significant growth potential for the coming years.
The green steel sector is gaining positive momentum. Companies along the value chain should benefit from this. thyssenkrupp shares have impressively demonstrated what is possible in recent months. By contrast, Strategic Resources still appears to have room for growth. This also applies to Salzgitter.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.