
Evotec: Once Again on the Hunt for Executive Leadership
The Hamburg-based drug discovery company Evotec SE still cannot find stability at the executive level. It must cope with yet another high-profile departure amid a sensitive restructuring phase. In a surprise move, the SDAX-listed company announced that its long-time Chief Scientific Officer (CSO), Dr. Cord Dohrmann, has stepped down by mutual agreement. For over 16 years, Dohrmann was a defining figure in the group’s scientific excellence and helped advance technologies such as iPSC stem cell research. For CEO Dr. Christian Wojczewski, who has only been in office since the summer, this personnel change means he must now fill one of the most critical positions while simultaneously navigating the company’s ongoing strict cost-cutting measures. According to the company, the search for a suitable successor was initiated immediately; however, this leaves a strategic gap in scientific leadership for the time being. After cutting the revenue forecast by about 20%, the company also issued major profit warnings, as EBITDA is now expected to range from minus EUR 70 to 105 million instead of breaking even. With a 57% loss and a drop below EUR 3 over the past 12 months, Evotec currently tops the losers list. However, analysts on the LSEG platform remain optimistic and have set an average 12-month price target of EUR 4.50. Highly interesting for traders!
Bayer: Portfolio Restructuring Puts Bayer Back on the Path to Growth
Few anticipated the easing of the glyphosate conflict, yet Bayer’s stock price has already doubled again in just 10 months. The next price surge could be on the horizon. With significantly more financial breathing room, the pharmaceutical and chemical conglomerate is systematically reducing its debt through an aggressive mix of capital measures and portfolio restructuring. The recent placement of new hybrid bonds totaling EUR 2 billion provided a significant liquidity boost. Key point: Leading rating agencies count 50% of these securities as equity, which noticeably improves key balance-sheet and creditworthiness metrics. Additional capital is coming from the sale of selected assets, including the global rights to the cancer drug Stivarga to the Aachen-based pharmaceutical company Grünenthal. This will bring an additional up to EUR 375 million to Leverkusen. Together with the previously agreed-upon financing worth billions from Apollo, Bayer is thus gaining considerable financial flexibility and can now look ahead with renewed confidence.
Now comes good news from the FDA. The US Food and Drug Administration has accepted Bayer’s application to expand Kerendia’s indication to treat chronic kidney disease in adults without diabetes. This decision is based on the Phase III FIND-CKD study, in which Kerendia met the primary endpoint and significantly slowed kidney function loss. In addition, the risk of a combined renal-cardiovascular endpoint decreased significantly compared to placebo (hazard ratio 0.77). The FDA’s decision could significantly expand the drug’s indications, which are already approved for kidney disease in patients with diabetes and certain forms of heart failure. With an expected P/E ratio of just 9.2 for 2027, as projected by LSEG analysts, the stock currently appears reasonably priced at EUR 43, especially since the 12-month consensus stands at EUR 58.60.
Formycon: 2027 Could Bring Plenty of Surprises
Investors in Munich-based biosimilar specialist Formycon have weathered a rough ride. The stock reached prices of over EUR 90 during the pivotal transition year of 2022 through early 2023, but fell to a low of EUR 16.30 in 2026. The silver lining: The core investors have remained steadfast! The Strüngmann family of investors, known for their stakes in Hexal Pharma and BioNTech, still holds a roughly 24% stake today. In addition, major investor and “Back” icon Peter Wendeln is also on board with a stake of over 13%. Despite poor share price performance so far in 2026, the Munich-based company’s outlook looks promising, as analysts predict it will shift into “turbo mode” operationally and financially for the 2027 fiscal year. After reaching the operating break-even point in 2026, as announced, experts on the LSEG Refinitiv platform forecast a massive jump in earnings for the coming year, with estimated revenue over EUR 107 million, up from just EUR 44.5 million in 2025. Based on these calculations, the resulting EBITDA, which market experts expect to soar from nearly zero to over EUR 46 million thanks to massive economies of scale in the product portfolio, would be impressive. This rally is driven by ongoing market penetration of established biosimilars such as the Stelara biosimilar FYB202 and the recently launched ophthalmic drug FYB203 in Europe. However, the primary driver of the 2027 share price remains the highly anticipated FYB206, a Keytruda biosimilar in cancer immunotherapy, whose upcoming approval and potentially lucrative licensing partnerships are likely to drive significant revenue. The current share price of approximately EUR 19 still reflects a fairly moderate market capitalization of EUR 335 million. It would be nice if the prolonged consolidation phase since March were finally coming to an end. Very exciting!
Novo Nordisk: Technological Quantum Leap Countermoves Legal Setbacks
Much is also happening at the Danish pharmaceutical giant Novo Nordisk. The index heavyweight is still navigating turbulent waters after a year-to-date loss of over 34%, but alongside protracted legal disputes, it is also pursuing major, forward-looking transactions. The financially strong alliance with the Swedish specialists at Nanexa recently caused quite a stir. This partnership gives the Scandinavian company exclusive rights to a novel drug-delivery technology that could drastically extend dosing intervals for in-demand obesity treatments—moving away from weekly injections toward monthly or even quarterly cycles. Such a quantum leap has the potential to permanently secure the company’s lead in the lucrative weight-loss market.
In contrast, a legal dispute is unfolding in the US market, where generic drug manufacturer Mylan is trying to overturn patent protection for Wegovy’s injection systems in court. Such attacks by generic drug manufacturers weigh on short-term sentiment, yet they have little impact on the industry leader’s existing market share. Even amid fierce competition and health policy debates over price caps, the Danish company’s development pipeline remains well-stocked and promises a whole series of future blockbusters. Even though only 7 out of 31 analysts on the LSEG Refinitiv platform currently issue an explicit “Buy” recommendation, the median price target of DKK 315 signals attractive upside potential of about a quarter compared to the most recent closing price. And when most analysts are already feeling pessimistic, things can only get better from here!
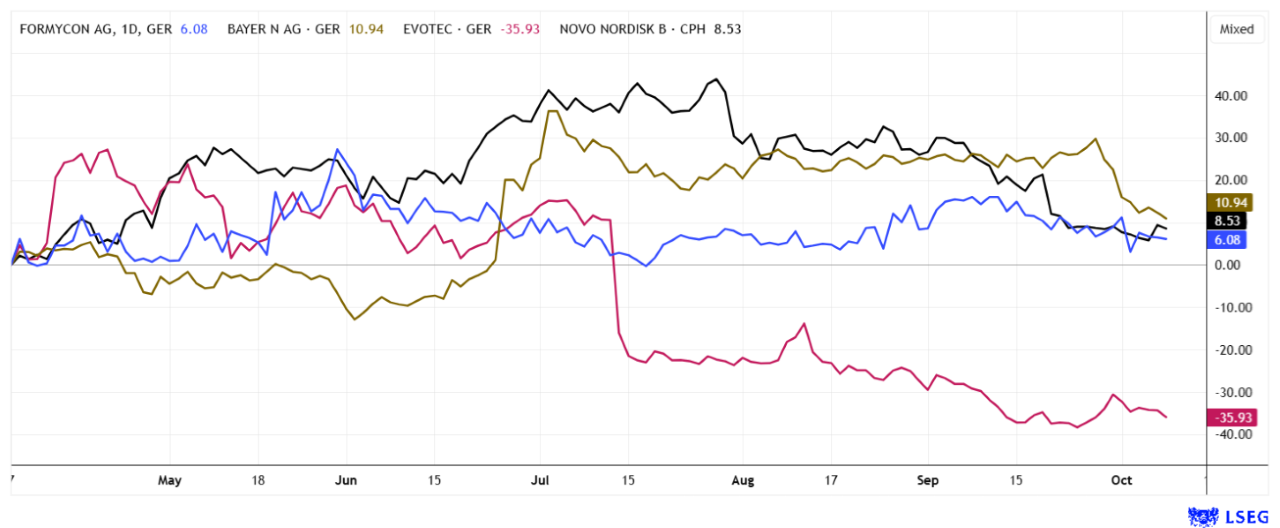
The spotlight on the financial markets is once again increasingly focused on the life sciences sector. Alongside highly innovative, novel therapies, strategically positioned generic drugs are increasingly taking centre stage. Thanks in part to a noticeable industry-wide recovery in liquidity, many players in the capital markets are once again seeing genuine, fundamental breakthroughs. With good diversification, investors can effectively mitigate portfolio volatility.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.