
Washington funds remediation through to the end of the decade
The US faces a massive legacy problem. For decades, oil and gas wells were abandoned without being properly plugged. Methane, a particularly potent greenhouse gas, continues to escape from many of these sites. At the same time, the wells can threaten groundwater and make former production sites harder to use.
Through the Infrastructure Investment and Jobs Act (IIJA) of 2021, the US Congress allocated around USD 4.7 billion for the remediation of orphaned wells. Of this, USD 4.3 billion is allocated to state and private land. Under the original plans, funding from individual grant programmes is available through September 2030.
For specialist service providers, this means long-term business opportunities. However, contracts are awarded through public tenders. There is no guaranteed share of the funding.
Zefiro secures contracts worth USD 40 million
One active provider is Zefiro Methane. The North American company plugs abandoned wells, surveys former production sites and measures methane emissions. Through its subsidiary Plants & Goodwin, Zefiro has more than 50 years of industry experience.
In mid-October, the company reported a backlog of public projects already awarded worth around USD 40 million. Some of the work extends through June 2029.
A three-year contract with the Ohio Department of Natural Resources alone is worth USD 19.6 million. Under this contract, crews will decommission around 200 problematic wells. In addition, there is a state-funded contract worth USD 11.5 million in the Great Lakes region.
Around USD 4.9 million of the order backlog is to be completed in the current quarter ending in December 2026. A further USD 34.6 million is scheduled mainly for 2027 and 2028. These figures do not yet include additional private industrial contracts.
Revenue grows by 31% – losses fall significantly
The expansion is increasingly reflected in the financial results. In the 2026 financial year, ended June 30, Zefiro increased revenue by 31.1% to USD 42.5 million. Gross profit rose 66% to USD 12.4 million.
At the same time, the net loss narrowed from USD 10.8 million to USD 3.5 million. Adjusted EBITDA improved from minus USD 4 million to plus USD 3.8 million.
The acquisition of operating assets from Viking Well Service in May opened up additional growth opportunities. For USD 4.3 million, Zefiro secured, among other things, five additional drilling rigs. This is expected to increase annual revenue capacity by around USD 10 million.
New customers are increasingly coming from industry. Particularly in energy and data centre projects, former production sites often have to be remediated before new infrastructure can be built.
Analysts see more than 200% upside potential
Augsburg-based GBC AG also takes a positive view of the development. In their study dated October 28, 2026, the analysts confirmed their Buy rating with a price target of USD 1.42 by June 2027.
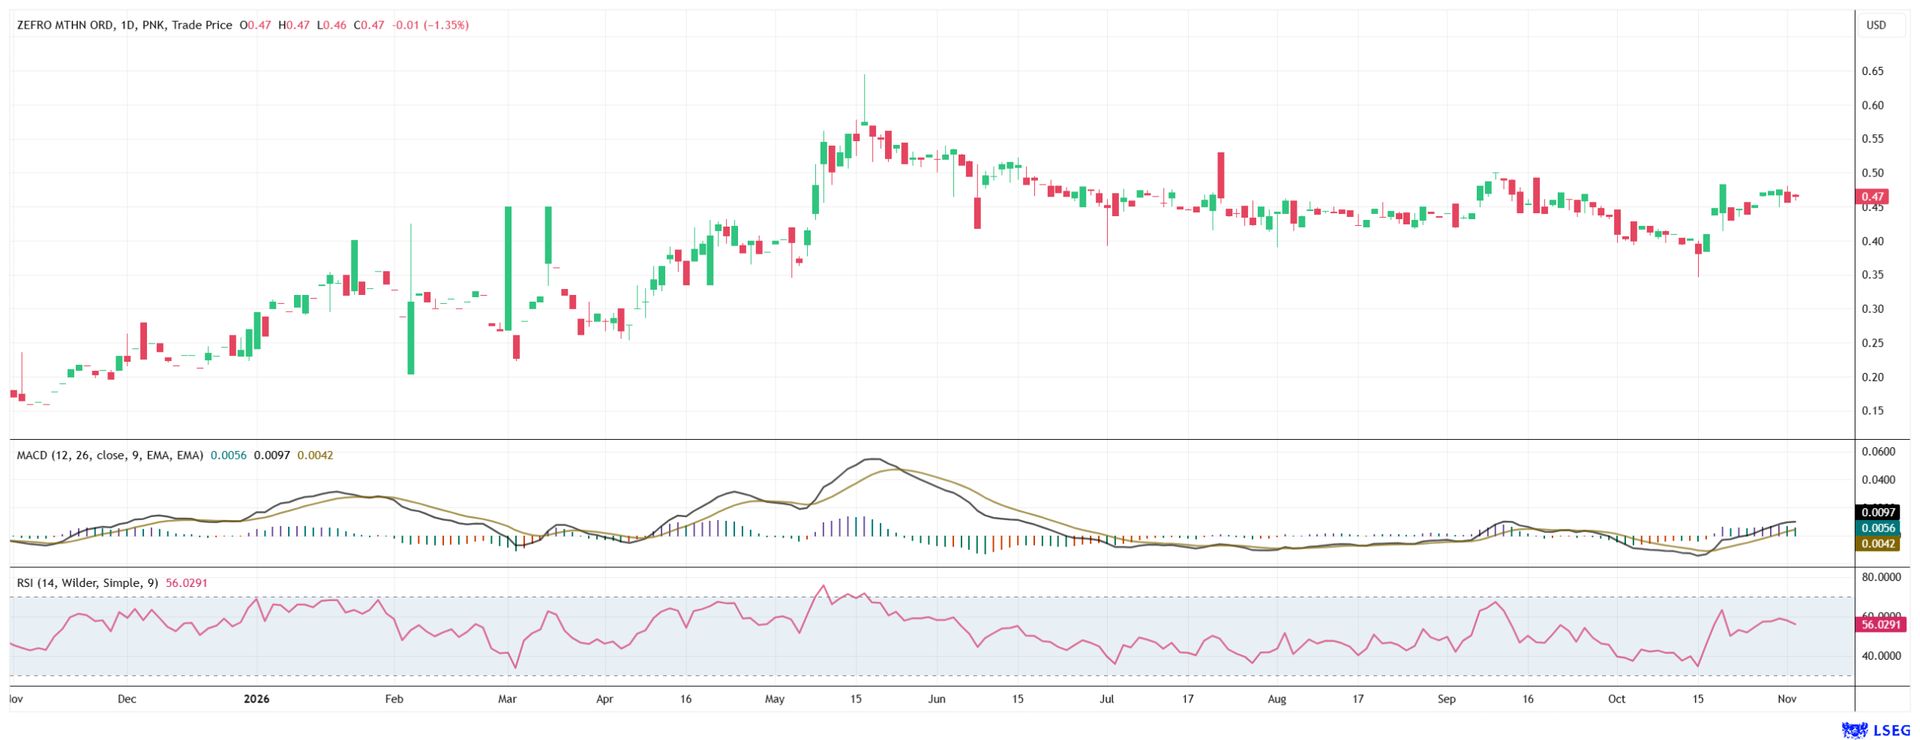
Compared with the current share price of USD 0.47, this represents a calculated upside potential of around 202%.
For the 2026/27 financial year, GBC forecasts revenue of USD 57.92 million and EBITDA of USD 10.02 million. Revenue is expected to rise to USD 75.21 million by 2028/29.
Methane credits as an additional source of income
Alongside public and private remediation contracts, Zefiro is working on another business area. The company recently reported on its involvement in developing a certification standard for the decommissioning of orphaned oil and gas wells.
The framework developed by the provider Isometric is still undergoing public consultation. In the future, eligible projects not already publicly funded could generate additional income from verified methane avoidance.
The company is not yet profitable on the bottom line. However, growing revenue, additional drilling rigs and the large order backlog significantly improve its starting position.
Zefiro benefits from a problem that is likely to occupy the US for years to come. The decisive factor will be whether the government programmes worth billions and private remediation contracts generate sustained profit growth.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.