
Barrick Mining: Strong Profit Jump, but Rising Costs
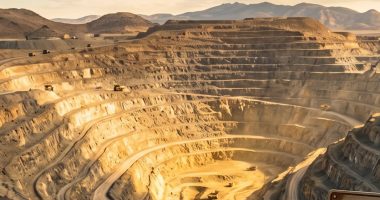
Investors looking to bet on large-scale ongoing production need a producer that is currently among the world’s largest. That company is Barrick Mining. Headquartered in Toronto, Canada, the group operates mines in Nevada in partnership with Newmont. It also owns the Pueblo Viejo mine in the Dominican Republic and the Lumwana copper mine in Zambia. Production of 2.90 to 3.25 million ounces of gold is planned for 2026. In Mali, the deadlock has also been broken. Since the end of 2025, the Canadians have been operating the Loulo-Gounkoto mine on their own again. Production is on track, and the on-site issues have been resolved.
On August 10, Barrick released its second-quarter results. Revenue per ounce was USD 4,417. By comparison, it was USD 3,295 a year earlier. That is an increase of 34%. Revenue grew by 44% to USD 5.29 billion, and net income rose by 50% to USD 1.22 billion. This is exactly where the gold price is working in the company’s favour. However, free cash flow amounted to just USD 141 million, down from USD 212 million. Meanwhile, the company reached an agreement with Newmont in the dispute over the Nevada joint venture. Newmont will pay USD 1.95 billion in cash and also contribute the Fiberline and Mike projects.
Gold leverage is being held back by costs. All-in costs per ounce of gold rose to USD 1,866, up from USD 1,684 in the previous year. Higher fuel prices and retroactive levies, including penalties, in Mali weighed on results. It will also take time for the company to develop new gold deposits. For the Fourmile project in Nevada, the pre-feasibility study is not scheduled to be completed until 2028. The next key milestone is the initial public offering (IPO) of the North American mines by year-end. However, on September 2, Bloomberg reported that Barrick was considering postponing the IPO until 2027. If the spin-off can still be completed in 2026, it would be a major coup, but the timeline is shaky.
DRC Gold: Option Agreement for Giro and Nizi in Place
On September 1, DRC Gold announced the next step in the Congo. The Canadians have signed an option agreement dated August 25 that replaces the February agreement. This allows them to secure a 55% stake in Giro Goldfields. This project company holds the Giro project and is also set to take over the Nizi license. Payment will be made in shares. 25 million shares were already issued in May, with an additional 325 million to follow upon approval by shareholders and the CSE stock exchange. Both parties have completed their due diligence. Now it is up to the shareholders.
The Giro project is located around 35 km west of Kibali. According to DRC Gold, the Kibali mine produces more than 600,000 ounces of gold each year. For the Kebigada deposit, a 2020 estimate was 4.10 million ounces at 1.03 g/t gold. New drilling could bring this figure up to current standards. Nizi has a long history. Gold was mined at the King Leopold Mine between 1913 and 1931. However, only two of up to seven known quartz veins were mined. The rest have been dormant ever since.
For a gold company with multiple mines, a few million ounces more is just one item among many. For an explorer like DRC Gold, on the other hand, nearly the entire valuation hinges on the ounces that can be confirmed. If the Kebigada resource is successfully confirmed in accordance with the Canadian NI 43-101 standard and modern drilling at Nizi strikes gold, the company could move up to a whole new league. In addition, the agreement grants DRC Gold the right to increase its stake in Giro Goldfields. At Moto Goldmines, a former employer of CEO Klaus Eckhof, a resource of over 20 million ounces was defined within four years. The Kibali Mine was developed on Moto Goldmines’ property. This demonstrates just how significant the leverage is.
B2Gold: Higher Revenue, but Less Gold
B2Gold’s gold production spans several continents. The company operates mines in Mali, the Philippines, Namibia, and, most recently, in Nunavut, Canada. Its most important asset is Fekola in western Mali, which the company claims is the country’s largest gold producer. Since 2014, the Canadian company has invested over USD 2.0 billion there and employs more than 3,300 people, about 98% of whom are from Mali. The Goose Mine in the Arctic, by contrast, is still in the ramp-up phase. The rise in the price of gold is playing into the company’s hands. However, its foundation lies in West Africa.
On August 6, B2Gold released its second-quarter results. The company produced 203,648 ounces of gold. In the same quarter of the previous year, production stood at 229,454 ounces. Because the realized gold price rose from USD 3,290 to USD 3,767 per ounce, gold revenue still grew to USD 789.4 million from USD 692.2 million. However, total costs also climbed to USD 2,356 per ounce from USD 1,519. Adjusted earnings came in at just USD 41 million. By comparison, they were USD 162.8 million the previous year. That was not exactly a home run. At the same time, the company spent USD 92 million on share buybacks.
On August 7, Mali granted the mining permit for Menankoto. The area is part of the Fekola Regional project, which is expected to produce over 150,000 ounces annually from 2028 through the mid-2030s. However, the government holds a 35% stake there. For 2026, the Canadians narrowed their forecast to 820,000 to 920,000 ounces; previously, the upper limit had been 970,000. The main reason is the Goose mine, which, following a fire in the crusher, can now contribute only 170,000 to 200,000 ounces. If repairs are completed as planned in the third quarter, Goose could finally get back on track.
Gold remains a powerful lever, but the three stocks represent very different risk profiles. Barrick Mining impresses with its size and jump in profits, but is struggling with rising costs and a shaky IPO plan. DRC Gold offers the greatest exploration leverage in the Congo, with its valuation hinging on confirming large resources. B2Gold is increasing revenue but producing less gold and must keep Goose and Mali under control.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.