
TUI and Lufthansa – Strong Results, but Shares Have Reversed Course
The Democrats’ surprising success in the midterms is putting the brakes on Donald Trump’s protectionist plans and providing palpable relief on international markets. As a direct beneficiary of this political easing, Lufthansa is in the spotlight, as falling jet fuel prices are massively reducing operating costs. The latest third-quarter figures underscored the airline’s fundamental strength, with revenue rising 9% to a near-record EUR 12.24 billion and adjusted EBIT increasing to EUR 1.41 billion. Despite the burden of historically high fuel costs, the group showed strong resilience thanks to robust premium demand. With these figures behind it, the crane-logo airline is optimistic about the coming year, when efficiency gains and lower fuel costs could trigger a significant share price rebound. Analysts on the LSEG platform share this view, with an average price target of around EUR 9.35.
For tourism giant TUI too, the political signal from the US marks the starting gun for a potential recovery in the travel market. Falling oil prices directly ease the cost burden on the group’s aircraft fleet and cruise ships, significantly improving the travel operator’s margins. The latest quarterly figures for the third financial quarter show the business model has proved extremely resilient despite geopolitical challenges in the Middle East. Although higher fuel costs and customers booking at shorter notice initially pushed adjusted EBIT down to EUR 233.8 million, the revenue base remained remarkably robust at EUR 5.9 billion. Looking ahead, management continues to expect positive momentum and confirmed its full-year EBIT guidance of EUR 1.1 to 1.4 billion. With prices at the pump easing and consumers’ appetite for spending growing, little stands in the way of a strong wave of bookings for the coming seasons. Here too, LSEG analysts expect a strong turnaround to EUR 9.74 over the next 12 months. Exciting!
Ryanair – Half-year profit decline and Kassel newly added to the schedule
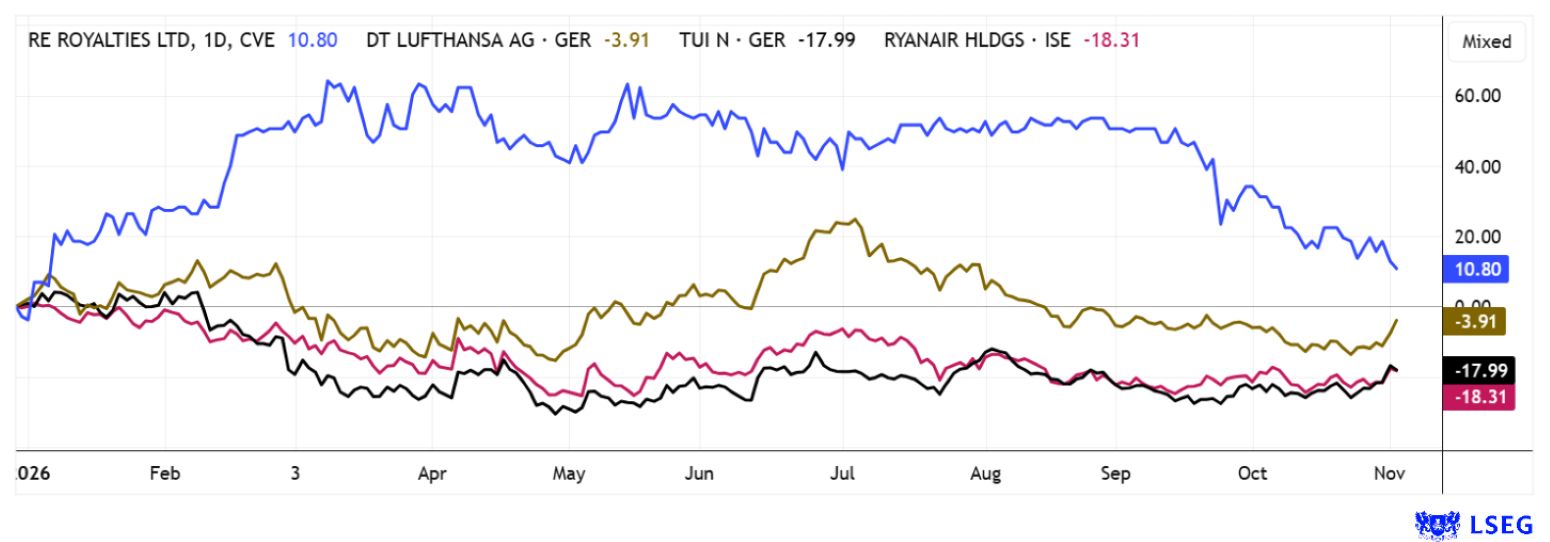
A bombshell in northern Hesse: Irish low-cost carrier Ryanair is heading for Kassel-Calden Airport from summer 2027! With new direct flights to Mallorca and southern Italy, the airline is lending a helping hand to the chronically underused regional airport, which urgently needed a success story after the embarrassing Fischer Air debacle in the spring and a completely deserted winter flight schedule. While airport operators hope passenger numbers will stabilise and the perennial subsidy debates will end, the deal is unlikely to be a financial walkover. After all, Ryanair is known for negotiating airport charges down to the absolute minimum. Things are not going smoothly for the industry giant at present anyway, as the newly released half-year figures show a 15% decline in profit to EUR 2.15 billion. The slump is primarily due to sharply rising jet fuel costs, which have severely dented earnings. To counter this, management is now pulling the emergency brake and switching to a tough cost-cutting programme, under which it will rigorously renegotiate existing airport contracts alongside internal savings measures. Overall, however, the share has weathered the recent years of war well and is still up 52% over three years. The loss in the current year is a manageable 17%, but 16 of 19 analysts on the LSEG platform give it the thumbs-up. Something, at least!
RE Royalties – Fresh capital for the next stage of growth
From the travel market to sustainable financing. RE Royalties has been quiet in recent months, but now the Canadians are delivering their next blockbuster deal. With a fifth green bond issue, the company aims to raise up to CAD 5 million in fresh capital to finance additional stakes in sustainable energy projects. The structure is noteworthy: the five-year bonds bear interest at 7.5% per annum, paid quarterly, and are secured by the existing portfolio of royalties and loan receivables. In addition, investors receive 1,000 warrants per bond unit, entitling them to subscribe for one share at CAD 0.35 within 24 months. This once again gives RE Royalties access to capital that enables further growth without immediately triggering conventional share dilution. The proceeds are to be invested entirely in new financing for renewable energy and emissions-reducing technologies, allowing the cycle of capital raising, royalty income and reinvestment to continue.
The company already holds more than 100 royalty interests in solar, wind, hydropower, battery storage and renewable natural gas, spread across North and South America as well as Asia. Over the past few months, the strategic review process has taken significantly clearer shape: management reports sustained interest from strategic and financial investors and continues to hold talks with various potential partners. Range Renewables has also been brought in as an adviser to broaden access to US capital providers, industry players and strategic contacts – an important lever in one of the world’s largest renewable energy markets. Changes are also being made at board level. With co-founder Marchand Snyman stepping down from the Board of Directors, CEO Bernard Tan is also taking over as chairman, ensuring closer alignment between operational leadership and strategic direction. The change marks the end of a formative development phase, as the company now focuses more on scaling up and new financing partnerships.
Vice President Talia Becket in conversation with IIF moderator Lyndsay Malchuk about the future of the financier in the renewable energy sector.
The current market environment is also providing a noticeable tailwind: in its analyses, the International Energy Agency (IEA) continues to see an enormous need for investment in clean energy, with solar power and storage solutions in particular among the most dynamic growth drivers. With the shift to the left in the US, the opportunities for promising projects that were less favoured under Donald Trump are increasing. RE Royalties positions itself as a capital provider in the background, participating in long-term revenue streams without building or operating power plants itself. If it deploys the fresh capital in a disciplined manner and turns the strategic review process into concrete partnerships or a value-enhancing transaction, the currently small royalty specialist could become a substantially larger financing platform. A closer look should prove worthwhile for risk-aware investors over the medium term.
Conclusion
The stock market environment remains tough and requires risk-aware investors to maintain a medium-term focus on a significant improvement in sentiment. After all, daily fluctuations of over 5% have long ceased to be an exception for individual stocks. In our selection, RE Royalties scores points with a clearly focused financing model, while TUI, Ryanair and Lufthansa are banking on the return of high-margin tourism. Falling oil prices are at least easing the pressure on the aviation industry’s already thin margins.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.