

Eli Lilly: New highs despite twist with Novo Nordisk
Another new annual high at EUR 1,294. Eli Lilly is racing from one stock market record to the next, setting new highs despite fierce competition from Novo Nordisk in the obesity segment. The US pharmaceutical company continues to benefit enormously from the tremendous demand for its blockbuster medicines for weight loss and diabetes treatment. The Danish rival dominated the market with its established products for a long time, but Eli Lilly is now catching up rapidly with Mounjaro and Zepbound. The ongoing battle between the two industry giants is driving substantial innovation in GLP-1 receptor agonists and fuelling investors’ imagination. Despite supply bottlenecks, the group is steadily expanding production capacity and consolidating its market position. Analysts see this momentum as the start of a long-term growth cycle, as the global market for obesity therapies grows dramatically.
Eli Lilly’s revenue climbed an impressive 39% year on year to USD 24.40 billion in Q3. The main drivers were the medicines Mounjaro, with revenue of USD 10.72 billion, and Zepbound, with USD 5.35 billion. Adjusted earnings per share rose 7% to USD 7.48, significantly exceeding analysts’ expectations. Given persistently strong demand, the pharmaceutical group raised its revenue forecast for full-year 2026 from USD 88 billion to USD 91 to 92 billion. Regulatory hurdles or smaller competitors cannot halt the share’s strong run for now. For investors, the pharmaceutical giant remains a driving force in the global healthcare sector. The company is a prime example of successful innovation amid intense market competition.
Bayer: The first glyphosate trial has now been won
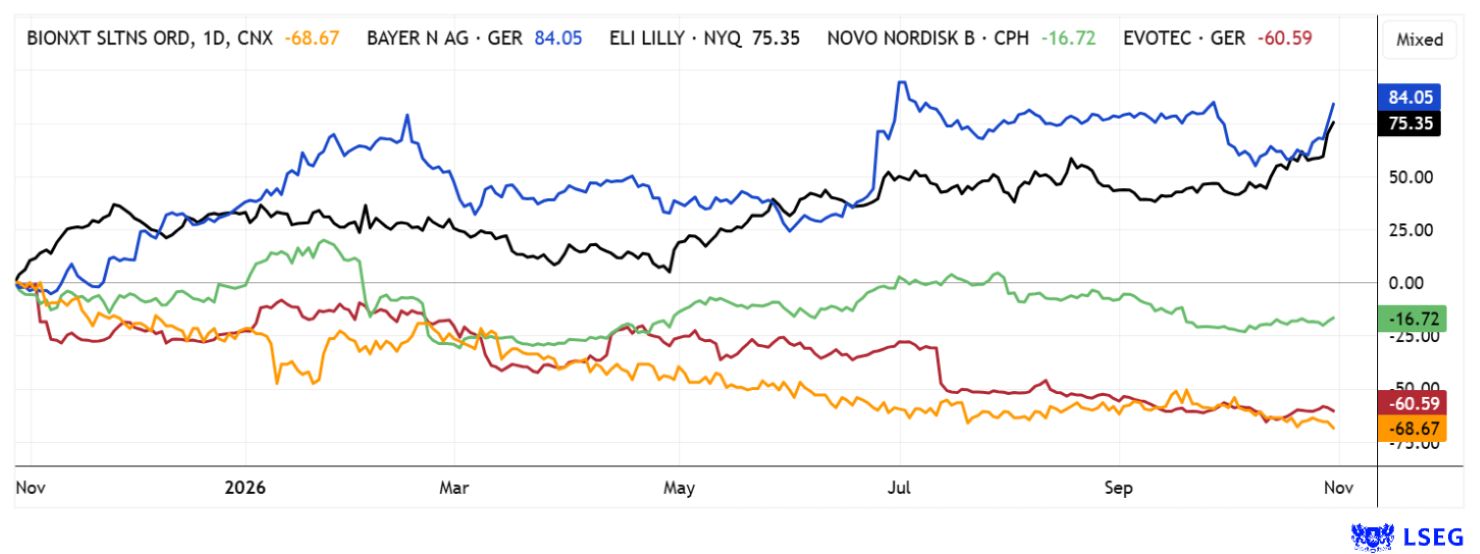
And yet another jump above the EUR 50 mark! The Leverkusen-based agricultural and pharmaceutical group Bayer has reached an important milestone in the protracted glyphosate litigation, winning its first jury trial in the US. A jury in California ruled that the company’s Roundup weedkiller was not responsible for a plaintiff’s cancer. This legal success brings tangible relief to the heavily battered share and fuels hopes of a turnaround in this closely watched sector. Analysts see the verdict as an important signal, as it breaks a sequence of previous weedkiller trial losses. For the group, which has carried the burden of US litigation for years, this victory is a significant psychological win. Nevertheless, the glyphosate issue is still far from resolved for the company, as tens of thousands of lawsuits remain pending in the US. The group will have to continue its aggressive approach in the courtrooms to avert or reduce further costly settlements. Nevertheless, investors are now once again taking a somewhat more optimistic view of the group’s operating business and its future in agriculture. Analysts on the LSEG platform have once again set their 12-month price target significantly higher, at over EUR 58. The Q3 figures are expected on November 3. Another breakthrough could be on the agenda.
BioNxt Solutions: The leap into the clinical development phase draws closer
Much smaller, but with major technological irons in the fire, the Canadian company BioNxt Solutions is trying to catch up with the industry’s major players. Its current focus is on developing an innovative drug platform that could substantially increase its valuation if it achieves a broad breakthrough. With GMP production of around 1,500 drug films completed and the European clinical trial application submitted, the promising candidate BNT23001 is reaching an important milestone. At its heart is a novel sublingual dosage form of the MS drug cladribine, which is intended to make it easier for patients to take their medication. Human testing is now within reach for the first time, with particular emphasis on investigating bioavailability and comparability with the approved medicine Mavenclad. Furthermore, BioNxt’s technology platform opens up additional prospects in obesity, neurological diseases and targeted cancer therapies.
The required Investigational Medicinal Product Dossier (IMPD) was completed back in August, followed in mid-October by the submission of the clinical trial application through the European CTIS system. This means BNT23001 is officially undergoing regulatory review, which, according to the company’s plans, could take approximately three months. Final quality controls, formal batch release and regulatory and ethics approvals are still pending before the study can begin. For BioNxt, this marks the transition from preclinical development work to the intended clinical testing. The BNT23001 development programme has a clear objective: in future, the established active ingredient cladribine is to be available not only as a conventional tablet, but also as a thin film that dissolves under the tongue. This dosage form could represent a tangible advance, particularly for people with multiple sclerosis who suffer from swallowing difficulties. A planned randomised crossover study in healthy adults is to compare absorption of the active ingredient with that of the approved product Mavenclad. The key factors are the pharmacokinetic properties, relative bioavailability and whether the required bioequivalence criteria are met. If this can be demonstrated, BioNxt would have established an important basis for further clinical development and a potential European approval pathway.
However, the real investment appeal lies not solely in the cladribine project, but in the broader technology platform. Alongside oral dissolving films (ODFs), BioNxt is also developing transdermal patch systems, oral formulations and a technology for targeted drug delivery in cancer therapy. The prospect of further developing established active ingredients such as semaglutide for more convenient oral administration remains particularly interesting. In oncology, the company is also pursuing an approach aimed at concentrating highly toxic chemotherapy drugs as selectively as possible in tumour tissue while sparing healthy tissue. In vitro studies provided initial promising indications of a significantly improved therapeutic effect, although clinical significance still needs to be confirmed through further development. BioNxt is positioning itself as a technology-focused developer that does not necessarily need to discover new active ingredients, but instead aims to open additional market opportunities for existing medicines through intelligent delivery systems.
On the stock market, BioNxt continues to trade as a speculative small-cap biotech whose valuation depends heavily on the successful implementation of its development programmes. So far, BioNxt has cleared two important operational hurdles with GMP production and the European study application, bringing it closer to a potentially share-price-sensitive turning point. With a market capitalisation of around CAD 37 million, investors are watching regulatory progress, clinical data and potential pharmaceutical partnerships. Entire worlds can change overnight here!
Evotec: Things are now getting extremely exciting
Steady nerves are needed now! Despite the recent plunge in Evotec shares to below EUR 2.50, the speculative element remains. The Hamburg-based drug developer is regarded as a hot takeover target, as major shareholder Triton remains in play and Goldman Sachs has expanded its derivatives positions to over 13% of the outstanding shares. The official quarterly report on November 5, 2026, must now provide the final nine-month figures, after preliminary data delivered a positive surprise. Operationally, the “Project Horizon” cost-cutting programme, along with new personnel from Novo Nordisk, is expected to drive the turnaround. The latest rating changes reflect deep scepticism: according to LSEG Refinitiv, following massive downgrades, only a single Buy recommendation from RBC remains for the biotech stock, with a price target of EUR 5. Analysts’ consensus price target has fallen by a full EUR 6 over the past 12 months to EUR 3.76. Should a takeover offer emerge, a rational assessment would suggest that even EUR 4 to 5 per share may be out of reach. What an endless ordeal for shareholders.

Conclusion
While the tech sector struggles with record valuations and a growing risk of overheating after its spectacular rally, life sciences looks like a historically attractive counterposition. As soon as the market initiates the usual sector rotation, the companies mentioned above are likely to reappear quickly on institutional investors’ shopping lists. A rediscovery is overdue, as fundamentals are improving while current valuations continue to offer room for upside.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.