
Adidas: Back in the fast lane with strong direct sales and new records
The global sporting goods market is hard to predict. Hype can be over faster than it began. Few things are as fast-moving as fashion. Brand management and sales discipline determine success or failure for sporting goods manufacturers. The German heritage brand Adidas has made an impressive comeback in recent days and weeks and could finally be ready to leave behind the prolonged crisis mode it has been stuck in for the past few months (since the end of February 2025). While competitors have also stumbled recently, the brand with the three stripes is making a targeted push for new market share. Global demand for performance products is proving a stable foundation for the share price’s latest rally.
Operationally, things ran like a well-oiled machine in the third quarter just ended, as reflected in the financial figures. Quarterly revenue climbed 9% to just under EUR 7.3 billion, while currency-adjusted growth stood at a solid 7%. The group recorded double-digit growth particularly in North America and China, driven by a booming apparel business and strong direct-to-consumer sales. The operating margin also improved significantly to 13.9%, resulting in a bottom-line profit of EUR 711 million from continuing operations.
In light of this operational strength, management raised its full-year operating profit forecast to around EUR 2.5 billion. Renowned research houses such as Bernstein Research (EUR 245) and JPMorgan (EUR 230) see considerable upside potential with their price targets. However, challenges such as the stagnating footwear business and the recent setbacks in Europe are not entirely invisible. In addition, a EUR 200 million tariff refund effect supported the quarter, which should be mentioned for fairness. Retail investors backing a successful restructuring and strong brands will find a reliable turnaround candidate here.
The task now is to overcome the EUR 180 level and resistance area. However, this is unlikely to be easy. Nevertheless, this would then pave the way for prices well above the EUR 200 mark. Shares could be picked up on price weakness!
ServiceNow: Historic share price plunge stokes fears of an impending AI apocalypse
Stock markets are in turmoil when technology giants miss the high expectations of critical analysts by even the narrowest of margins. Cloud software specialist ServiceNow endured one of the darkest days in its corporate history, with its share price plunging around 27%. Fear of a so-called SaaS apocalypse, in which generative artificial intelligence displaces traditional business models, is spreading noticeably. Investors are wondering when the gigantic AI investments will finally deliver tangible results.
Yet ServiceNow’s figures are by no means catastrophic, as total revenue grew by more than 20% to USD 4.11 billion in the third quarter. However, adjusted earnings per share of USD 1.00 narrowly missed analysts’ estimates of USD 1.02. Growth in current remaining performance obligations also dampened the euphoria, as it slowed sequentially to 18.5%. Although the AI business is picking up noticeably with new tools, the market is currently barely rewarding this progress.
Despite the dramatic sell-off, the company’s operational foundations remain intact, with strong gross margins and solid cash flow. Goldman Sachs responded to the share price plunge by moderately raising its price target to USD 154, while the long-term growth story nevertheless remains under scrutiny. While the drastic share price slide brings the ambitious valuation down to a significantly lower level, it demands strong nerves from existing investors. Anyone buying into this technology stock is betting that the software platform will successfully become the indispensable control authority for AI agents.
From a technical chart perspective, however, the share price could now fall further first. The shock and disappointment were likely too great. The psychologically important USD 100 mark beckons. Caution is advised until a sustainable bottom has been reached.
Globex Mining Enterprises: Royalty gem with excellent underlying assets and a strong chart signal
Away from Adidas and ServiceNow, a specialised project developer and licensor in resource-rich North America is emerging as a quiet and unassuming winner. With a broadly diversified portfolio of over 270 mineral and royalty assets, Globex Mining Enterprises offers an impressively diversified mix of resource companies. Its business-model licensing concept protects the company from operational mining risks and generates reliable income. The key advantage of this model is that, rather than funding costly drilling itself, Globex Mining participates in the success of its partner companies. They assume the exploration risk and, if successful, Globex receives the contractually agreed payments. Even if they fail to meet their objectives, Globex still receives compensation, for example in the form of option payments. In addition, the mineral deposit has nevertheless been further advanced.
The latest company announcements underline this approach with good exploration results and operational milestones.
TomaGold reported outstanding polymetallic intersections at the Berrigan property, with thick zinc, gold and silver zones, on which Globex holds a Gross Metal Royalty of 2%. Excellent gold grades were also demonstrated at the Bartec project.
Globex’s management reinforces its shareholder-friendly approach with an approved share buyback programme covering up to 1,000,000 shares for cancellation. With a strong balance sheet, nearly CAD 40 million (CAD 8.03 million in cash and CAD 31.74 million in investments) and no debt, the company is in robust financial health.
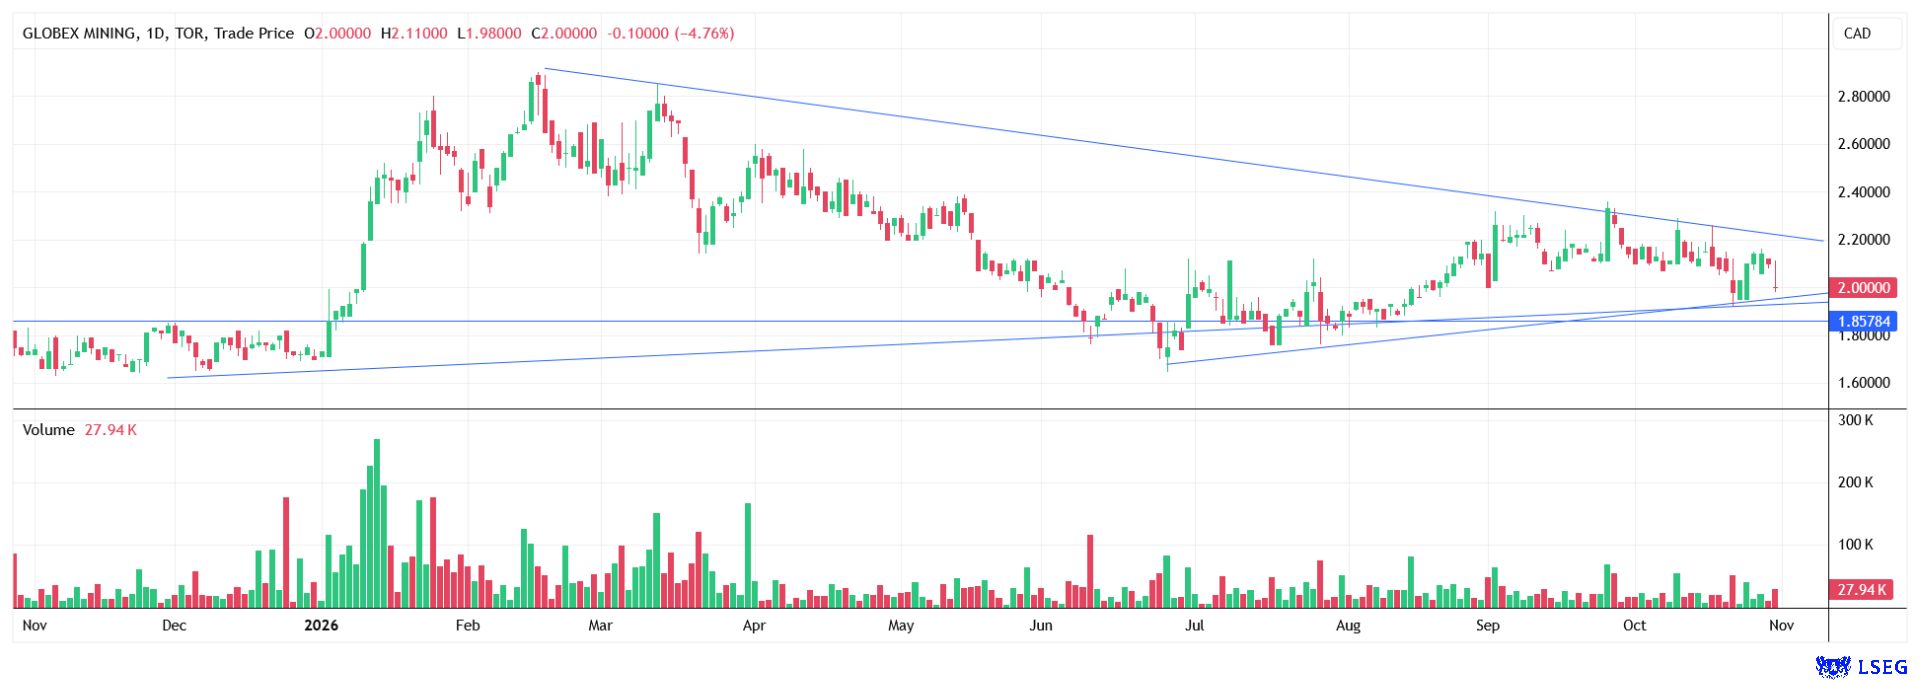
From a technical perspective, the shares are in an interesting position that could lay the groundwork for the next upward move, as the price is moving within a wedge formation, currently around CAD 2.00, with an initial upper boundary at CAD 2.20. Solid downside support is provided by horizontal and upward-sloping trend lines between CAD 1.86 and CAD 1.97. Following a successful breakout from this wedge at CAD 2.20 to CAD 2.25, the price could head straight toward the resistance levels at CAD 2.60 or CAD 2.80. If it also breaks through these levels, targets between CAD 3.00 and CAD 3.20 come within reach.
Conclusion
Adidas impresses as a strong turnaround candidate with record revenue, excellent margins and a confident outlook for the fourth quarter. ServiceNow is suffering from massive fears of AI disruption and missed earnings expectations, but could offer an interesting rebound opportunity after a bottoming-out phase. Globex Mining appears to be a fundamentally solid royalty stock with a strong balance sheet, high-profile partner successes and a promising technical setup.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.