
dynaCERT: Vietnam Is Expected to Deliver the Breakthrough
Diesel trucks, construction equipment, port vehicles, and generators will still be needed in many places for the foreseeable future. Replacing them costs money, and charging infrastructure is far from being available everywhere. This is exactly where dynaCERT comes in. The Canadian company aims to make existing engines more efficient and help fleet operators reduce fuel costs and emissions. The large existing fleet of machinery opens up an attractive market for retrofits.
At the heart of the system is HydraGEN™. During operation, the system uses electrolysis to generate hydrogen and oxygen and feeds the gases to the engine via the air intake. This is designed to improve combustion and reduce diesel consumption. The savings can be particularly significant for high-mileage vehicles. The key factor is that the benefits in each specific application convincingly outweigh the acquisition and operating costs.
A key foundation is the General Operating Permit already granted by the Federal Motor Transport Authority. Added to this is the methodology recognized by Verra for tracking efficiency improvements in vehicle fleets. HydraLytica is designed to collect fuel consumption data and calculate avoided emissions. This could lead to an additional business opportunity involving CO₂ credits. However, further steps are necessary before actual revenue from the credits begins to flow.
Operationally, the focus is on Vietnam. In June, following successful pilot tests, dynaCERT announced its first production order from a transportation and logistics company. In addition, HydraGEN™ systems were installed on trucks and container handling equipment belonging to an international port operator. The company did not disclose the quantity or value of the production order. Nevertheless, this is a significant step: a test has turned into a paying customer—a first hurdle on the path to larger fleet orders has been cleared.
An update followed on August 6. Preparations for another truck pilot project at a waste and recycling company in the Hanoi area had been completed. A Vietnamese oil and gas company had selected fire trucks, forklifts, and mobile cranes for testing. An improved telematics solution is also designed to transmit engine data from the equipped port vehicles to HydraLytica and provide comparative figures for fuel consumption and emissions. Management indicated that several pilot projects would launch in the third quarter.
If HydraGEN™ proves itself in everyday use, these references could convince additional customers. According to the company, discussions are also underway in Cambodia, Indonesia, and Japan. These are not yet confirmed orders. However, if operators gradually retrofit their fleets, Vietnam could become the starting point for broader expansion. This presents significant leverage for investors.
CEO Kevin Unrath is ramping up sales efforts. On August 18, dynaCERT announced an international program for customer meetings and sales partners. At the 24-hour truck race in Le Mans in late September, dynaCERT, together with its French sales partner IPMD and the Dakar team NRS, presented rally trucks equipped with HydraGEN™. At the same time, the company aims to reduce its reliance on the road logistics market alone. dynaCERT was also represented at Breakbulk Americas in Houston in September. TOC Americas in Colombia is scheduled for October, and Breakbulk Asia in Singapore for November. These events must result in orders of a measurable volume.
The current figures show just how early dynaCERT still is in the marketing phase. In the second quarter of 2026, revenue rose to approximately CAD 169,000, up from just under CAD 56,000 in the same period the previous year. In the first half of the year, however, they came in at approximately CAD 207,000, below the just over CAD 355,000 recorded in the previous year. This was offset by a net loss of CAD 3.81 million and an operating cash outflow of CAD 3.61 million.
At the end of June, Spielraum secured CAD 5 million in financing: convertible bonds with a two-year term and a 6% interest rate, supplemented by warrants. At the end of the first half of the year, dynaCERT had CAD 5.05 million in cash and cash equivalents. This will help expand the business. However, interest expenses are a burden.
The stock remains a speculative bet on a commercial breakthrough. Technology, regulatory approval, and initial customer projects form the foundation. Larger follow-up orders from Vietnam would now send a strong signal. If the transition to a repeatable business model succeeds, dynaCERT could be revalued on the stock market. The stock is currently trading at CAD 0.10 (EUR 0.06). Analysts at the Augsburg-based financial services firm GBC Research set the price target at CAD 0.75 or EUR 0.48, seeing a profit potential of over 700%.
From an investor’s perspective, October 7 should therefore be a must-attend event on the calendar. On that day, CEO Kevin Unrath will speak at the 20th International Investment Forum (IIF), a virtual investor event that is also open to retail investors. At the IIF, information about dynaCERT that the market has not yet picked up on may also come to light. You will find a registration link for the event at the end of the article.
Bechtle: Full Order Books and Higher Targets
At Bechtle, growth is picking up pace. In the second quarter, revenue rose 16.5% to EUR 1.7 billion, and pre-tax profit increased 20.1% to EUR 80.2 million. At EUR 3.5 billion, the order backlog reached a record high at the end of June. Demand is coming from the industrial and public sectors. For 2026, the IT service provider now expects revenue and pre-tax profit to grow by 5 to 10% each; previously, the forecast was 0 to 5%.
At the Baader Investment Conference, which took place recently in Munich during Oktoberfest and was accordingly well attended, CFO Christian Jehle expressed confidence. According to Jehle, order intake has recently grown faster than business volume. The final quarter, which is particularly important seasonally, is expected to contribute significantly to the full-year results. According to the CFO, Bechtle can continue to pass on higher prices to customers.
Jehle sees additional opportunities in artificial intelligence: Customers need advice and support, while internally, AI is expected to make processes more efficient. He attributed the weak margins in 2025 to investments and integration costs following acquisitions. However, efficiency gains and synergies are expected to improve profitability again in the future.
Based on the analyst consensus for share price and earnings estimates, Bechtle is trading at around 16 times its expected 2027 earnings. This appears reasonable given the growth recovery. Delayed customer projects and acquisition integration remain risks, however. The record order backlog, however, provides a solid foundation for a strong finish to the year. Analysts are accordingly confident: There are 12 “Buy” recommendations, compared to 1 “Hold” recommendation and 2 “Sell” recommendations. With an average price target of just under EUR 43, analysts see around 25% upside potential. For a long-term investment portfolio, Bechtle shares remain an option as a diversifying holding.
MLP: Profit Surge with Prospects for More
According to Baader, MLP was also among the positive surprises at the Munich Conference. The financial services provider has established a broad presence in wealth management, retirement planning, and insurance. In the first half of the year, total revenue rose by 10% to EUR 583 million. Operating profit (EBIT) even jumped by 41% to EUR 60.4 million. Assets under management reached EUR 68.8 billion at the end of June, providing a growing foundation for future revenue.
Of particular interest are the performance-based fees from the asset management division FERI. These can generate significant additional profit contributions if the managed investments perform well. MLP had already slightly exceeded the approximately EUR 8 million budgeted annually for this purpose in the first half of the year, according to Baader in Munich. If financial markets remain favourable, an upward revision of the annual forecast could be possible, as some conference participants at the Wiesn rumoured as the evening wore on. Officially, the EBIT target remains at EUR 100 to 110 million.
By 2028, MLP aims to increase EBIT to EUR 140 to 155 million, with total revenue of EUR 1.3 to 1.4 billion. Increased business with family and corporate clients, as well as the expansion of wealth management, are expected to help achieve this. Current consensus estimates put the 2027 P/E ratio around 12, with an expected 2026 dividend yield of about 4.1%. This represents an attractive combination of growth, valuation, and dividends.
Investors should, however, bear in mind that performance-based fees fluctuate and weaker capital markets can slow earnings momentum. Analysts are consistently positive on MLP. Currently, there are 6 “Buy” recommendations and no “Hold” or “Sell” ratings. On average, however, experts estimate the fair value at just under EUR 11—a mere 11% above the current share price.
dynaCERT offers the greatest potential for positive operational surprises and the highest price leverage, but it also requires the highest risk tolerance. Bechtle stands out with a record order backlog, while MLP boasts rising earnings and a moderate valuation.
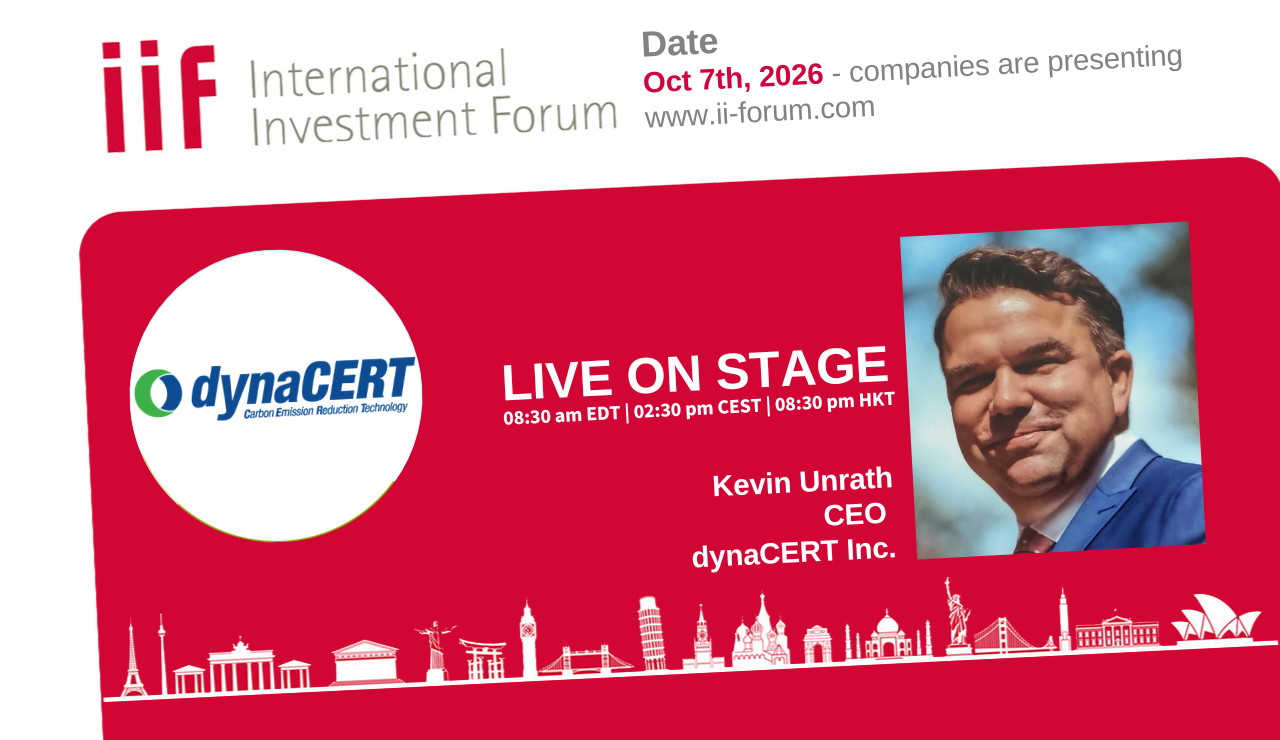
Attending investor conferences outside the mainstream can reveal information that the broader market has not yet priced in. Investors should therefore listen closely on October 7 during dynaCERT’s presentation at the International Investment Forum when CEO Kevin Unrath takes the stage at 2:30 pm CEST. Click here to register:
https://us06web.zoom.us/webinar/register/WN_KxUBth5WSYagM_MwU_P4fw#/registration
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a “Transaction”). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.