
K+S: How the Fertilizer Giant Is Securing Tomorrow’s Crop Yields
With energy prices soaring, food production must get creative! As one of the world’s leading suppliers of potash and magnesium products, K+S is an indispensable foundation for global food production. The company supplies the essential nutrients that plants need to remain resilient to drought and disease despite climate change. In light of rising energy prices, K+S faces the challenge of transitioning its own highly energy-intensive fertilizer production to CO₂-neutral processes. At the same time, the Group is investing heavily in research for customized, more efficient fertilizer solutions that minimize nutrient loss in the soil. Through these targeted innovations, K+S helps farmers sustainably increase yields per hectare while complying with strict environmental regulations. Amid renewed discussions about agricultural diesel, such highly efficient specialty fertilizers ease the burden on farmers by reducing the number of passes needed in the field. In this way, the company is positioning itself as a strategic partner for a future in which resource scarcity and climate protection must go hand in hand. The stock has experienced a roller-coaster ride amid the Middle East conflict. At current prices around EUR 16.60, the LSEG consensus price target of EUR 16.94 offers little upside potential. Furthermore, only 5 out of 17 analysts issue a specific “Buy” recommendation.
Bayer Deal Ignites Next Phase: MustGrow Biologics on the Verge of an Operational Breakthrough
The agricultural industry faces a paradoxical challenge: it must produce more on less fertile soils while simultaneously reducing the use of conventional inputs. This is where biological agricultural technology takes on strategic importance, because according to a recent study in Nature Food, soil health accounts for about 12% of global variations in crop production. MustGrow Biologics addresses this structural shift with a patented platform based on natural mustard compounds and has now clearly focused on two proprietary products: TerraSante™ for biofertility and the pre-registered TerraMG™ for biological crop protection. What is exciting is that the narrative is increasingly shifting from research and regulatory approval toward industrial scaling. Although TerraSante™ revenue in the second quarter of 2026 was still below the prior-year figure, the company attributes the lack of higher sales to production bottlenecks at contract manufacturers and expensive air freight. Nevertheless, TerraSante™ revenue has already reached CAD 0.9 million from the beginning of the year to mid-August, up more than 46% from total revenue in the prior year. The key operational lever now lies in the shift from cost-intensive air freight to significantly cheaper ocean freight, as well as in new production lines at contract manufacturers, which are expected to enable higher volumes. This could turn the previous bottleneck into a growth accelerator.
Even more important for the valuation, however, is the platform’s second pillar. Through its exclusive partnership with Bayer for Europe, the Middle East, and Africa, TerraMG™ has gained an industrial gateway that extends far beyond the company’s current size. In August, the first significant milestone payment from Bayer was received, while MustGrow anticipates investments from its partner totaling approximately USD 35 to 40 million over the next 5 to 7 years for development, regulatory approval, and market launch. This enables the Canadian company to advance its technology internationally without bearing the full costs of global commercialization. At the same time, the group has divested its low-margin third-party product business, thereby significantly sharpening its focus on its proprietary product platform. The latest figures already offer a glimpse of the potential earnings momentum: Despite lower TerraSante™ sales, MustGrow generated a net profit of CAD 0.4 million from continuing operations in the second quarter, driven by CAD 1.4 million in licensing revenue.
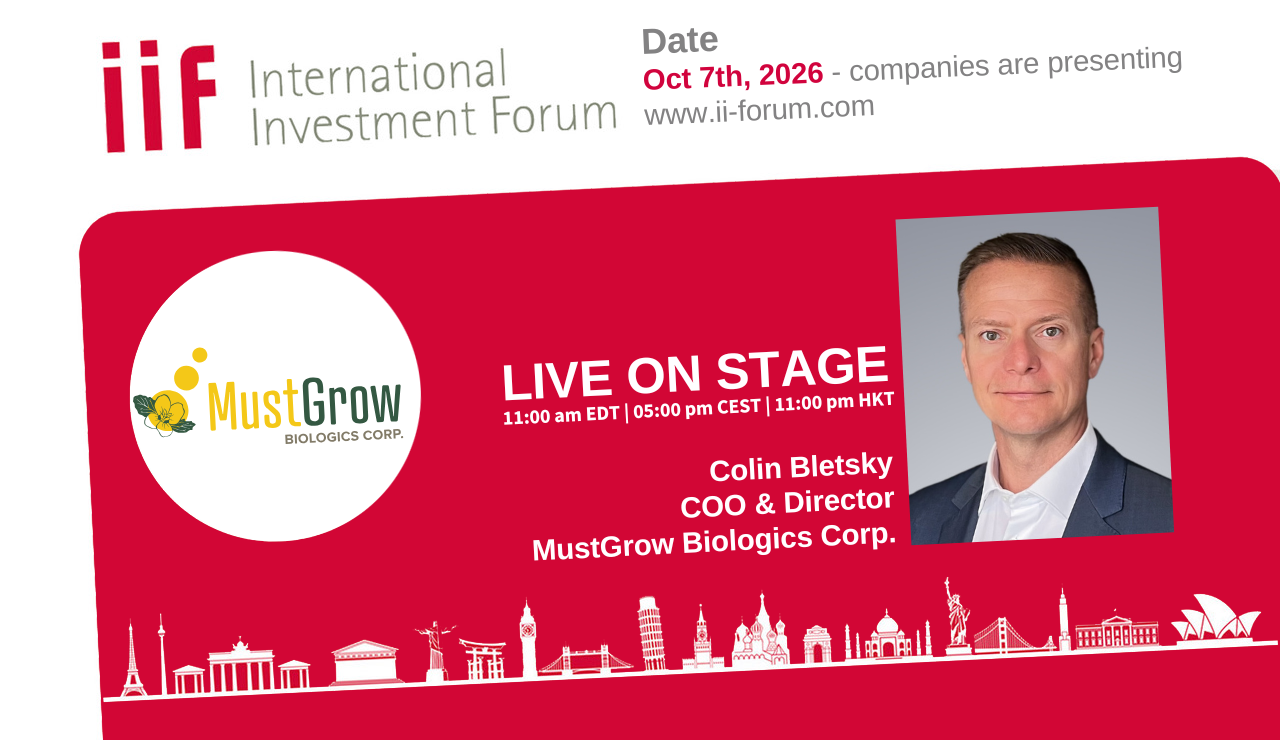
On October 7, COO Colin Bletsky will make an appearance at the 20th International Investment Forum (IIF). He will outline the emerging company’s medium-term growth strategy.
Against this backdrop, the research firm GBC expects revenue to rise from CAD 4.5 million in 2026 to CAD 14.05 million in 2027 and CAD 31.56 million in 2028, with EBITDA improving from a loss of CAD 4.35 million to a profit of CAD 8.46 million. The CAD 3.74 million financing round completed in June provides the necessary foundation to fund inventory and the next phase of growth. With approximately 110 granted and pending patents, Bayer validation, and an upcoming production ramp-up, MustGrow has several attractive levers. This creates an exciting, timely mix of factors for the stock.
Nel ASA: Green Hydrogen for Farmland
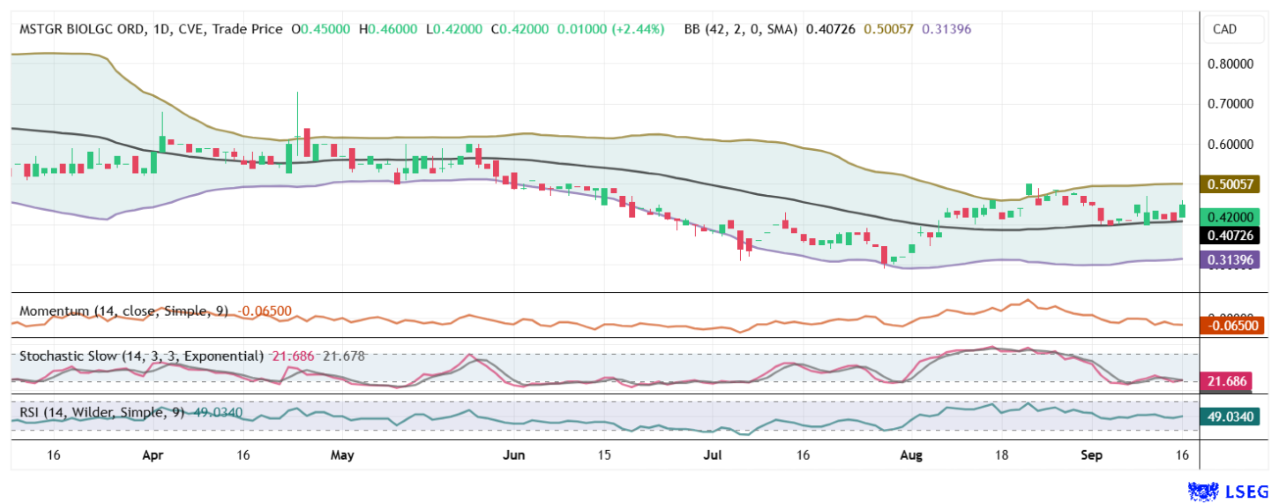
The Norwegian hydrogen company Nel ASA is playing a key role in the energy transition by expanding its production capacity in Europe. This shift is also significantly affecting sustainable agriculture. As recently announced, a new partnership with the Scottish industrial equipment supplier Hydrasun is bolstering the installation of innovative PEM electrolysers on the European market. These highly advanced electrolysers use electricity to split water into hydrogen and oxygen, thereby forming the technological foundation for zero-emission energy sources. This green hydrogen is of central importance for sustainable food production, as it serves as a clean raw material for the synthesis of environmentally friendly fertilizers. Conventional nitrogen fertilizers are mostly based on fossil natural gas, whereas the use of the new Nel technology enables the transition to decarbonized agricultural chemicals. A key technological advantage of PEM electrolysers is their compact design and ability to adapt output quickly to a fluctuating electricity supply. This enables farms and rural regions to use volatile solar or wind power directly on-site to convert the intermittently available energy into storable hydrogen. This cleanly produced hydrogen can subsequently be used as an alternative fuel to gradually replace conventional agricultural diesel in tractors and harvesters. A reliable, regional supply of such electrolyser systems protects the food industry in the long term from unpredictable price spikes in international fossil fuels. Nel stock delivered nearly 100% short-term gains in April/May, but has since returned to a 5% return for the year. Not much of a reward for this ultra-volatile stock.
The financial markets remain highly volatile. The underlying trend, however, is positive, which deviates from historical patterns given the rising capital market interest rates. The food and agriculture sector is repeatedly taking centre stage due to the issues surrounding the Strait of Hormuz. This increases the appeal of stocks in this sector. A balanced investment strategy that combines blue-chip and small-cap stocks smooths portfolio returns and reduces risk.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.