

- MTY Food Group (TSX:MTY) reported lower revenue and earnings in the third quarter, but continued to generate strong cash flow and reduce debt despite ongoing consumer spending pressures
- The company concluded its strategic review and determined that focusing on operational efficiency, franchising growth, and shareholder returns offers the best path forward
- Management increased the quarterly dividend by 35% to $0.50 per share and plans to resume share buybacks, showing confidence in the company’s long-term outlook
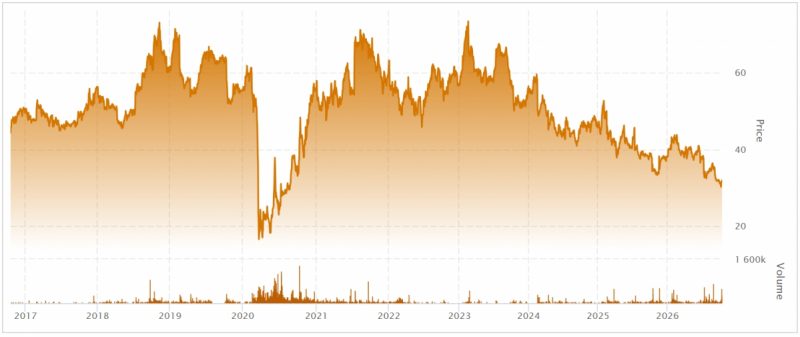
- MTY stock (TSX:MTY) last traded at C$32.04
For investors following dividend growth stories on the TSX, MTY Food Group (TSX:MTY) has delivered news worth pausing for.
While the restaurant franchisor reported mixed third-quarter fiscal 2026 results amid a challenging consumer environment, management also announced a significant increase in its shareholder return strategy, highlighted by a 35% dividend hike and plans to resume share repurchases.
A quarter with more mixed results than a tossed salad
During the 13-week period ended August 30, 2026, MTY generated net income attributable to shareholders of C$24.8 million, or $1.08 per diluted share, compared with C$27.9 million, or C$1.22 per diluted share, in the prior-year period. Revenue declined 7.1% year over year to C$277.7 million, reflecting lower sales from corporate-owned restaurants and weakness within its retail segment.
Consumer spending pressures continued to weigh on operating performance. Same-store sales declined 1.9% during the quarter, with Canada remaining relatively stable while U.S. and international operations experienced larger declines. System-wide sales held steady at approximately C$1.5 billion, supported by the company’s diversified portfolio of restaurant brands.
Despite softer sales trends, MTY’s franchise business remained resilient. Franchise segment revenue increased 1.6% year over year, while normalized EBITDA margins held steady at 54%. The company’s asset-light franchising model continues to be the primary source of profitability within the organization.
Cash flow and balance sheet remain areas of strength
One of the more encouraging aspects of MTY’s quarter was its continued ability to generate cash. Free cash flow, net of lease payments, reached C$28.5 million, or C$1.25 per diluted share, compared with C$25.8 million, or $1.13 per diluted share, a year earlier. Operating cash flow totaled $37.6 million during the quarter.
Management also continued reducing leverage, repaying C$14 million of long-term debt during the quarter and more than C$61 million over the past year. At quarter end, MTY held C$70.6 million in cash while carrying C$585.7 million in long-term debt.
These figures suggest that despite ongoing pressures within the restaurant sector, the company continues to generate sufficient cash flow to support debt reduction and shareholder distributions.
Straight from the galley
“During the third quarter, our franchising segment showed impressive resilience despite facing continued pressure on consumer spending and a challenging operating environment,” MTY’s CEO, Eric Lefebvre, said in a news release. “Despite these headwinds, our asset-light and diversified model continued to generate strong free cash flows, and we remained focused on executing our strategic plan.”
Business review ends with a focus on shareholders
Perhaps the most significant announcement was the conclusion of a business review process that began in November 2025. During that review, the board evaluated a range of alternatives, including the potential sale of all or part of the business. Following its assessment, management and the board concluded that the best path forward is to continue executing MTY’s current strategy while emphasizing efficiency, simplification, and disciplined capital allocation.
The company outlined several initiatives, including optimizing its brand portfolio, expanding its focus on asset-light franchising operations, streamlining certain functions, and increasing direct returns to shareholders.
Management stated that, at current valuations, MTY itself represents a more attractive investment opportunity than pursuing additional acquisitions. As a result, the company intends to prioritize share buybacks and increased dividend payments.
Dividend growth takes centre stage
For income-focused investors, the headline announcement was MTY’s decision to increase its quarterly dividend from $0.37 per share to $0.50 per share, representing a 35% increase. The new dividend will be paid on November 13, 2026, to shareholders of record as of November 3, 2026.
The increase follows a 12% dividend raise announced earlier in 2026, continuing a multiyear pattern of dividend growth. Management has pointed to the company’s cash-generation capabilities and disciplined capital allocation strategy as key factors supporting higher shareholder distributions.
What’s interesting is that MTY’s dividend payout ratio remains relatively conservative at roughly 28% to 30% of earnings, suggesting the company retains flexibility to invest in its operations while returning capital to shareholders.
Order up!
MTY enters the remainder of fiscal 2026 facing a familiar challenge: balancing slower consumer spending and modest sales declines against the strengths of its franchise-heavy business model. The company’s operating results indicate that demand remains uneven across parts of its network, particularly outside Canada.
At the same time, strong cash flow generation, ongoing debt reduction, share repurchase plans, and a substantially higher dividend suggest management is confident in the company’s long-term outlook. For investors, MTY increasingly appears to be transitioning from a growth-through-acquisition story toward one focused on capital returns and disciplined execution.
MTY stock (TSX:MTY) closed trading 1.94% higher at C$32.04 but has lost 15.98% since the year began.
Join the discussion: Find out what the Bullboards are saying about MTY Food Group and check out Stockhouse’s stock forums and message boards.