
Zefiro Methane: Hidden champion with fresh capital
Zefiro offers an integrated range of services for identifying, measuring and reducing methane emissions from decommissioned, orphaned and improperly plugged oil and gas wells. The operational core of its activities is its subsidiary Plants & Goodwin, a company with more than five decades of industry experience in the US. Clients include government agencies and private companies in a growing number of US states.
Old wells can release methane, endanger groundwater and hinder land use. Methane is one of the most damaging greenhouse gases for the climate and has around 80 times the warming effect of CO₂ over the first 20 years. In addition to the considerable impact on the climate, this also poses risks of soil and groundwater contamination.
Public programmes provide support here. The US Infrastructure Act provides a total of around USD 4.7 billion for such work. Most recently, Zefiro put its backlog of awarded government projects at around USD 40 million, with terms running until June 2029. These include an Ohio contract worth USD 19.6 million and a contract from the Great Lakes region worth USD 11.5 million.
Additional growth potential arises from demand from private landowners and companies whose land contains decommissioned or leaking oil and gas wells. This includes, in particular, land intended for new construction projects, industrial facilities or data centres. Old wells can lead to considerable environmental and liability risks as well as costly delays in land development.
The need for remediation thus arises for several reasons, namely climate protection, safety, environmental liability and the economic reuse of land. Zefiro estimates that there are more than 2 million orphaned wells in the US. This implies market potential of up to USD 500 billion. The company can point to a high success rate in government tenders. The “bottleneck to growth” is the availability of crews and equipment. Acquisitions and their successful integration can significantly accelerate growth and expand the geographical scope of operations. Zefiro is currently active in 15 states.
Strategic growth through M&A and partnerships
The acquisition of Viking Well Service’s equipment, completed in May, expands the possibilities. The purchase price for this was USD 4.3 million. Since the acquisition, the number of framework agreements secured has increased to a total of up to seven. Five of these agreements are already generating revenue. In total, work using the acquired equipment accounted for around USD 1.54 million in revenue in August and September. Zefiro is thus well on track to achieve its target of USD 10 million in annual revenue from this acquisition.
The partnership with the US-based Well Done Foundation is of utmost strategic importance. This gives Zefiro access to remediation projects and public-sector clients. Initially, the collaboration covers ten abandoned wells in Oklahoma, with a further 20 expected to follow in 2027. In addition to new revenue potential, the cooperation strengthens Zefiro’s regional presence and opens up additional opportunities for generating and marketing emissions credits.
Figures and valuation
The company’s financial year ended on 30 June. Revenue increased by 31.1 % to USD 42.5 million. At the same time, the gross margin improved from 23.0 % to 29.2 %. Adjusted operating earnings (EBITDA) reached USD 3.8 million. The net loss narrowed significantly to USD 3.55 million from USD 10.76 million in the previous year.
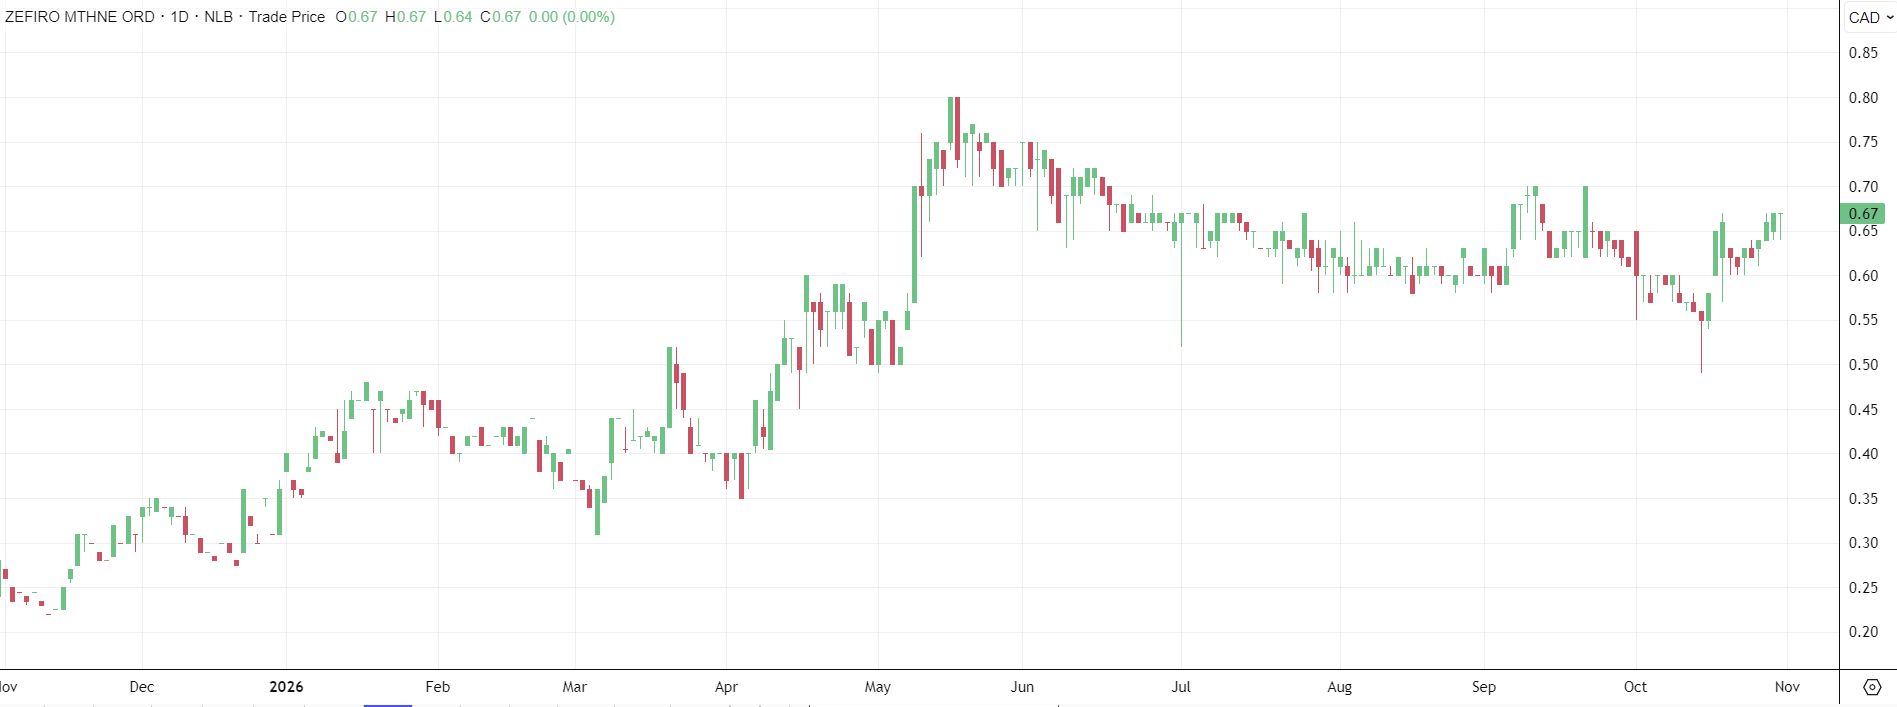
Zefiro recently completed a capital increase with gross proceeds of CAD 5 million. Around 7.58 million shares were issued at CAD 0.66, supplemented by half a warrant per share. This can be exercised over the next 30 months at a price of CAD 0.80. The funds are intended to finance working capital and general corporate purposes, but also serve to complete further acquisitions. Based on the new share count of 116.09 million and a current price of CAD 0.67 (USD 0.48 or EUR 0.43), the market capitalisation amounts to CAD 78 million or the equivalent of USD 56 million.
Potential
GBC expects revenue of USD 57.92 million and EBITDA of USD 10.02 million for the current financial year. In the opinion of the research firm’s experts, further acquisitions are strategically plausible if they close regional gaps or complement the company’s own services. The analysts set a price target of USD 1.42, equivalent to EUR 1.27, signalling significant upside potential.
In the medium term, the emissions credits business offers Zefiro considerable additional growth potential. By properly plugging abandoned oil and gas wells, the company prevents climate-damaging methane emissions and can convert the verifiably avoided emissions into tradable carbon credits under the relevant standards.
Conclusion
Zefiro covers the entire methane reduction value chain and, looking ahead, combines operational environmental services with the growth opportunities of the carbon credit market. The latest contract signings underline the successful integration of the Viking operations and open up further potential to gain market share. The recently completed capital increase provides an important foundation for this. GBC’s analysts set a price target for the stock of USD 1.42 (EUR 1.27), which is almost three times the current share price.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.