
Analysts Expect Strong Growth in Revenue and Earnings
The figures speak for themselves: a P/E ratio of 10 for the current financial year (ending June 30), revenue growth of over 30% and a solid equity ratio of around 26%. It is therefore no surprise that GBC Research sees over 200% upside potential in Zefiro Methane shares. The company’s revenue and earnings are expected to rise sharply in the coming years. Revenue is already expected to rise by 36.3% to USD 57.92 million in the current 2026/27 financial year alone. EBITDA is expected to rise to USD 10.02 million, and net profit to USD 4.21 million. For 2027/28, GBC forecasts revenue of USD 66.85 million, EBITDA of USD 12.22 million and net profit of USD 5.77 million. In the 2028/29 financial year, revenue of USD 75.21 million, EBITDA of USD 15.04 million and net profit of USD 8.31 million are ultimately expected to be achieved. This would put earnings per share at USD 0.04 in the current financial year, doubling to USD 0.08 over the following two years. From GBC Research’s perspective, the current share price of USD 0.40 appears far too low. The analysts see fair value at USD 1.50 (CAD 2.15). The shares are also traded in Germany, and the price target corresponds to EUR 1.35.
Clear Investment Case
GBC’s investment case for Zefiro Methane is clear. The analysts see the company as well positioned to benefit from a market worth billions. Since the management change, revenue, EBITDA, and the cost structure have already improved significantly. Large multi-year government contracts ensure a high degree of revenue visibility. The company is steadily expanding into new US states. At the same time, acquisitions are accelerating growth. The resumption of high-margin trading in carbon credits offers additional upside potential.
Diversified Business Model
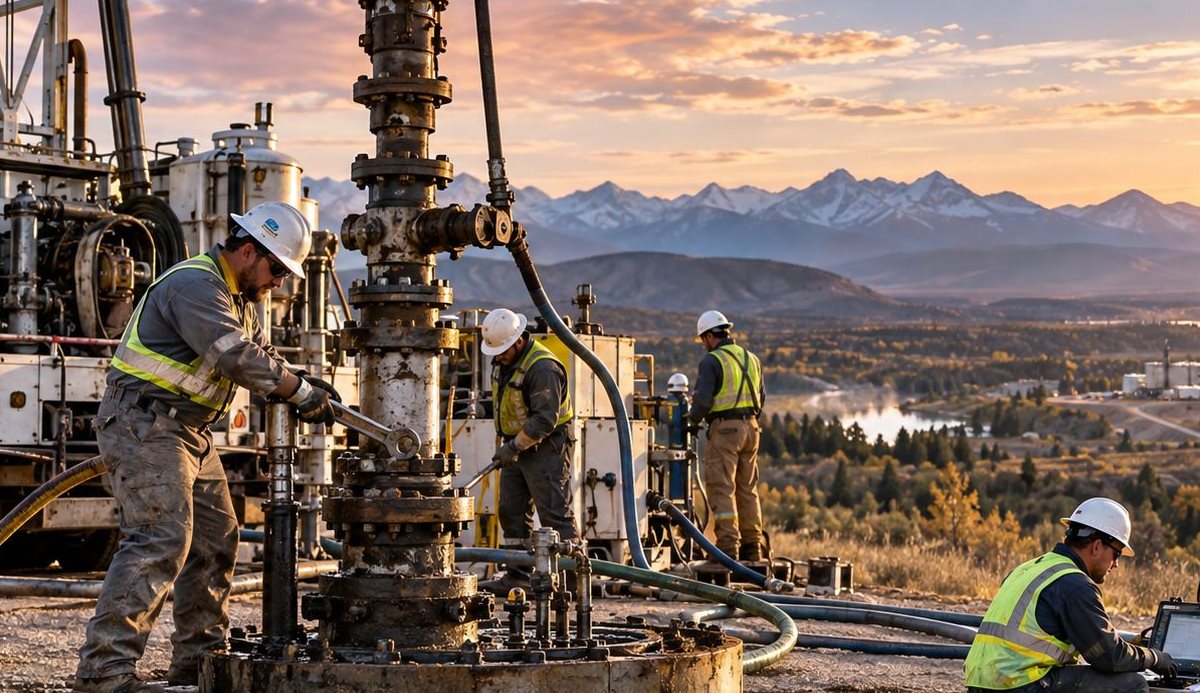
And what does Zefiro Methane’s business model look like? Its core business is the plugging of orphaned oil and gas wells. Most clients are government agencies, with funding generally provided through multi-year support programmes. These are supplemented by contracts from oil and gas companies that are legally obliged to plug end-of-life wells, as well as from infrastructure developers that require the sites for construction projects. Another business area is the measurement and monitoring of methane emissions. This area requires comparatively little investment in equipment, offers margins roughly twice as high as well plugging and can also operate during the winter months. The fourth revenue stream is the generation and marketing of carbon credits. These make it economically viable to remediate wells for which neither government funding nor private clients are available. Zefiro can therefore use its existing operational infrastructure across different revenue models, reducing its dependence on individual customer groups or government funding programmes.
On Track to Lead the USD 500 Billion Market?
The market may not sound particularly spectacular, but the figure certainly is: USD 500 billion. That is the size of Zefiro’s addressable market in the US alone. For decades, abandoned wells were not properly plugged and sealed. Many continue to leak methane. This is not only harmful to the climate but can also pose a serious threat to human life. Videos showing water catching fire and houses exploding are circulating on YouTube and social media. Politicians can no longer downplay the problem.
Many of the roughly 3.9 million abandoned or non-producing oil and gas wells need to be properly plugged and monitored. Government funding programmes have made USD 4.7 billion available nationwide. These programmes already offer Zefiro long-term business potential. At the same time, private companies must do more. US states are tightening regulatory requirements, while oil and gas companies are increasingly required to decommission their ageing wells. In addition, major infrastructure projects worth billions of dollars require contaminated sites to be remediated before construction can begin. These also include data centres. They require vast areas of land, and customers often pay a premium for faster completion. Zefiro has already received its first contracts in this area. Demand is therefore growing from several directions. For specialist remediation companies like Zefiro, this is a major opportunity. The market for qualified providers remains limited. Zefiro has already begun expanding through acquisitions as it seeks to establish itself as a market leader.
The company already operates in 15 US states and has won around 25% of government-funded decommissioning contracts in its core regions. In some tenders, Zefiro is even the only bidder.
Medium-Term Revenue Target of USD 100 Million
At the most recent International Investment Forum (IIF), Zefiro CEO Catherine Flax outlined the company’s ambitious growth targets. The latest acquisition alone is expected to increase annual revenue by around USD 10 million in the 2026/27 financial year. At full utilisation of existing capacity, Flax believes annual revenue could reach just under USD 70 million. Further organic growth and targeted acquisitions are expected to increase revenue to around USD 100 million in the medium term. The CEO illustrated how strongly demand is increasing using Pennsylvania as an example. The state previously spent only around USD 1 million annually on plugging old wells, but spending is set to reach USD 80 million this year and USD 114 million in each of the following two years. To meet rising demand, Zefiro is focusing on better utilisation of its field teams and an in-house training programme. CEO Flax also highlighted international potential. Initial enquiries for measuring methane emissions have come from the Middle East and Southeast Asia.
Conclusion: When Will the Share Price Take Off?
Zefiro has delivered so far. The past financial year ended with record figures, acquisitions to accelerate growth were completed, and the company reported transparently and regularly on developments. All this against the backdrop of a vast market. Government contracts provide a strong foundation, and the AI boom is generating high-margin additional business. It can therefore really only be a matter of time before the stock takes off. It is currently trading at around USD 0.40 or EUR 0.36. As mentioned, GBC Research’s price target is USD 1.50, CAD 2.15 or EUR 1.35.

Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as “Relevant Persons”) currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a “Transaction”). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.
Stockhouse does not provide investment advice or recommendations. All investment decisions should be made based on your own research and consultation with a registered investment professional. The issuer is solely responsible for the accuracy of the information contained herein. For full disclaimer information, please click here.